








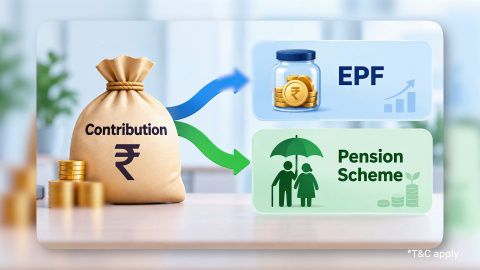
How to calculate your employers EPF contribution
-
In summary
Understanding PF calculation on salary helps employees verify their employer’s contributions and identify how each component is allocated.
- Employee contribution: Employees generally contribute 12% of basic salary and DA entirely towards EPF.
- Employer contribution: Employers generally contribute another 12%, divided between EPF and EPS.
- EPS allocation: Employers contribute 8.33% towards EPS, subject to the Rs. 15,000 pensionable wage ceiling.
- EPF allocation: The remaining employer contribution is credited to the employee’s EPF account.
- Additional payments: Employers separately pay EDLI contributions and EPF administrative charges.
Interest rate: The EPF interest rate for FY 2025-26 is 8.25% p.a.
The contribution structure may differ where the reduced 10% rate or contributions above the statutory wage ceiling apply.
How do you calculate your employer's EPF contribution?
Avoid these mistakes while booking FD
-
Your employer generally contributes 12% of the applicable EPF wages, while you contribute another 12%. The employer's 12% share is divided between the Employees' Provident Fund (EPF) and the Employees' Pension Scheme (EPS).
From 17 September 2026, the statutory wage ceiling for mandatory EPFO coverage and contributions has increased from Rs. 15,000 to Rs. 25,000 per month. The maximum EPS contribution at 8.33% of this ceiling is approximately Rs. 2,083 per month. The actual contribution can differ where an establishment contributes on higher wages or where special pension provisions apply.
- Employee contribution: generally 12% of applicable EPF wages.
- Employer contribution: generally 12%, split between EPF and EPS.
- Maximum standard EPS contribution: about Rs. 2,083 per month based on the revised Rs. 25,000 ceiling.
- EDLI: employer-funded insurance contribution is generally 0.50% of applicable wages, subject to scheme rules and the wage ceiling.
- EPFO administration charges: generally 0.50%, subject to applicable minimum charges.
- Current EPF interest rate: 8.25% for FY 2025–26, as recommended by the EPFO Central Board of Trustees and subject to Government notification.
The calculation is therefore different from older guides that still use the Rs. 15,000 wage ceiling.
What is the employer's EPF contribution structure?
-
The employer's contribution has two main components:
- EPF contribution: the portion credited to the Provident Fund.
- EPS contribution: the portion allocated towards the pension scheme.
Under the standard 12% employer contribution structure, the employer's share is commonly described as:
Component Standard rate How it works Employee EPF contribution 12% Generally credited to EPF Employer EPF contribution 3.67% Goes to EPF after the EPS allocation Employer EPS contribution 8.33% Subject to the applicable pensionable wage ceiling EDLI contribution 0.50% Employer-funded insurance contribution EPFO administrative charges 0.50% Employer-funded administrative charge The 3.67% and 8.33% figures describe the standard division of the employer's 12% share. They should not be treated as two additional contributions over and above the employer's 12%.
The employer also bears EDLI and applicable administrative charges separately.
What is the EPF wage ceiling in 2026?
The statutory EPFO wage ceiling was increased from Rs. 15,000 to Rs. 25,000 per month with effect from 17 September 2026.
This change is important when calculating the statutory contribution for employees whose applicable EPF wages fall between Rs. 15,000 and Rs. 25,000. Employees meeting the applicable eligibility conditions in this wage range can now come under mandatory EPFO coverage.
For contribution calculations, the revised ceiling means:
Maximum standard EPS contribution
Rs. 25,000 × 8.33% = Rs. 2,082.50
This is generally represented as approximately Rs. 2,083 per month, subject to payroll rounding and applicable scheme provisions.
The revised ceiling also changes the standard 3.67% calculation:
Rs. 25,000 × 3.67% = Rs. 917.50
Therefore, at a Rs. 25,000 wage base, the employer's 12% contribution is approximately:
Rs. 917.50 EPF + Rs. 2,082.50 EPS = Rs. 3,000
The precise accounting in an EPFO return can reflect applicable rounding conventions.
What is the formula for calculating the employer's EPF contribution?
For a standard contribution structure, the calculation can be expressed as:
Employer's total contribution = Applicable EPF wages × 12%
The EPS portion is:
Employer's EPS contribution = Applicable pensionable wages × 8.33%, subject to the applicable wage ceiling
The employer's EPF portion is then:
Employer's EPF contribution = Employer's total 12% contribution − EPS contribution
For the revised Rs. 25,000 statutory ceiling, the standard maximum EPS amount is approximately Rs. 2,083.
However, employees with wages above the statutory ceiling should not automatically assume that their employer contributes 12% only on Rs. 25,000. Employers may have arrangements to contribute on higher actual wages, subject to applicable EPFO rules. Higher pension contribution provisions can also apply in eligible cases.
How is the employer's EPF contribution calculated for different salaries?
The calculation depends on the wage base used by the employer. The following examples illustrate the arithmetic.
Example 1: Basic salary plus DA of Rs. 20,000
Assume Rs. 20,000 is the applicable EPF wage.
Employee contribution
Rs. 20,000 × 12% = Rs. 2,400
Employer contribution
Rs. 20,000 × 12% = Rs. 2,400
Employer EPS share
Rs. 20,000 × 8.33% = approximately Rs. 1,666
Employer EPF share
Rs. 2,400 − Rs. 1,666 = approximately Rs. 734
Therefore, the standard monthly retirement contribution is approximately:
- Employee EPF: Rs. 2,400
- Employer EPF: Rs. 734
- Employer EPS: Rs. 1,666
- Total EPF balance credited: approximately Rs. 3,134
- Total EPS contribution: approximately Rs. 1,666
Example 2: Basic salary plus DA of Rs. 25,000
At the revised statutory ceiling:
Employee contribution
Rs. 25,000 × 12% = Rs. 3,000
Employer contribution
Rs. 25,000 × 12% = Rs. 3,000
Employer EPS share
Rs. 25,000 × 8.33% = approximately Rs. 2,083
Employer EPF share
Rs. 3,000 − Rs. 2,083 = approximately Rs. 917
The standard monthly allocation is therefore approximately:
- Employee EPF: Rs. 3,000
- Employer EPF: Rs. 917
- Employer EPS: Rs. 2,083
- Total EPF balance credited: approximately Rs. 3,917
- Total EPS contribution: approximately Rs. 2,083
Example 3: Basic salary plus DA of Rs. 50,000
For a Rs. 50,000 applicable wage, the calculation depends on the contribution arrangement adopted by the establishment.
If contributions are restricted to the statutory Rs. 25,000 ceiling, the standard calculation would be:
Employee EPF
Rs. 25,000 × 12% = Rs. 3,000
Employer total contribution
Rs. 25,000 × 12% = Rs. 3,000
Employer EPS
Approximately Rs. 2,083
Employer EPF
Approximately Rs. 917
If the employer contributes on the actual Rs. 50,000 wage, the calculation would instead be:
Employee contribution
Rs. 50,000 × 12% = Rs. 6,000
Employer contribution
Rs. 50,000 × 12% = Rs. 6,000
If the standard EPS contribution remains subject to the Rs. 25,000 pensionable wage ceiling:
Employer EPS = approximately Rs. 2,083
Employer EPF = Rs. 6,000 − Rs. 2,083 = approximately Rs. 3,917
This distinction is important when reconciling a salary slip with an EPF passbook. The applicable contribution arrangement should be checked rather than assuming that every employee with a salary above Rs. 25,000 has the same calculation.
Check out different FD Rates
How does employer EPF differ from employer EPS?
Although both amounts come from the employer's contribution, they serve different purposes.
| Employer contribution | EPF | EPS |
|---|---|---|
| Purpose | Provident fund savings | Pension benefit |
| Standard share | 3.67% of applicable wages | 8.33% of applicable pensionable wages |
| Revised standard ceiling | Based on applicable contribution arrangement | Rs. 25,000 wage ceiling |
| Maximum standard EPS amount | Not applicable | Approximately Rs. 2,083/month |
| Passbook treatment | Appears under employer EPF contribution | Appears under pension contribution |
| Retirement benefit | EPF accumulation | Pension subject to EPS eligibility |
The employer's EPS contribution is not transferred to the EPF balance as ordinary provident fund savings. It is accounted for under the pension scheme.
What are EDLI and EPFO administrative charges?
The employer's cost is not limited to the 12% retirement contribution.
The Employees' Deposit Linked Insurance Scheme (EDLI) provides insurance-linked benefits under the EPFO framework. The employer generally contributes 0.50% of applicable wages, subject to the applicable wage ceiling and scheme provisions.
The employer also pays EPFO administrative charges, generally calculated at 0.50%, subject to prescribed minimum charges.
Therefore, a simplified representation of the employer's statutory outflow is:
12% EPF/EPS contribution + 0.50% EDLI + 0.50% administrative charges
This means the employer's total statutory outflow can be approximately 13% of the applicable wage base, subject to the applicable ceilings, minimum charges and scheme rules.
How can you verify your employer's EPF contribution?
Your EPF passbook can help reconcile the contributions shown by payroll with the amounts reported to EPFO.
Step 1: Check your salary slip
Identify:
- Basic Salary
- Dearness Allowance, where applicable
- EPF deduction
- Employer EPF contribution, if separately shown
- Other payroll components
EPF is generally calculated using the applicable EPF wages rather than gross salary.
Step 2: Check your EPF passbook
Log in to the EPFO Member Passbook service using your UAN credentials.
Select the relevant Member ID if you have changed employers.
Step 3: Compare the monthly entries
Look for separate entries relating to:
- Employee EPF contribution
- Employer EPF contribution
- Pension contribution
The amounts should be reconciled against the applicable contribution arrangement used by your employer.
Step 4: Check the remittance period
EPF contributions are generally required to be remitted by the 15th of the following month. For example, contributions relating to September are generally due by 15 October.
A missing or delayed passbook entry does not by itself establish non-payment because passbook updates can take time. If a contribution remains missing after allowing for processing, the matter can be raised with the employer's payroll or HR team and, where necessary, through the appropriate EPFO channel.
Is the employer's EPF contribution taxable?
Employer contributions to a recognised provident fund are subject to specific tax rules.
Under Section 17(2)(vii), the aggregate employer contribution to:
- Recognised provident fund
- National Pension System under the relevant provision
- Approved superannuation fund
is taxable as a perquisite to the extent the aggregate contribution exceeds Rs. 7.50 lakh in a financial year.
The Income Tax Department also specifies separate tax treatment for employer contributions exceeding the applicable percentage limits for recognised provident funds.
Therefore, the Rs. 7.50 lakh threshold should be considered an aggregate retirement-fund threshold, rather than an EPF-only limit.
Fixed Deposit variants
Get ROI up to
7.75% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.40% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.40% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.40% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.40% p.a.
Sole proprietor
Starting with just Rs. 15,000
What is the current EPF interest rate?
The EPF interest rate is notified for each financial year and should not be confused with the employer contribution percentage.
For FY 2025–26, the EPFO Central Board of Trustees recommended an annual interest rate of 8.25%, subject to Government notification. The contribution itself is calculated using the applicable EPF wage and contribution rules; the interest rate does not change the monthly 12% contribution calculation.
What should you check if your employer's EPF amount looks different?
A difference between your calculation and the passbook does not necessarily indicate an error. Check these factors first:
- Applicable wage base: EPF is generally linked to Basic Salary, DA and other wages covered under the applicable rules.
- Rs. 25,000 statutory ceiling: The mandatory coverage and contribution framework changed from Rs. 15,000 to Rs. 25,000 from 17 September 2026.
- Employer contribution arrangement: Some employers may contribute on actual wages subject to applicable provisions.
- EPS allocation: The employer's 12% is split between EPF and EPS.
- Higher pension provisions: Eligible employees covered by applicable higher-pension provisions can have different EPS calculations.
- Payroll rounding: Small differences can arise because contribution amounts are rounded according to the applicable payroll/ECR process.
- Processing delays: The passbook may not immediately reflect a recently remitted contribution.
Locate to your nearest FD branch

Related Articles
Frequently Asked Questions
Overview
Can I rely solely on EPF for my retirement savings?
EPF can form an important part of retirement planning, but its adequacy depends on your income, contributions, retirement age, expenses, and inflation. Review your projected corpus and consider additional savings where required.
How do I start investing in an FD to complement my EPF?
You can book a Bajaj Finance Fixed Deposit online with a minimum deposit of Rs. 15,000. Select a tenure between 12 and 60 months after reviewing prevailing rates and liquidity requirements.
How much percentage is EPF deduction from salary?
The standard employee EPF deduction is 12% of basic salary and dearness allowance. A 10% rate may apply to specifically eligible establishments under EPFO provisions.
Is EPF interest credited monthly or yearly?
EPF interest is computed monthly but it is credited annually.
Is the EPF interest rate fixed or variable?
The EPF interest rate can vary and is subject to periodic revisions by the government.
What is the method of crediting EPF interest to the subscribers?
EPF interest is credited to the subscribers' accounts by the Employees' Provident Fund Organization (EPFO).
Till what time will I get EPF interest in my account?
EPF interest is credited until the time you withdraw the EPF balance or close the account.
Will I face a loss when there is a delay in the updation of EPF interest in my passbook?
Delay in the updation of EPF interest in your passbook does not result in any financial loss.
Will I face a loss if I withdraw the EPF balance when there is a delay in the updation of EPF interest in my passbook?
Delay in the updation of EPF interest in your passbook does not impact the amount you receive upon withdrawing your EPF balance.
Is employer contribution to PF 12% or 13%?
The Employees' Provident Fund (EPF) is a widely chosen savings scheme in India, where both the employer and employee contribute 12% of the employee’s basic salary to secure future financial stability.
Is PF mandatory for 10 employees?
Generally, PF is mandatory for all establishments with 20 or more employees.
Can employer PF be less than 12%?
For most companies, the employer's PF contribution is mandated to be 12%.
How is PF Calculated in Tax?
Provident Fund (PF) is calculated as a percentage of an employee's basic salary and dearness allowance. Typically, both the employee and employer contribute 12% each to the PF. For tax purposes, employee contributions up to Rs. 1.5 lakh are eligible for deduction under Section 80C of the Income Tax Act. The interest earned and maturity amount are tax-free if certain conditions are met.
How can I check my employer contribution in EPF?
You can check your employer's contribution to your EPF by logging into the EPFO portal using your Universal Account Number (UAN). After logging in, navigate to the 'Passbook' section, where you can view your contribution details, including the employer's share.
How much PF contribution is tax-free?
The employee's contribution to EPF is eligible for tax deduction under Section 80C of the Income Tax Act, up to Rs. 1,50,000 annually.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.