








₹10,000 - ₹25 Cr
Loan of up to 80% of policy value| Funding against policies under lock-in period
Overview
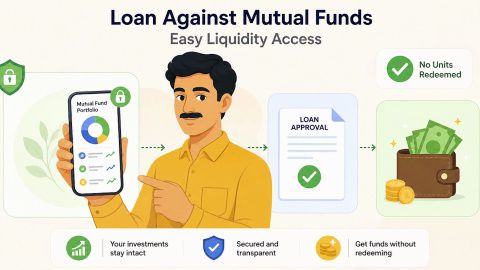
What Is a Loan Against Mutual Funds and How Does It Work
-
What is a loan against mutual funds?
In summary
A loan against mutual funds is secured credit obtained by pledging eligible units, providing liquidity without requiring their immediate redemption.
- Type: This loan against securities preserves ownership of lien-marked investments.
- LTV: Eligible portfolios may receive a limit of up to 90%.
- Rate: Current interest ranges from 7% to 12.25% per annum.
- Eligibility: Indian residents aged 21–90, whether salaried or self-employed, need KYC-compliant holdings.
- Restriction: Repayment is required before pledged units can be redeemed or switched.
What is a loan against mutual funds?
A loan against mutual funds is a secured borrowing facility where eligible mutual fund units are pledged as collateral. It allows investors to access funds without selling the selected units or immediately reducing their invested portfolio.
The lender evaluates the portfolio using four important factors:
Assessment factor What it determines Net Asset Value Current market value of the selected units Fund category Risk and volatility associated with equity, debt, or hybrid funds Applicable LTV Percentage of the portfolio value available as credit Scheme eligibility Whether the fund appears on the lender’s approved list After approval, the lender lien-marks the selected units. The borrower can withdraw funds within the available limit and pays interest on the utilised amount.
Key benefits of a loan against mutual funds
This facility can support planned or unexpected financial requirements without requiring immediate portfolio liquidation. Its principal benefits include:
- Investment continuity: Pledged units remain invested and continue participating in market movements during the loan tenure.
- No compulsory redemption: Borrowers retain ownership and avoid selling investments solely to manage a temporary cash requirement.
- Interest on utilisation: Interest is charged only on the amount withdrawn from the sanctioned credit limit.
- Digital processing: Application, portfolio assessment, lien authorisation, and account management can generally be completed online.
- Flexible tenure: Repayment options are available from seven days to 36 months, depending on the selected arrangement.
- Broad scheme coverage: More than 5,000 approved funds across over 40 asset management companies may qualify.
Potential additional credit: An increase in pledged portfolio value may improve drawing power, subject to the sanctioned limit and reassessment.
These benefits are most relevant when the requirement is temporary and the borrower has a reliable repayment plan.
Eligibility criteria for loan against mutual funds
How to apply for Bajaj Finance loan against shares
Bajaj Finance evaluates the applicant and pledged portfolio before determining the final credit limit. The general requirements are presented below:
| Eligibility parameter | Requirement |
|---|---|
| Nationality | Indian |
| Age | 21 to 90 years |
| Employment | Salaried or self-employed |
| Portfolio value | Minimum Rs. 50,000 |
| Fund ownership | Eligible units held in the applicant’s name |
| KYC status | Applicant must satisfy applicable KYC requirements |
| Scheme acceptance | Selected funds must appear on the approved list |
Eligibility does not guarantee approval. The final decision depends on fund type, current NAV, unit quantity, ownership structure, existing obligations, and internal policies.
Basic requirements
Applicants must provide accurate personal information, hold eligible mutual fund units, and maintain valid KYC records. An applicant above 70 years may require a co-borrower under applicable lending conditions.
Accepted mutual funds
Approved equity, debt, hybrid, liquid, and other eligible schemes may be accepted. The applicable LTV varies because different fund categories carry different volatility and liquidity characteristics.
The final credit limit can reach up to 90% of the portfolio value, depending on the fund type. Equity-oriented schemes generally receive a lower LTV than comparatively stable debt-oriented schemes.
Documentation required
The application generally requires three essential documents or records:
- PAN card
- Aadhaar card, passport, or voter ID for KYC verification
Consolidated Account Statement showing the mutual fund holdings
The lender may request additional information if ownership, KYC, bank, or portfolio details require further verification.
Application process for loan against mutual funds
The loan application process is digital and uses OTP-based verification. Applicants can follow these steps:
- Visit the loan against mutual funds page and select the application option.
- Enter your registered mobile number and verify it using the received OTP.
- Provide your PAN, date of birth, email address, and requested personal information.
- Enter or retrieve your mutual fund details and review the eligible schemes.
- Select the mutual fund units that you want to offer as collateral.
- Review the proposed credit limit calculated using current NAV and applicable LTV.
- Accept the terms and digitally authorise lien marking on the selected units.
Complete bank verification and submit the application for final processing.
Following successful verification and pledge confirmation, disbursal may take approximately 24 to 48 working hours. Actual timelines depend on documentation, registrar confirmation, and operational checks.
Interest rates and charges on loan against mutual funds
Features & Benefits for Bajaj Finance loan against shares
Borrowers should calculate the complete borrowing cost rather than comparing only headline interest rates. Current charges include:
| Charge | Applicable amount |
|---|---|
| Interest rate | 7% to 12.25% per annum |
| Processing fee | Up to 4.72% of the loan amount, inclusive of applicable taxes |
| Full prepayment up to Rs. 5 crore | Nil |
| Full prepayment above Rs. 5 crore | Up to 4.72% of the outstanding amount, inclusive of applicable taxes |
| Part-prepayment up to Rs. 5 crore | Nil |
| Part-prepayment above Rs. 5 crore | Up to 4.72% of the prepaid principal, inclusive of applicable taxes |
Interest is generally calculated on the amount actually withdrawn. Therefore, using only the required amount can control interest accumulation under a revolving credit arrangement.
Risks and limitations of loan against mutual funds
Pledging mutual funds provides liquidity, but it also creates repayment and collateral-related responsibilities. Important risks include:
- Market-linked valuation: A decline in NAV reduces the market value of the collateral and may affect drawing power.
- Margin shortfall: The lender may request additional units or partial repayment when the prescribed collateral margin is breached.
- Restricted transactions: Lien-marked units cannot be redeemed, switched, transferred, or pledged elsewhere during the facility.
- Interest accumulation: Keeping the withdrawn amount outstanding for longer increases the total borrowing cost.
- Possible liquidation: Continued default or an unresolved shortfall may allow the lender to sell pledged units and recover dues.
- Investment losses: Remaining invested preserves market participation, but it also exposes the portfolio to possible depreciation.
Scheme limitations: Funds outside the lender’s approved list cannot support the credit limit, regardless of overall portfolio value.
Regularly monitoring NAV, drawing power, outstanding principal, accrued interest, and margin alerts can help borrowers manage these risks responsibly.
Read more: things to know before taking loan against mutual funds
Conclusion
Eligibility criteria for Bajaj Finance loan against shares
A loan against mutual funds can provide short-term liquidity while allowing eligible investments to remain market-linked. Its value lies in lien-based borrowing, interest on the utilised amount, flexible tenure, and digital account management. However, the facility introduces interest costs, repayment obligations, NAV-related margin risks, and possible liquidation after default. Compare these considerations with redemption costs and borrow only when a dependable repayment source is available.
Loan against your assets


Loans Against Securities
Related Articles

Frequently asked questions
General
What is a loan against mutual funds?
A loan against mutual funds is secured credit obtained by lien-marking eligible mutual fund units. You retain ownership, while the available amount depends on portfolio value and applicable LTV.
Who can apply for a loan against mutual funds?
Any individual investor who owns mutual fund units held in demat or non-demat form can apply. You must meet basic eligibility criteria such as age, KYC compliance, and maintain a portfolio with accepted fund types.
Who can apply for a loan against mutual funds?
Indian residents aged 21–90 who are salaried or self-employed may apply, provided they satisfy KYC requirements and hold approved mutual funds worth at least Rs. 50,000.
What types of mutual funds are eligible for a loan?
Loans are typically offered against equity, debt, or hybrid mutual funds from SEBI-registered AMCs. The eligibility may vary by lender, and only select funds may be approved under their list of accepted securities.
How much loan can I get against my mutual fund units?
The loan amount depends on the Loan-to-Value (LTV) ratio, which can go up to 90% of the fund’s market value. The final sanctioned amount also depends on your portfolio and the lender’s assessment.
Will I still earn returns on pledged mutual funds?
Yes, you continue to earn potential returns like dividends and NAV growth on your pledged mutual funds since the units remain in your name. However, access to selling or switching them is restricted during the loan tenure.
Is the loan disbursed instantly?
Loan disbursal is usually quick, especially with digital applications. With Bajaj Finance, funds are often disbursed within 24 to 48 hours of successful pledge and approval, subject to documentation and lender’s internal checks.
What happens if the value of my mutual funds drops?
If the NAV falls and the LTV exceeds permissible limits, the lender may ask for margin maintenance. You might need to pledge additional securities or partially repay the loan to restore the required margin.
How can I apply for a loan against mutual funds with Bajaj Finance?
You can apply online through the Bajaj Finance website by logging in, entering your portfolio details, and completing KYC. After verification and pledge setup, funds are quickly disbursed into your account.
How is the loan amount determined?
The loan amount is determined based on the market value of your mutual fund holdings and the lender’s Loan-to-Value (LTV) ratio, which typically up to 80% of the mutual fund’s current value.
Can I continue investing after taking out a loan?
Yes, you can continue investing in mutual funds even after taking a loan. However, the pledged units remain under lien and cannot be redeemed or switched until the loan is fully repaid.
Can I repay early or partially?
Yes, most lenders allow you to repay the loan either partially or in full before the tenure ends. There are generally no prepayment or foreclosure charges for early repayment.
How is interest charged?
Interest is charged only on the amount you utilise from the sanctioned limit and for the duration it remains outstanding. This helps you save interest costs if you withdraw funds only when required.
What types of mutual funds can be used to secure a loan?
Most lenders allow loans against equity, debt, or hybrid mutual funds that are part of their approved list. Funds with steady performance, sufficient liquidity, and transparent NAV pricing are typically considered suitable for pledging.
Which mutual funds are not eligible for loan?
Mutual funds that are highly volatile, thematic, sector-specific, newly launched, or those not included in the lender’s approved list are generally not eligible. Funds with low liquidity or irregular NAV patterns may also be excluded from loan offerings.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company(BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.