








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
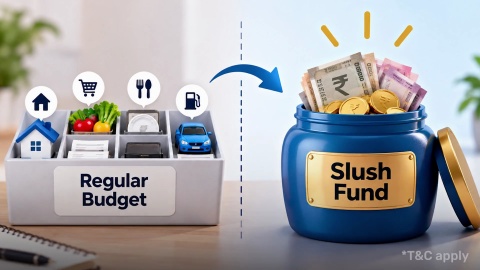
Slush Fund
In summary
A slush fund generally refers to money kept separately from normal financial records or budgets for a specific, discretionary, or undisclosed purpose. The term is commonly associated with business or political corruption, although it can also be used informally for money kept aside for unexpected expenses.
- A slush fund can be kept for discretionary or undisclosed spending.
- The term is commonly associated with secret or poorly accounted funds.
- Slush funds can occur in businesses, politics, and other organisations.
- Some informal uses of the term refer to money set aside for unexpected costs.
- An emergency fund is a clearer term for planned financial protection.
- There is no fixed amount that defines a slush fund.
- The purpose and transparency of the money determine how the term is used.
The term therefore needs to be understood from its context. In personal finance, keeping money aside for emergencies is generally better described as building an emergency fund.
What is a slush fund?
A slush fund is generally a pool of money kept secretly or without proper disclosure. In business or political contexts, the term usually has a negative meaning because it is associated with money being used for unauthorised, dishonest, or illegal purposes.
The term can also be used informally for money kept to meet unexpected costs. However, in a personal financial planning context, calling this an emergency fund is clearer.
This is different from a mutual fund, which pools money from investors and invests it according to a defined investment objective and regulatory framework.
What are the different types of slush funds?
The term can be used in different contexts. These are not necessarily separate regulated financial products; they describe situations in which the term may be used.
- Political slush funds: Money associated with political activity that is kept or spent without the disclosure or oversight expected under applicable rules.
- Corporate slush funds: Money maintained by a business outside normal controls and potentially used for unauthorised payments, undisclosed benefits, or other improper purposes.
- Government-related funds: Undisclosed or restricted pools of public money that may be associated with activities requiring confidentiality. Their treatment depends on the applicable legal and accounting framework.
- Non-profit slush funds: Money associated with a charitable or non-profit organisation that is diverted from its stated purpose or inadequately disclosed.
- Foreign-account slush funds: Money held through overseas accounts or structures where the purpose or ownership is concealed. The legality depends on the source of the funds and applicable reporting and tax rules.
- Lobbying-related funds: Money used to support lobbying or influence activities. Such spending may be legal where properly authorised and disclosed, but secrecy or non-compliance can create concerns.
The important point is that the label alone does not establish whether a particular transaction is illegal. The facts, purpose, records, disclosures, and applicable laws matter.
What are slush funds used for?
The uses associated with a slush fund depend on the context.
In business or political discussions, the term may describe money used for undisclosed payments, improper benefits, influence, or other activities that are kept outside expected transparency and oversight.
In informal personal-finance usage, people may use “slush fund” to describe money kept outside their regular budget for unexpected or discretionary expenses. For example, someone may keep a separate reserve for an urgent repair or an unplanned expense.
However, it is better to call this an emergency fund when it is intended for unexpected essential costs. A fixed income mutual fund, for example, is an investment product and should not be treated as a substitute for an accessible emergency reserve simply because it may be used for financial planning.
How does a slush fund work?
A conventional slush fund involves money whose source, purpose, or use is not properly disclosed or monitored. This lack of transparency is what distinguishes it from an ordinary business budget or personal savings account.
For personal financial planning, a different approach is more appropriate. You can set a clear savings goal, keep the money separately, and record how much you have saved and when it is used.
If you are separately considering systematic investing, an SIP investment provides a transparent and regulated way to invest a fixed amount at regular intervals. A step-up SIP can allow the investment amount to increase at defined intervals. Neither is a replacement for an emergency reserve.
What is an example of a slush fund?
Consider two different situations.
Legitimate personal reserve: Ravi earns Rs. 60,000 a month and saves part of his income separately to cover unexpected medical or household expenses. This is better described as an emergency fund.
Undisclosed business fund: A company diverts money into an account that is not properly recorded and uses it for payments that have not been authorised or disclosed. This is the type of arrangement commonly described as a corporate slush fund.
The difference is not simply whether the money is kept separately. Its purpose, authorisation, accounting, and transparency are important.
What is the history of slush funds?
The term has a maritime origin. “Slush” was used for leftover cooking fat on ships. The fat could be collected and sold, with the proceeds forming a separate pool of money.
Over time, the expression developed a broader meaning associated with money kept for unofficial or undisclosed purposes. This history helps explain why the term can refer to a separate pool of money, while its modern usage often carries a negative meaning.
How are slush funds concealed?
Where money is deliberately concealed, the methods can involve keeping transactions outside normal records, disguising the purpose of payments, or using arrangements that make the source or destination of money difficult to identify.
These practices can create legal, accounting, tax, and governance concerns. The appropriate response is not to treat every separate account as a slush fund, but to examine whether the money is properly authorised, recorded, and disclosed.
How can you create a legitimate financial reserve?
If your aim is to prepare for unexpected expenses, build an emergency fund rather than using the term slush fund.
Start by calculating your essential monthly expenses. These may include rent, food, utilities, transport, insurance, and minimum debt payments. You can then choose a reserve target based on your income stability and financial commitments.
For example, if your essential expenses are Rs. 40,000 a month and you decide to keep four months of expenses available, your illustrative target would be Rs. 1,60,000. You can build this gradually through regular transfers to a separate, accessible savings account.
A sinking fund serves a different purpose. It helps you prepare for a known future expense, such as annual insurance or planned home repairs.
How is a slush fund different from other financial concepts?
Not every separate pool of money serves the same purpose. Understanding how these concepts differ can help you identify whether you are talking about emergency savings, planned savings, discretionary spending, or a slush fund.
| Financial concept | Main purpose |
|---|---|
| Emergency fund | Unexpected essential expenses |
| Sinking fund | Known future expenses |
| Discretionary reserve | Flexible or irregular spending |
| Slush fund | Generally a secret or inadequately disclosed pool of money |
| Mutual fund | Regulated investment vehicle for pooled investor money |
If you are learning about investing, you can explore types of mutual funds, direct mutual funds, and equity funds separately from your emergency savings.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
Practical considerations
Business considerations
Terminology and usage
Can you keep money for unexpected expenses in a separate account?
Yes. Keeping emergency savings in a separate, easily accessible account can make it easier to distinguish these funds from your regular spending money. The amount you keep should reflect your essential expenses, income stability, and financial commitments. This is generally better described as an emergency fund rather than a slush fund.
Should you use an emergency fund for planned expenses?
Generally, planned expenses are better handled through a separate sinking fund. For example, if you know you will need to pay an annual insurance premium or replace an appliance, you can save towards that cost in advance. This helps preserve your emergency fund for genuinely unexpected financial needs.
How should businesses handle discretionary spending?
Businesses should set clear budgets, approval processes, and accounting records for discretionary spending. This makes it easier to track where money is going and demonstrate that expenses have been properly authorised. A legitimate discretionary budget should not need to be kept secret or recorded outside normal financial controls.
Why is transparency important when managing business funds?
Transparency helps a business track how money is received and spent, maintain accurate financial records, and meet applicable reporting requirements. When the purpose or use of money is deliberately concealed, it can create accounting, tax, governance, or legal concerns depending on the circumstances.
Is “slush fund” an appropriate term for personal savings?
It can be used informally, but it is not the clearest term for personal financial planning. If you are saving for unexpected essential expenses, “emergency fund” is more precise. If you are saving for a known future expense, “sinking fund” better describes the purpose.
Does the amount of money determine whether something is a slush fund?
No. There is no standard amount that makes a fund a slush fund. The term is more closely associated with the fund's purpose, transparency, authorisation, and how the money is recorded and used. A small undisclosed fund can raise the same type of concerns as a much larger one.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.