








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
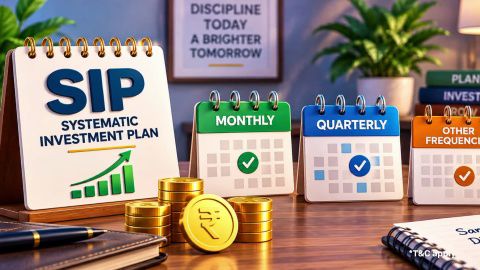
SIP Investing - How to Start, Manage & Optimise Your SIP
In summary
Mutual funds pool money from investors and invest it in different securities. They offer professional management, diversification, and different investment methods to suit various financial needs.
- Mutual funds offer professional investment management.
- Diversification helps reduce concentration risk.
- SIPs support regular, affordable investments.
- Open-ended funds generally provide liquidity.
- ELSS funds offer eligible tax deductions.
- Different schemes serve different financial goals.
- Investment returns are never guaranteed.
Mutual funds can support different investment goals, but every scheme carries risks. Compare expenses, liquidity, investment objectives, and market exposure before choosing a fund.
What are mutual funds?
Mutual funds are investment vehicles that collect money from several investors and invest it in securities such as shares, bonds, and money market instruments. An Asset Management Company (AMC) manages the scheme according to its stated investment objective. When you invest in a mutual fund, you receive units representing your proportionate share of the scheme's net assets. The value of these units is measured through the Net Asset Value (NAV), which changes according to the value of the underlying investments. Mutual funds are available in several categories, each with a different investment approach.
| Fund category | Investment approach | Primary risk |
| Equity funds | Invest primarily in shares | Equity market fluctuations |
| Debt funds | Invest in debt securities | Credit and interest rate risks |
| Hybrid funds | Combine different asset classes | Risks of underlying investments |
| Index funds | Track a specified benchmark | Market and tracking risks |
| ELSS funds | Invest mainly in equity | Equity risk and three-year lock-in |
The right category depends on your investment horizon, financial goals, and ability to tolerate losses.
What are the advantages of mutual funds?
The main advantages of mutual funds include diversification, professional management, accessibility, and different investment options. These features allow investors to participate in financial markets without managing each underlying security separately.
However, the benefits vary across schemes. Understanding how each feature works can help you identify funds that suit your requirements.
1. Professional management
Mutual funds are managed by investment professionals who oversee portfolios according to the scheme's investment objective. In actively managed funds, managers research companies, evaluate securities, and decide how to allocate investments within the permitted framework.
This allows investors to access professional research and portfolio monitoring without independently evaluating every security. Fund managers also review portfolio risks and make adjustments when required.
However, professional management does not eliminate market risk or guarantee positive returns. Fund performance depends on investment decisions, expenses, and market conditions.
2. Diversification
Mutual funds can spread investments across several companies, sectors, or asset classes. This reduces dependence on the performance of an individual security.
For example, a diversified equity fund may invest in companies operating across banking, technology, healthcare, and manufacturing. If one company performs poorly, the effect on the overall portfolio depends on its allocation and the performance of other holdings.
Diversification can provide several benefits:
- Reduced dependence on individual securities
- Exposure to multiple companies or sectors
- Lower concentration in selected investments
However, diversification does not eliminate market-wide losses. Sectoral and thematic funds may also carry substantial concentration risk.
3. Liquidity
Open-ended mutual funds generally allow investors to purchase and redeem units on applicable business days. This provides access to invested money without requiring investors to find another buyer.
However, redemption is subject to scheme-specific settlement timelines and conditions. Some mutual funds impose exit loads when units are redeemed within a specified period. Equity Linked Savings Schemes (ELSS) have a mandatory three-year lock-in for each investment.
Investors should therefore review liquidity requirements, exit loads, and redemption restrictions before choosing a scheme.
4. Tax benefits
Certain mutual fund schemes provide tax deductions under applicable income tax provisions. For example, investments in eligible ELSS mutual funds qualify for deductions under Section 80C, subject to applicable conditions under the old tax regime.
The deduction is available within the overall annual Section 80C limit of Rs. 1.5 lakh. Each ELSS investment has a three-year lock-in period, during which the invested units cannot be redeemed.
Other mutual funds do not automatically qualify for Section 80C benefits. Taxation of capital gains depends on the scheme's classification, acquisition date, holding period, and applicable income tax provisions.
5. Affordable investment amounts
Mutual funds allow investors to start with amounts specified by the selected scheme. Some SIP facilities accept contributions starting from Rs. 100, while others require higher minimum investments.
For example, an investor contributing Rs. 500 every month invests Rs. 6,000 over one year, assuming all instalments are completed. This allows investors to allocate money regularly without making a large initial investment.
You can explore available mutual fund schemes and compare their minimum investment requirements.
6. Regulatory oversight and transparency
Mutual funds in India are regulated by the Securities and Exchange Board of India (SEBI). Fund houses must follow applicable requirements relating to scheme operations, disclosures, and investor protection.
Investors can access information about the scheme's investment objective, portfolio holdings, NAV, expense ratio, and Riskometer classification. These disclosures help investors understand how their money is invested.
Regulatory oversight promotes transparency and accountability. However, SEBI regulation does not make mutual funds risk-free or guarantee capital protection.
7. Systematic or one-time investment
Mutual funds allow investors to choose between regular contributions and a single investment. An SIP involves investing a predetermined amount at regular intervals, while a lumpsum investment involves contributing money in one transaction.
For example, an investor can contribute Rs. 2,000 every month through an SIP or invest Rs. 24,000 through a single purchase. Both methods provide exposure to the chosen mutual fund scheme.
The main differences relate to contribution timing, available funds, and market exposure. Neither investment method consistently delivers higher returns.
8. Automated payments
Investors can register bank payment mandates to automate their SIP contributions. Once the instructions are approved, instalments are processed according to the selected contribution schedule.
For example, an investor can register an SIP of Rs. 1,500 per month. The bank attempts to debit the scheduled amount, subject to sufficient balance and successful processing.
Automated payments support investment discipline and reduce repeated manual transactions. However, failed payments can interrupt scheduled investments, so investors should monitor their mandates and account balances.
9. Investment accessibility
Mutual fund investments can be made through fund houses, eligible digital investment platforms, and registered distributors. Investors must complete the applicable Know Your Customer (KYC) requirements before investing.
The process generally involves selecting a scheme, reviewing its risk disclosures, choosing an investment amount, and completing payment instructions. The actual steps depend on the investment channel.
Investors can gradually build a mutual fund portfolio across different categories based on their financial goals. However, adding more funds does not automatically improve diversification, particularly when their underlying holdings overlap.
10. Portfolio tracking
Mutual fund investors receive periodic information about scheme performance, holdings, expenses, and NAV movements. These disclosures help them monitor how their investments have performed.
Fund managers review portfolios and make decisions according to their stated investment objectives. Investors can compare historical performance against an appropriate benchmark and examine whether the fund continues to meet their financial requirements.
A fund's past performance does not indicate future returns. Investors should assess performance over suitable periods rather than reacting to short-term market movements.
11. Investment options for different goals
Mutual funds offer categories that serve different investment goals, risk preferences, and holding periods. Investors can choose schemes according to when they expect to need their money.
For example, someone planning for retirement over 15 years may evaluate equity-oriented schemes based on their risk tolerance. An investor with a shorter investment horizon may consider appropriate debt categories after examining their risks.
The decision should account for financial goals, investment duration, liquidity requirements, and existing asset allocation. No single mutual fund category is suitable for every investor.
What are the benefits of lumpsum investments in mutual funds?
A lumpsum investment allows investors to contribute a selected amount through a single transaction. This method can be considered when money is available for investment without requiring periodic contributions.
For example, an investor receiving a bonus of Rs. 50,000 may decide to invest an appropriate portion in an eligible mutual fund scheme. The full invested amount receives market exposure after unit allotment.
The main features of lumpsum investing include:
- One-time investment contribution
- Market exposure from the initial investment
- No recurring contribution schedule
- Investment period chosen by the investor
Lumpsum investments can also be made in eligible Money Market funds for suitable short-term requirements.
However, the investment's performance depends on the purchase NAV and subsequent market conditions. Lumpsum investing does not automatically outperform an SIP.
What are the advantages of SIPs in mutual funds?
A Systematic Investment Plan (SIP) allows investors to contribute a fixed amount to a mutual fund at regular intervals. It supports planned contributions and reduces the need to select a new investment date for every purchase.
For example, contributing Rs. 2,000 every month results in total investments of Rs. 24,000 over 12 months, assuming every instalment is completed.
SIPs also use rupee-cost averaging. When the applicable NAVs are lower, the same contribution purchases more units. When NAVs are higher, fewer units are purchased.
This mechanism spreads purchases across different market prices. However, it does not eliminate market risk or guarantee profits.
What are the advantages of mutual fund STPs?
A Systematic Transfer Plan (STP) allows investors to move predetermined amounts between eligible schemes of the same fund house at regular intervals.
For example, an investor may transfer Rs. 5,000 every month from an eligible debt scheme into an equity scheme. This spreads the timing of investments into the destination fund instead of making the entire transfer at once.
An STP can help investors manage gradual changes in asset allocation. However, each transfer generally involves redeeming units from the source scheme, which can result in applicable exit loads and capital gains taxes.
An STP does not eliminate market volatility or guarantee higher returns.
What are the advantages of mutual fund SWPs?
A Systematic Withdrawal Plan (SWP) allows investors to withdraw a predetermined amount from a mutual fund at regular intervals.
For example, an investor can arrange monthly withdrawals of Rs. 3,000 from an eligible scheme, provided sufficient units remain available. The withdrawal amount is generated by redeeming units at the applicable NAV.
SWPs can support planned cash flow requirements without redeeming the entire investment at once. However, the payments are not guaranteed income, and withdrawals reduce the number of units held.
Capital gains taxes and exit loads may apply. If withdrawals exceed investment growth over time, the remaining investment value can decline.
What are the advantages of the mutual fund IDCW option?
The Income Distribution cum Capital Withdrawal (IDCW) option permits a mutual fund to distribute amounts to investors when a distribution is declared under the scheme's rules.
This option can provide payouts without requiring investors to submit separate redemption requests. However, distribution amounts and frequency are not guaranteed.
When an IDCW payout is made, the scheme's NAV falls by the distribution amount, subject to applicable adjustments. The payout can effectively include a return of part of the investor's capital.
Investors should compare the growth and IDCW options based on their cash flow needs and applicable tax treatment. IDCW does not represent additional returns over the growth option.
What should you consider when investing in a mutual fund?
Before investing, review the scheme's objectives, underlying assets, historical performance, expenses, and risk profile. The appropriate mutual fund depends on your financial goals and ability to bear investment losses.
The following factors can help you compare schemes.
| Factor | What to check |
| Investment approach | Active or passive management |
| Portfolio role | Suitability for your financial goals |
| Performance | Historical returns against appropriate benchmarks |
| Expenses | Expense ratio and applicable exit loads |
| Taxation | Capital gains and distribution rules |
| Fund management | Investment approach and management experience |
| Risk | Riskometer and underlying assets |
| Liquidity | Redemption timelines and restrictions |
Investors can compare actively managed strategies with a passively managed mutual fund approach. The expense ratio of the mutual fund affects the returns retained after scheme expenses. The experience and investment approach of the fund manager can also influence actively managed portfolio decisions. Past performance is not indicative of future returns.
Conclusion
Mutual funds offer diversification, professional management, investment flexibility, and access to different asset classes. Features such as SIPs, STPs, SWPs, and multiple scheme options allow investors to manage contributions and withdrawals according to their financial requirements. However, mutual fund investments remain exposed to market risks. Investors should compare expenses, liquidity, taxation, and investment objectives before choosing a scheme. Explore more than 4,000 mutual fund schemes on the Bajaj Broking website, compare investment options, and make informed investment decisions based on your financial goals, investment horizon, and risk tolerance.
Last reviewed: 12 November 2026
Mutual funds are subject to market risk. Please read the scheme-related documents carefully before investing.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
SIPs and beginner investing
Diversification and professional management
Can I run more than one SIP at the same time?
Yes, you can run multiple SIPs simultaneously, subject to the requirements of the selected mutual fund schemes. For example, you can invest Rs. 1,000 per month in one scheme and Rs. 2,000 in another. However, multiple SIPs do not automatically create a diversified portfolio.
Should beginners invest in mutual funds?
Beginners can consider mutual funds after understanding the scheme's investment objective, risk level, expenses, and recommended investment horizon. Mutual funds offer access to professionally managed portfolios without requiring investors to select individual securities.
Why are mutual funds better than stocks?
Mutual funds are not automatically better than individual stocks. They offer diversification and professional portfolio management, while individual stock investing provides greater control over security selection.
How does professional fund management benefit mutual fund investors?
Professional fund management gives investors access to research, security selection, and regular portfolio monitoring. Fund managers make decisions within a scheme's investment mandate, reducing individual research needs. However, fees apply, and returns are not guaranteed.
How do mutual funds give you diversification with small investments?
Mutual funds pool investors' money to buy a portfolio of securities, allowing even small contributions, such as Rs. 500, to provide diversified exposure. Diversification reduces concentration risk but cannot eliminate market losses or sector-specific risks.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.