








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
What is Payment, Lease & Reverse Repo Rate Everyday Finance Explained
In summary
The reverse repo rate is associated with transactions in which banks place surplus funds with the RBI and receive interest. It forms part of the monetary-policy framework used to manage liquidity and short-term interest rates.
- The RBI sets monetary-policy rates to influence financial conditions.
- The fixed reverse repo rate is currently 3.35%.
- The policy repo rate is currently 5.25%, based on RBI data.
- Higher rates can encourage banks to park surplus funds with the RBI.
- Changes in interest rates can affect debt securities and borrowing conditions.
- Mutual funds can be affected differently depending on their underlying investments.
The practical impact depends on the RBI’s broader monetary-policy framework, market expectations, liquidity conditions, and the type of financial asset being considered.
What is the reverse repo rate?
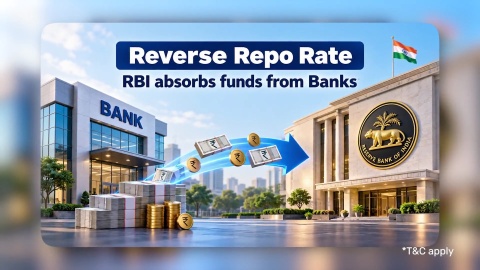
The reverse repo rate refers to the rate at which the RBI absorbs liquidity from banks against eligible securities under a reverse repo transaction. In simple terms, banks can deploy surplus funds with the central bank rather than lending those funds elsewhere.
This is the opposite direction of a repo transaction, where the RBI provides funds to banks against eligible securities.
The reverse repo mechanism can therefore influence how banks manage short-term liquidity. For context, you can also understand inflation, which is one of the economic conditions considered in monetary-policy decisions.
How does a reverse repo transaction work?
A simplified reverse repo transaction involves these steps:
- Banks have surplus funds: A bank may temporarily have more liquidity than it needs for immediate lending or other requirements.
- Funds are placed with the RBI: The bank enters an eligible transaction through the RBI’s liquidity-management framework.
- Securities support the transaction: The transaction is conducted against eligible securities under the applicable framework.
- The bank earns a return: The agreed rate determines the return on the funds deployed.
- Liquidity is absorbed: Funds placed with the RBI are temporarily removed from circulation in the banking system.
The actual operational framework can include facilities other than the fixed reverse repo facility. RBI data currently lists the Standing Deposit Facility at 5.00%, alongside the fixed reverse repo rate of 3.35%.
What is the current reverse repo rate in India?
As per RBI’s published rate data dated July 28, 2026, the fixed reverse repo rate is 3.35%. The same RBI data lists the policy repo rate at 5.25%, the Standing Deposit Facility at 5.00%, and the Marginal Standing Facility at 5.50%.
These rates can change following monetary-policy decisions or other changes to the RBI’s operating framework. Therefore, a rate stated in an older article or document should not be treated as the current rate without checking the RBI’s latest published data.
Last updated: October 2026
Why does the reverse repo rate matter?
The reverse repo rate is relevant because liquidity conditions influence borrowing, lending, money-market rates, and financial-market activity.
When banks find it more attractive to place surplus funds with the central bank, less of that surplus may be available for deployment elsewhere. Conversely, when the return from alternative uses of liquidity is more attractive, banks may allocate funds differently.
The effect is not mechanical. Banks consider credit demand, market rates, liquidity requirements, risk, regulatory requirements, and expected returns when deciding how to deploy funds.
This makes the reverse repo rate relevant to the wider money market.
How does the reverse repo rate affect inflation?
A higher rate for absorbing surplus liquidity can support tighter financial conditions by encouraging banks to keep more surplus funds with the central bank. This can moderate the amount of liquidity available for other uses.
However, inflation is influenced by several factors, including demand, supply conditions, commodity prices, exchange rates, expectations, and fiscal and monetary policies. Therefore, the reverse repo rate should not be viewed as a standalone tool for controlling inflation.
How does the reverse repo rate affect mutual funds?
The impact varies according to the assets held by a scheme.
Debt mutual funds
Debt funds invest in fixed-income securities such as government securities, corporate bonds, and money-market instruments. Changes in market interest rates can affect the prices of these securities.
When market yields rise, prices of existing fixed-rate bonds generally fall, although the magnitude depends on factors such as duration and portfolio composition. Investors can learn more about debt mutual funds before assessing how interest-rate changes may affect a portfolio.
Liquid funds
Liquid funds invest primarily in very short-term money-market and debt instruments. Their yields can respond relatively quickly to changes in short-term interest-rate conditions.
However, a change in the reverse repo rate does not guarantee a corresponding change in a liquid fund’s return.
Equity mutual funds
Equity mutual funds are not directly linked to the reverse repo rate. Their performance can be affected indirectly through changes in borrowing costs, economic growth, corporate earnings, valuations, and investor sentiment.
The broader mutual fund category therefore cannot be expected to respond uniformly to a rate change.
Reverse repo rate vs repo rate
The two rates describe transactions in opposite directions, although their roles within India’s current monetary-policy operating framework need to be considered carefully.
| Factor | Repo rate | Reverse repo rate |
|---|---|---|
| Basic direction | RBI provides funds to banks | RBI absorbs funds from banks |
| Primary purpose | Support or tighten financial conditions through lending operations | Absorb surplus liquidity through eligible operations |
| Counterparty providing funds | RBI | Banks |
| Counterparty receiving funds | Banks | RBI |
Last updated: October 2026
The repo rate is generally more prominent in discussions of the RBI’s current policy stance, while the fixed reverse repo remains one of the RBI’s available liquidity-management rates.
How does the reverse repo rate affect loans?
The reverse repo rate can influence lending conditions indirectly rather than determining retail loan rates on its own.
Changes in monetary-policy and liquidity conditions can affect banks’ funding conditions and market interest rates. Banks then consider these conditions alongside credit demand, competition, borrower risk, and their own funding costs when pricing loans.
Therefore, a change in the reverse repo rate does not automatically mean that every personal loan, home loan, or business loan will become more or less expensive.
You can use relevant funds and investment information to understand how broader financial conditions affect different financial products.
What happens when the reverse repo rate increases or decreases?
The possible effects depend on the wider economic and market environment.
- When the rate increases: Parking surplus liquidity with the RBI may become relatively more attractive, potentially supporting liquidity absorption.
- When the rate decreases: The relative incentive to park surplus funds with the RBI may decline, depending on prevailing market conditions.
- For debt securities: Market yields and bond prices can respond to changing interest-rate expectations.
- For borrowers: Lending conditions can change indirectly, although retail loan rates depend on several factors.
- For equity markets: Valuations and corporate financing conditions may respond to changes in the broader interest-rate environment.
These are possible transmission effects, not guaranteed outcomes.
Why should investors track reverse repo rate changes?
Investors can track monetary-policy changes to understand the environment in which different asset classes operate. This is particularly relevant for investors holding debt-oriented investments because bond prices and yields are sensitive to interest-rate expectations.
However, a rate decision should not automatically trigger a portfolio change. Consider your investment objective, time horizon, asset allocation, liquidity requirements, and risk tolerance.
For investors evaluating mutual fund investments, the scheme’s underlying portfolio remains more relevant than the reverse repo rate alone.
Conclusion
The reverse repo rate is an RBI liquidity-management rate associated with the absorption of funds from banks. Its significance extends beyond banking because liquidity and interest-rate conditions can influence debt markets, borrowing conditions, economic activity, and financial markets.
For investors, the key is to understand the transmission mechanism rather than react to the rate in isolation. Debt-fund investors should pay particular attention to interest-rate sensitivity, duration, credit quality, and portfolio composition, while equity investors should consider the wider effects on growth, earnings, and valuations.
Last reviewed: October 2026
Mutual funds are subject to market risk. Please read the scheme-related documents carefully before investing.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
Monetary policy and banking
Interest rates and financial markets
Understanding investment impact
Is the reverse repo rate the same as the Standing Deposit Facility rate?
No. They are separate RBI rates and facilities. The Standing Deposit Facility allows eligible banks to place funds with the RBI without the traditional collateral arrangement associated with a reverse repo transaction. RBI data currently lists the Standing Deposit Facility at 5.00% and the fixed reverse repo rate at 3.35%. Their roles should therefore not be treated as interchangeable.
Who decides changes to India’s policy rates?
The Reserve Bank of India’s Monetary Policy Committee determines the policy repo rate. Its decisions consider factors such as inflation and growth while assessing the appropriate monetary-policy stance. Other operational rates and liquidity facilities form part of the RBI’s broader monetary-policy framework. Individual rate changes should therefore be understood within the context of the overall policy stance.
Does a reverse repo rate change immediately affect bond prices?
Not necessarily. Bond prices respond to market yields and expectations, which can move before or after an RBI announcement. Investors and traders may anticipate policy changes, while global rates, inflation expectations, liquidity, credit conditions, and demand for securities can also influence prices. The effect therefore depends on the broader interest-rate environment rather than one rate alone.
Can a higher reverse repo rate always reduce inflation?
No. A higher rate can support tighter liquidity conditions, but inflation can arise from supply shocks, food and energy prices, exchange-rate movements, demand, expectations, and other factors. Monetary policy also operates with a time lag. The RBI therefore considers a range of economic indicators rather than relying on the reverse repo rate alone.
Which mutual funds are generally more sensitive to interest-rate changes?
Debt-oriented funds are generally more directly sensitive because they hold fixed-income securities whose market values can change when yields move. The extent of sensitivity depends on duration, maturity, credit quality, and portfolio composition. Very short-duration portfolios may respond differently from longer-duration portfolios, so fund category alone does not determine the impact.
Should investors change mutual fund investments whenever the reverse repo rate changes?
Not necessarily. A single rate decision does not determine whether a mutual fund remains suitable. Investors should assess their goals, investment horizon, risk capacity, asset allocation, portfolio composition, costs, and the scheme’s objective. Rate changes can provide useful economic context, but they should not automatically be treated as a signal to buy or sell a mutual fund.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.