








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
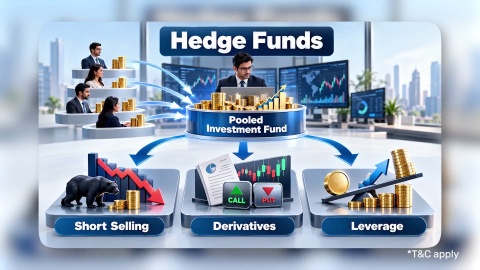
Hedge Funds Explained
In summary
A hedge is a position or strategy used to reduce the effect of an unfavourable move in another investment. Investors may hedge share, currency, commodity, or interest-rate exposure.
Key points to understand include:
- Hedging reduces risk rather than removing it.
- Options and futures are common hedging tools.
- Currency exposure can use forwards or options.
- Hedging usually involves costs or trade-offs.
- Diversification spreads risk but differs from hedging.
- A perfect hedge is difficult in practice.
A hedge can protect against a specific risk, but the protection may reduce potential gains or involve additional cost. The right approach depends on the exposure being protected and the investor's understanding of the instrument.
How does a hedge work?
A hedge works by creating an offsetting exposure to a risk already present in your portfolio. If the original investment loses value because of the risk being hedged, the second position aims to offset part or all of that loss.
For example, an investor who owns shares and is concerned about a short-term fall may buy a put option. A put gives the holder the right, but not the obligation, to sell the underlying asset at an agreed strike price, subject to the contract terms.
The protection does not make the original investment risk-free. The option costs a premium, and its protection lasts only for the period specified in the contract.
What are the main types of hedging?
The type of hedging depends on the risk you want to reduce. Investors and businesses can hedge risks related to shares, currencies, commodities, or interest rates.
| Type of hedging | What it protects against |
|---|---|
| Equity hedging | Helps reduce losses if share prices or a stock market index falls. |
| Currency hedging | Helps reduce losses caused by unfavourable exchange-rate movements. |
| Commodity hedging | Helps manage changes in prices of commodities such as gold, oil, or agricultural products. |
| Interest-rate hedging | Helps reduce the effect of changes in interest rates on investments or borrowing costs. |
The type of hedge you choose should match the specific risk you want to manage. A hedge designed for currency risk, for example, will not automatically protect you from a fall in share prices.
What tools are used for hedging?
Investors can use different financial contracts to create a hedge. SEBI identifies futures and options as common derivatives used to manage price risk.
| Hedging tool | How it works |
|---|---|
| Options | Give the buyer the right, but not the obligation, to buy or sell an asset at an agreed price. |
| Futures | Require the parties to buy or sell an asset at an agreed price on a future date. |
| Forward contracts | Allow two parties to agree privately on a future transaction at a fixed price. |
| Swaps | Allow two parties to exchange payments, often to manage interest-rate or currency risk. |
For example, an investor worried about a fall in a share price may buy a put option. A business expecting payment in a foreign currency may use a forward contract to reduce exchange-rate risk.
Some investors also use portfolio diversification to spread risk across different asset classes. Diversification can reduce concentration risk, but it is not a direct hedge because the other investments may not move in the opposite direction when losses occur.
What does a hedging example look like?
The following example is illustrative and does not represent an actual exchange contract or expected return.
Suppose Asha owns 100 shares bought at Rs. 750 each. Her total investment is Rs. 75,000. She buys an illustrative put with a strike price of Rs. 700 and pays a premium of Rs. 20 per share, or Rs. 2,000.
If the share price falls to Rs. 600:
Share loss = (Rs. 750 − Rs. 600) × 100 = Rs. 15,000
The illustrative value of the put at expiry is:
Put value = (Rs. 700 − Rs. 600) × 100 = Rs. 10,000
Therefore:
Net loss after hedge = Rs. 15,000 − Rs. 10,000 + Rs. 2,000 premium = Rs. 7,000
Without the hedge, the illustrative share loss would be Rs. 15,000. The hedge reduces that loss to Rs. 7,000 after considering the premium.
However, the Rs. 2,000 premium remains a cost even if the share price rises and the investor never needs to exercise the option.
What are the benefits of hedging?
Hedging can help reduce the effect of unfavourable price movements and make investment risk easier to manage.
| Benefit | What it means |
|---|---|
| Reduces downside risk | A hedge can help limit losses if the original investment moves against you. |
| Protects existing gains | It can help protect profits already made in an investment. |
| Helps manage uncertainty | Hedging can reduce the impact of sudden market, currency, or interest-rate movements. |
What are the limitations of hedging?
Hedging does not remove all risk and can also reduce returns or add extra costs.
| Limitation | What it means |
|---|---|
| Comes with a cost | Options may require a premium, while other hedges can involve trading costs or margins. |
| Can reduce profits | Some strategies may limit part of the upside if the investment performs well. |
| May not give full protection | The hedge may not move exactly opposite to the original investment. |
| Protection may expire | A hedge may end before the risk actually occurs. |
| Can be complex | Futures and options can create losses if their rules and risks are not understood. |
SEBI material published in October 2025 notes that hedging may be perfect or imperfect and that derivatives carry their own risks. A hedge should therefore be used as part of an overall investment strategy, not as guaranteed protection.
When may hedging be useful?
Hedging may be useful when you have a clearly identified exposure that you want to retain but partially protect. Examples include short-term downside risk in shares, foreign-currency exposure, commodity-price exposure, and interest-rate risk.
Before using a hedge, identify the risk, protection period, acceptable loss, and cost. Compare the cost with simpler alternatives, such as reducing the original position or improving diversification.
For a long-term mutual fund investor, direct derivative hedging may not always be necessary. A fund manager may use permitted derivatives within the scheme mandate and applicable rules. Review the scheme information document and portfolio disclosures when evaluating a mutual fund investment.
Conclusion
A hedge is a risk-management tool, not a guarantee against loss. It uses an offsetting position to reduce the effect of an adverse movement in shares, currencies, commodities, interest rates, or another identified exposure.
Costs, timing, complexity, and imperfect offsets can reduce the effectiveness of protection. Before using derivatives, understand the contract, possible losses, and whether a simpler risk-management approach could meet the same objective.
Last reviewed: October, 2026
Mutual funds are subject to market risk. Please read the scheme-related documents carefully before investing.
Explore Investment Tools
Articles and Insights
Frequently Asked Questions
Understanding hedging
Hedging, currency risk, and speculation
What is a hedge in investment?
A hedge is a strategy used to reduce the risk of loss in an investment. You take another position that may gain value if your main investment moves against you. For example, an investor holding shares may buy a put option to limit losses if the share price falls. Hedging reduces risk, but it does not guarantee complete protection.
How does hedging work in investing?
Hedging works by creating a position that can offset some of the loss from another investment. For example, if you own shares and expect a temporary fall in their price, you may use an option to reduce the possible loss. The hedge may also involve costs and can reduce some of the profit if the original investment performs well.
What are the common types of hedges used by investors?
Common hedging tools include options, futures, forwards, and swaps. Investors may also use different strategies to manage risks related to shares, currencies, commodities, or interest rates. The suitable method depends on the type of risk you want to reduce, the period of protection required, and the cost of setting up the hedge.
Why do investors hedge their investments?
Investors hedge to reduce the impact of unfavourable market movements. A hedge can help protect an existing investment, reduce portfolio swings, or manage risks linked to currencies, interest rates, or commodity prices. However, hedging usually involves a cost and may also reduce potential gains. It is mainly used for risk management rather than to guarantee returns.
Is hedging the same as speculation?
No, hedging and speculation are not the same. Hedging involves taking positions to reduce the risk of losses and protect investments from adverse market movements. In contrast, speculation aims to profit from anticipated changes in market prices, often involving higher risk. While hedging seeks to manage risk, speculation seeks to capitalise on potential gains.
How does hedging reduce the risk of currency fluctuations for investors?
Currency hedging can reduce the effect of unfavourable exchange-rate movements on an investment. An investor with foreign currency exposure may use forwards, futures, or options to offset part of that risk. If the foreign currency moves against the investor, gains from the hedge can help reduce the resulting loss. The hedge may not remove the currency risk completely.
What is the difference between hedging and speculation in financial markets?
Hedging starts with a risk that already exists and tries to reduce it. Speculation deliberately takes additional risk based on an expected price movement. For example, an investor may use a futures contract to protect an existing holding, while a trader may use the same type of contract to try to profit from an expected rise or fall in prices.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.