








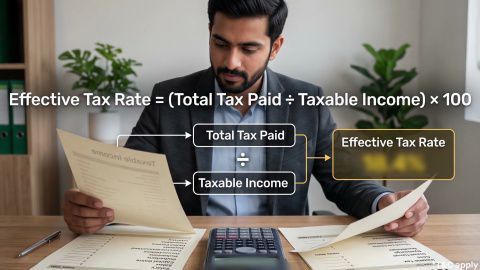
Effective Tax Rate
-
In Summary
The effective tax rate helps you measure the proportion of your income paid as tax. It differs from the marginal tax rate, which applies to the relevant additional portion of income under the applicable tax rules.
- Formula: Effective tax rate = (Total income tax liability ÷ Total income) × 100.
- Example: If your total income is Rs. 10,00,000 and your final income tax liability is Rs. 80,000, your effective tax rate is 8%.
- Marginal tax rate: This is the tax rate applicable to the relevant additional portion of income, not necessarily your entire income.
- What affects it: Your income, applicable tax regime, eligible deductions, exemptions, rebates and other relevant provisions can affect your tax liability.
Understanding these measures can help you assess your tax position and plan your finances. Your actual liability depends on the tax rules applicable to you and the relevant financial or tax year.
How is the effective tax rate calculated?
-
You can calculate the effective tax rate by dividing your total income tax liability by your total income and multiplying the result by 100.
Formula:
Effective tax rate = (Total income tax liability ÷ Total income) × 100
Where:
- Total income tax liability: The income tax payable for the relevant period after accounting for applicable tax provisions, including eligible rebates and applicable surcharge and cess.
- Total income: The income figure used as the denominator for the calculation. For a personal-finance illustration, this generally means the total income before income tax is deducted.
Use consistent figures for the same period. If you instead divide tax liability by taxable income after deductions, you calculate the tax liability as a percentage of taxable income. That is a different measure and should be labelled accordingly.
What is an example of effective tax rate calculation?
Consider a hypothetical example in which a person has an annual income of Rs. 10,00,000 and a final income tax liability of Rs. 80,000.
| Particular | Amount |
|---|---|
| Total annual income | Rs. 10,00,000 |
| Assumed final income tax liability | Rs. 80,000 |
| Calculation | (Rs. 80,000 ÷ Rs. 10,00,000) × 100 |
| Effective tax rate | 8% |
The effective tax rate is 8% because the assumed tax liability represents 8% of the person's total income.
This example is illustrative only. The tax liability of Rs. 80,000 is an assumption, not a tax calculation for a particular income level under a current tax regime. Actual tax depends on the applicable rules, the nature of income and the individual's circumstances.
What happens if you use taxable income instead?
Suppose the same person has total income of Rs. 10,00,000, taxable income of Rs. 8,00,000 and an assumed final tax liability of Rs. 80,000.
- Effective tax rate against total income: Rs. 80,000 ÷ Rs. 10,00,000 × 100 = 8%.
- Tax liability as a percentage of taxable income: Rs. 80,000 ÷ Rs. 8,00,000 × 100 = 10%.
Both calculations are mathematically correct, but they answer different questions. Always state the denominator to avoid confusion.
What is the difference between effective and marginal tax rates?
The effective tax rate measures the overall tax burden relative to total income. The marginal tax rate is the rate applicable to the relevant additional portion of taxable income.
| Basis of comparison | Effective tax rate | Marginal tax rate |
|---|---|---|
| Meaning | Overall tax liability as a percentage of total income | Rate applicable to an additional portion of income |
| Calculation | Total income tax liability divided by total income, multiplied by 100 | Determined by the applicable tax slab or special tax provision |
| What it tells you | The proportion of total income paid as income tax | How an additional amount of taxable income may be taxed |
| Main use | Understanding the overall tax burden | Understanding the potential tax impact of additional income |
| Relationship | Often lower than the marginal rate under a progressive slab system | Can be higher because different portions of income may be taxed at different rates |
For example, if your marginal tax rate is 20%, it does not automatically mean that 20% of your entire income is paid as income tax. The effective rate accounts for the overall liability relative to total income.
The relationship between these rates can vary depending on the tax regime, special-rate income, rebates, surcharge and other applicable provisions.
Which factors affect your effective tax rate?
Your effective tax rate depends on the tax liability calculated under the rules applicable to your income and circumstances. The main factors include the following.
1. Total income and its sources
Your salary, business income, interest income, capital gains and other taxable receipts may contribute to your overall tax position. Some types of income may be subject to special tax provisions rather than ordinary slab rates.
2. The tax regime you choose or are subject to
India's tax framework provides for different tax regimes with different slab rates, deductions and exemptions. The applicable regime can affect the amount of tax payable and, consequently, your effective tax rate.
The relevant provisions must be checked for the tax year in question. For example, the official guidance distinguishes assessment year 2026–27 from tax year 2026–27 onwards.
3. Eligible deductions and exemptions
Deductions and exemptions may reduce the income on which tax is calculated, where permitted by the applicable regime and law. Their availability is not universal, so you should not assume that a deduction available under one regime is also available under another.
4. Rebates, surcharge and cess
An eligible tax rebate may reduce the tax payable. Surcharge may apply to certain taxpayers above specified income thresholds, while health and education cess may increase the final liability.
The applicability and calculation of these amounts depend on the relevant tax provisions and taxpayer category.
5. The nature of your income
Different types of income may be taxed differently. For example, interest income and certain capital gains may be governed by provisions that differ from the ordinary income-tax slab rules. A reliable calculation must account for the nature of each income source.
How does the effective tax rate help with financial planning?
The effective tax rate helps you understand the overall share of your income paid as tax. It can be useful when reviewing your annual finances, comparing tax liabilities across periods and estimating how a change in income or an eligible tax provision might affect your position.
You can use it to:
- Review your tax burden: Compare the proportion of income paid as tax across years, while accounting for changes in income and tax rules.
- Understand additional income: Assess how interest, business income or another income source may affect your total liability.
- Review tax planning choices: Evaluate the effect of eligible deductions, exemptions and rebates under the applicable regime.
- Plan savings: Estimate how tax may affect the amount of income available for saving or spending.
The effective tax rate is an explanatory measure, not a substitute for a tax computation. It does not by itself determine which tax regime is preferable or which financial product is suitable for you.
How does tax affect fixed deposit interest?
Interest earned on a fixed deposit (FD) is generally taxable under the applicable income-tax provisions. The final tax treatment depends on your overall tax position, the nature of your income and the rules in force for the relevant tax year.
When evaluating an FD, consider its stated interest rate alongside the tax you may have to pay on the interest. The quoted rate is not necessarily the same as the return you retain after tax. For example, two deposits with similar interest rates may result in different post-tax outcomes for individuals with different tax liabilities.
Tax deducted at source (TDS), where applicable, is a mechanism for collecting tax in advance. The amount deducted does not necessarily equal your final income-tax liability.
If you are comparing deposit options, review the applicable interest rate, tenure, payout terms and other conditions alongside the potential tax implications. You can find current product information and terms on the Bajaj Finance Fixed Deposit page.
What are the limitations of the effective tax rate?
Although the effective tax rate is useful, it does not tell you everything about your tax position.
- It depends on the denominator: A rate calculated against total income differs from one calculated against taxable income.
- It does not show how each income component is taxed: Certain income may be subject to special tax rates or rules.
- It can change between years: Changes in income, tax regimes, deductions, rebates and legislation may alter the rate.
- It does not measure every financial cost: The calculation generally concerns income tax, not all taxes or other expenses you may incur.
- It does not replace a full tax computation: Your final liability may depend on details that a simple percentage does not capture.
For these reasons, use the effective tax rate as a summary measure and consult the applicable official guidance or a qualified tax professional for individual tax calculations.
Check out different FD Rates
The effective tax rate shows the proportion of total income paid as income tax, while the marginal tax rate indicates how an additional portion of income may be taxed. To calculate the effective rate, divide the relevant total income tax liability by total income and multiply by 100.
Always use consistent figures, identify the period being assessed and account for the applicable tax regime, deductions, rebates, surcharge and cess. When reviewing savings or investment income, consider the tax treatment alongside the stated return rather than assuming that the quoted rate represents the amount you will retain.
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
Locate to your nearest FD branch

Related Articles


Frequently Asked Questions
Overview
What is the effective tax rate in simple terms?
The effective tax rate is the percentage of your total income that you pay as income tax. If your annual income is Rs. 10,00,000 and your final income tax liability is Rs. 80,000, your effective tax rate is 8%. The example assumes the stated tax liability and does not calculate actual tax under a particular regime.
How do I calculate my effective tax rate?
Divide your total income tax liability by your total income and multiply the result by 100. For example, if your total income is Rs. 12,00,000 and your final tax liability is Rs. 96,000, your effective tax rate is 8%. Use figures from the same period and specify whether the denominator is total income or taxable income.
Is the effective tax rate the same as the income-tax slab rate?
No. An income-tax slab rate applies to a specified portion of taxable income under the applicable tax regime. The effective tax rate measures the overall tax liability as a percentage of total income. Under a progressive slab system, the effective rate is often lower than the marginal rate, although the relationship can vary with special-rate income and other provisions.
Can my effective tax rate be lower than my marginal tax rate?
Yes. Under a progressive tax system, different portions of taxable income may be taxed at different rates. Your marginal tax rate may apply to the additional portion of income in a higher slab, while your effective tax rate averages the overall tax liability against total income. Rebates, special-rate income and other provisions can affect the relationship.
Does TDS determine my effective tax rate?
No. Tax deducted at source is an amount collected in advance towards your tax liability. Your final liability is calculated under the applicable tax rules and may differ from the amount deducted. TDS may be adjusted against that liability, and an eligible refund or additional payment may arise depending on your final tax computation.
Does FD interest affect my effective tax rate?
Taxable FD interest can affect your total taxable income and overall tax liability, depending on the applicable rules and your circumstances. TDS may apply to FD interest under the relevant provisions, but it does not necessarily represent your final tax. Consider the applicable tax treatment when estimating the return you retain from an FD.
Does the effective tax rate change every year?
It can. Changes in income, deductions, exemptions, rebates, tax rates and other applicable provisions may alter your final tax liability. Even if your income remains similar, a change in the tax rules or in the composition of your income may change your effective tax rate. Compare periods using consistent definitions and the rules applicable to each year.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.