









Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
In summary
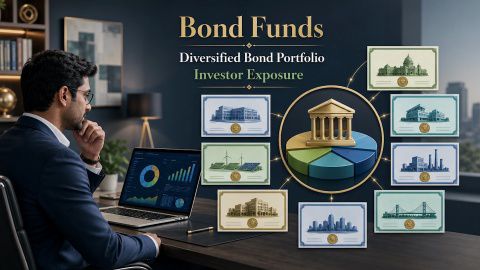
What are Bond Funds
A bond fund pools money from investors and invests it in bonds and other debt securities. The exact investments depend on the scheme's objective and category.
The key points to remember are:
- A bond fund can invest in government securities, corporate bonds and other debt or money market instruments.
- A bond fund does not have the same structure as an individual bond.
- The value of a bond fund can change when interest rates, credit conditions or market conditions change.
- Longer-duration debt securities are generally more sensitive to interest-rate movements.
- Bond funds can provide diversification because a scheme may hold several securities.
- A bond fund does not guarantee returns or protect your invested capital.
- Tax treatment depends on the type of mutual fund and the applicable tax rules. Certain debt-oriented funds fall under the specified mutual fund rules under Section 50AA of the Income-tax Act.
Before investing, check the scheme's objective, portfolio, Riskometer, duration, credit quality, costs and applicable tax treatment.
What is a bond fund?
A bond fund is a mutual fund that pools money from investors and invests it mainly in bonds and other debt securities. In India, the term “bond fund” is commonly used as a broad description. The exact portfolio depends on the mutual fund scheme and its investment objective.
Bond funds can invest in securities such as:
- Government securities
- Corporate bonds
- Treasury Bills
- Commercial Paper
- Certificates of Deposit
- Other eligible debt and money market instruments
SEBI classifies mutual fund schemes into groups such as debt schemes, and provides specific categories within debt schemes. Therefore, not every bond fund follows the same investment strategy.
You can explore different mutual fund options to understand how debt schemes differ from other mutual fund categories.
What is the difference between a bond and a bond fund?
A bond is a debt security issued by an entity such as a government or company. A bond fund is an investment vehicle that pools money from investors and uses it to buy a portfolio of bonds and other debt securities.
This distinction is important because the two investments work differently.
| Feature | Individual bond | Bond fund |
|---|---|---|
| What you buy | A specific bond | Units of a mutual fund or ETF |
| Portfolio | Usually one security unless you buy several bonds | A portfolio of securities |
| Maturity | The bond has a stated maturity date | The fund generally does not have a fixed maturity |
| Returns | Depend on the bond's coupon, purchase price, sale price and issuer | Depend on the securities held by the fund and changes in their value |
| Risk | Depends mainly on the specific bond and issuer | Depends on the fund's portfolio, duration, credit quality and market conditions |
If you buy an individual bond, you decide which security to hold. With a bond fund, the fund manager manages the portfolio according to the scheme's investment objective.
How does a bond fund work?
A bond fund pools money from many investors and uses it to invest in a portfolio of debt securities. The fund manager selects securities according to the scheme's investment objective and applicable limits.
The process can be understood in four steps:
- Investors put money into the fund: You buy units of the mutual fund scheme.
- The fund pools the money: Your money is combined with money from other investors.
- The fund invests in debt securities: The scheme buys securities such as government securities, corporate bonds or other eligible instruments.
- The value of your units changes: The NAV of the scheme can change as the value of its underlying securities changes.
The fund may receive interest or other income from the securities it holds. However, this does not mean that you receive a fixed or guaranteed return.
What happens to your money after you invest?
When you invest in a bond fund, you own units of the mutual fund scheme rather than the individual bonds held by the scheme.
The value of these units is represented by the scheme's net asset value (NAV). The NAV can change because the value of the underlying securities changes.
For example, if interest rates rise, the market value of existing fixed-rate bonds may fall. This can affect the NAV of a fund holding those bonds.
What does a bond fund invest in?
Bond funds can invest in different types of debt securities. The exact portfolio depends on the scheme's category and investment objective.
Government securities
Government securities are debt securities issued by the government. Gilt funds, for example, invest predominantly in government securities.
Government securities generally have relatively low credit risk. However, a fund investing in them can still be affected by changes in interest rates. A gilt fund is therefore not the same as a risk-free investment.
Corporate bonds
Companies may issue bonds to raise money for business requirements. Corporate bonds can have different credit ratings, maturities and interest rates.
A bond issued by a company with a lower credit rating can carry greater credit risk than one issued by a higher-rated company.
Money market and other debt instruments
Depending on its category and investment objective, a debt fund may also invest in instruments such as Treasury Bills, Commercial Paper and Certificates of Deposit.
The risk, maturity and liquidity of these instruments can vary. You should check the scheme documents to understand what a particular fund can hold.
What are the main types of bond and debt funds?
SEBI has defined several categories of debt mutual fund schemes. These categories differ mainly in terms of the securities they invest in, their maturity or duration and their investment approach.
Some categories that a beginner may come across include:
| Fund category | What it generally invests in |
|---|---|
| Short Duration Fund | Debt and money market instruments with a short portfolio duration |
| Medium Duration Fund | Debt securities with a medium portfolio duration |
| Dynamic Bond Fund | Debt securities across different durations, based on the fund's strategy |
| Corporate Bond Fund | Predominantly highly rated corporate bonds |
| Credit Risk Fund | Predominantly lower-rated corporate bonds and therefore higher credit risk |
| Banking and PSU Debt Fund | Debt securities issued by banks, public-sector undertakings and specified financial institutions |
| Gilt Fund | Government securities |
| Gilt Fund with 10-year constant duration | Government securities with a portfolio duration maintained around 10 years |
| Floater Fund | Debt instruments with floating interest rates |
The characteristics of these categories are defined by SEBI and can change when regulations are updated. Check the current scheme documents before investing.
What is a dynamic bond fund?
A Dynamic Bond Fund can invest across different maturities based on the fund's investment strategy. The fund manager may change the portfolio's duration as interest-rate conditions and market views change.
This means the fund's interest-rate exposure can change over time. You should therefore review the scheme's current portfolio and Riskometer rather than assuming that every dynamic bond fund has the same level of risk.
What is a corporate bond fund?
A Corporate Bond Fund is a debt mutual fund category that predominantly invests in highly rated corporate bonds. Under SEBI's categorisation, these schemes invest at least 80% of their total assets in AA+ and above-rated corporate bonds.
Corporate Bond Funds can still be affected by interest-rate movements. The credit quality of the securities held by the fund is also important.
What is a credit risk fund?
A Credit Risk Fund is a debt mutual fund category that predominantly invests in lower-rated corporate bonds. This means credit risk is an important factor to consider.
The fund can be affected if an issuer's credit quality deteriorates or if the issuer has difficulty meeting its payment obligations.
What is a gilt fund?
A Gilt Fund invests predominantly in government securities. Because the securities are issued by the government, credit risk is generally low.
However, gilt funds can still have interest-rate risk. A change in interest rates can affect the market value of the government securities held by the fund.
What are the benefits of bond funds?
Bond funds can provide access to a portfolio of debt securities through one mutual fund investment. However, these benefits do not mean that bond funds are risk-free or provide guaranteed returns.
The main benefits include:
- Diversification: A fund can invest in securities issued by different entities, which can spread exposure across issuers.
- Professional management: A fund manager manages the portfolio according to the scheme's investment objective.
- Access to debt markets: A mutual fund can give investors exposure to a range of debt securities without requiring them to buy each security separately.
- Choice of categories: Investors can choose from debt-fund categories with different durations, credit profiles and investment strategies.
- Potential liquidity: Open-ended mutual fund units can generally be redeemed according to the scheme's terms. Exit loads and other conditions may apply.
You can also read about fund managers and their role in managing mutual fund portfolios.
What are the risks of bond funds?
Bond funds are not risk-free. Their NAV can rise or fall because of changes in interest rates, credit quality, liquidity and other market conditions.
The main risks are explained below.
What is interest-rate risk?
Interest-rate risk is the risk that changes in market interest rates affect the value of debt securities held by the fund.
Bond prices and market interest rates generally move in opposite directions. When market interest rates rise, the prices of existing fixed-rate bonds may fall. When interest rates fall, their prices may rise.
Funds holding longer-duration securities are generally more sensitive to interest-rate movements. You can learn more about interest rate risk.
What is credit risk?
Credit risk is the possibility that an issuer may not meet its obligations to pay interest or repay principal on time.
A fund holding lower-rated corporate debt can have greater credit risk than a fund focused on higher-rated securities. You can read more about credit risk.
What is liquidity risk?
Liquidity risk is the possibility that a security may be difficult to buy or sell at the expected price under certain market conditions.
The liquidity of a mutual fund also depends on its structure and the liquidity of the securities in its portfolio.
You can also understand the broader risks associated with mutual funds.
Can you lose your principal in a bond fund?
Yes. A bond fund does not guarantee the return of your invested amount. The NAV can fall because of interest-rate movements, credit events, liquidity conditions or changes in the value of the securities held by the scheme.
This is different from a bond held until maturity, where repayment depends on the issuer meeting its obligations and the terms of the bond.
What factors should you check before investing in a bond fund?
Before investing, understand the scheme rather than looking at returns alone. Different debt-fund categories can have very different levels of interest-rate and credit risk.
The main factors to check are:
- Investment objective: Check what the scheme aims to achieve and where it can invest.
- Investment horizon: Match the scheme's duration and risk profile with the period for which you plan to invest.
- Interest-rate risk: Check the portfolio duration to understand its sensitivity to interest-rate movements.
- Credit quality: Review the credit ratings and types of issuers in the portfolio.
- Riskometer: Check the scheme's Riskometer and understand the risk level indicated for the scheme.
- Expense ratio: Review the costs charged by the scheme because expenses can affect your returns.
- Past performance: Historical returns can provide information about past performance but do not guarantee future returns.
- Liquidity and exit load: Check how you can redeem your investment and whether an exit load applies.
The portfolio diversification of the fund can also help you understand how its investments are spread across securities and issuers.
What are the key performance metrics for bond funds?
Several metrics can help you understand a bond fund. You should not rely on any one metric when evaluating a scheme.
The most useful metrics for a beginner include:
| Metric | What it tells you |
|---|---|
| NAV | The per-unit value of the mutual fund scheme |
| Yield or YTM | An indication of the potential yield of the debt securities in the portfolio, based on the applicable calculation method |
| Duration | How sensitive the portfolio may be to changes in interest rates |
| Credit quality | The creditworthiness of the securities held by the fund |
| Expense ratio | The annual operating expenses charged to the scheme |
| Historical return | How the fund performed during a past period |
Market value and NAV are different concepts. For a mutual fund, NAV is particularly important because it represents the value per unit of the scheme.
How are bond mutual funds taxed?
Tax treatment depends on the type of mutual fund and the applicable tax rules. For bond funds that fall within the definition of a Specified Mutual Fund under Section 50AA, gains from units acquired on or after 1 April 2023 are deemed to be short-term capital gains, regardless of the holding period. Such gains are taxed at the applicable rate for the investor.
From 1 April 2026, a Specified Mutual Fund includes a mutual fund that invests more than 65% of its total proceeds in debt and money market instruments, or a fund that invests 65% or more of its total proceeds in units of such a fund. The percentage is determined using the annual average of daily closing figures.
Therefore, do not assume that every fund described informally as a “bond fund” has exactly the same tax treatment. Check the scheme's classification and the tax rules applicable when you redeem your investment.
Tax laws can change. Consider the latest applicable provisions before making tax-related decisions.
How is a bond fund different from an equity fund?
A bond fund and an equity fund invest in different types of securities. A bond fund primarily invests in debt securities, while an equity fund primarily invests in equity and equity-related instruments.
The main differences are as follows:
| Feature | Bond fund | Equity fund |
|---|---|---|
| Main investments | Bonds and other debt securities | Shares and equity-related securities |
| Main risks | Interest-rate, credit and liquidity risks | Market and equity-related risks |
| Value movement | Affected by interest rates, credit quality and market conditions | Affected by company performance, market conditions and other factors |
| Income | Debt securities may generate interest or coupon income | Equity securities may generate dividends |
| Capital guarantee | No guarantee | No guarantee |
The right choice depends on your investment objective, time horizon and ability to accept risk. One category should not be described as universally better than the other.
Can you invest in bond funds through the Bajaj Broking website?
You can explore mutual fund schemes through the Bajaj Broking website. The platform provides access to 4,000+ mutual fund schemes across different categories, with SIP and lumpsum investment options.
If you are comparing schemes, you can use the mutual fund compare tool to review available information. Do not select a scheme only because it has shown higher historical returns.
You can also learn more about lumpsum and SIP investing methods.
Are bond funds suitable for long-term goals?
A bond fund may be considered when its investment objective, risk profile and duration match your financial goal and investment horizon.
However, there is no single bond fund category that is suitable for every long-term goal. A long-duration fund, for example, can have different interest-rate sensitivity from a short-duration fund.
Before investing, consider the purpose of the investment, the period for which you can remain invested and the level of risk you can accept.
Conclusion
Bond funds offer a convenient way to access the debt market. The various bond fund benefits make them an attractive investment option if you are seeking capital protection and a passive income source. That said, choosing the right mutual fund schemes is crucial to ensure that you meet your financial goals.
When selecting bond funds, remember to evaluate factors such as the current Net Asset Value (NAV), bond yield and total return, among others. You could use the mutual fund compare tool available on the Bajaj Broking website to help you choose the right option. The platform hosts more than 1,000 different mutual fund schemes across different categories with the option for both lump sum and SIP investments.
Discover the smarter way to grow your wealth by investing in mutual funds through the Bajaj Broking website! Enjoy a wide selection of top-performing funds, seamless online transactions, and expert insights to guide your journey. Start today with flexible options tailored to your goals.

Start Exploring
Articles and Insights

Frequently Asked Questions
Overview
What is the meaning of a bond fund and how does it work?
A bond fund is a mutual fund that pools money from investors and invests it in bonds and other debt securities. The fund's NAV changes based on the value and performance of the securities in its portfolio.
Are bond funds risk-free?
No. Bond funds are not risk-free. Their value can be affected by interest-rate movements, credit events, liquidity conditions and other market factors.
Can you lose money in a bond fund?
Yes. The NAV of a bond fund can fall, which means you may receive less than the amount you invested when you redeem your units.
Do bond funds provide fixed returns?
No. Bond fund returns are not fixed or guaranteed. The return depends on the performance and value of the securities held by the fund, as well as other market conditions.
What is the difference between a bond fund and an equity fund?
A bond fund primarily invests in debt securities such as bonds, while an equity fund primarily invests in shares and equity-related instruments. Their risks and return patterns can therefore differ.
What is the difference between a bond and a bond fund?
A bond is an individual debt security issued by an entity such as a government or company. A bond fund pools money from investors and invests in a portfolio of bonds and other debt securities.
What is duration risk in a bond fund?
Duration risk refers to the sensitivity of a bond fund's value to changes in interest rates. A fund with higher duration is generally more sensitive to interest-rate movements than a fund with lower duration.
What is the difference between a bond fund and a gilt fund?
A bond fund is a broad term for a mutual fund that invests mainly in bonds and other debt securities. A gilt fund is a specific debt-fund category that invests predominantly in government securities.
Do bond funds pay monthly income?
Not necessarily. The securities held by a bond fund may generate interest or coupon income, but this does not mean that investors receive a fixed monthly payment. Any distribution depends on the scheme's structure, option and applicable rules.
What is the best time to invest in a bond fund?
There is no single best time that applies to every investor. The decision depends on your investment objective, time horizon, interest-rate exposure, credit risk and the specific scheme's portfolio.
How are bond funds taxed?
The tax treatment depends on the type of mutual fund and applicable tax rules. Certain debt-oriented schemes fall under Section 50AA and are subject to its special rules. Check the scheme's classification and current tax provisions before investing.
What should I check before investing in a bond fund?
Check the scheme's investment objective, Riskometer, portfolio, credit quality, duration, expense ratio, historical performance, liquidity and applicable exit load. Also consider whether the scheme matches your investment horizon and financial goal.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.