








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
Understanding Gilt Mutual Fund
In summary
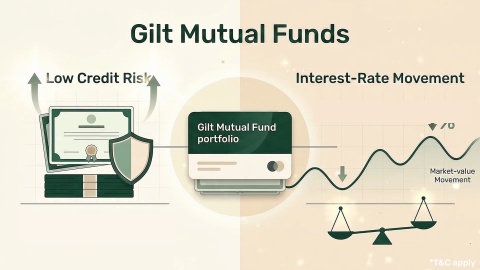
A gilt mutual fund is a debt mutual fund that puts at least 80% of its assets in government securities. The government owes the money, so default risk is low, but the fund's value still moves with interest rates.
- The Securities and Exchange Board of India (SEBI) listed 23 gilt fund schemes as of July 2026.
- When interest rates rise by 1 percentage point, a fund with a 6-year duration loses about 6% of its value.
- You pay tax at your income tax slab rate on gains from units bought on or after 1 April 2023.
You can invest through a systematic investment plan (SIP) or a lumpsum.
Choose a gilt mutual fund when you can hold it for at least as long as its duration. Keep money you need within a year in a savings account or fixed deposit instead.
Last reviewed: September 2026
What are gilt mutual funds?
A gilt mutual fund is a debt mutual fund that invests at least 80% of its assets in government securities of any maturity. Government securities (G-secs) include bonds and treasury bills issued by the central government and bonds issued by state governments.
SEBI set this 80% rule in its October 2017 scheme categorisation circular, and it remains in force as of September 2026. A separate category, the gilt fund with 10-year constant duration, keeps the average duration of its portfolio at 10 years. SEBI's mutual fund statistics list 23 gilt fund schemes and 5 constant-duration gilt schemes as of July 2026. To see where gilt funds sit among other debt funds, read about debt mutual funds.
How do gilt mutual funds work?
A gilt mutual fund pools money from investors and buys government securities, and the value of those securities sets the fund's price. That price is the net asset value (NAV): the value of the portfolio, minus expenses, divided by the number of units. Read more about net asset value.
Three terms explain how the NAV moves:
| Term | What it means for you |
|---|---|
| Coupon | The fixed interest a bond pays each year, stated as a percentage of its face value |
| Yield | The annual return a buyer earns on a bond at today's market price |
| Duration | The sensitivity of a bond's price to a change in yields, stated in years |
When market yields rise, existing bonds with lower coupons lose value, and the NAV falls. When yields fall, those bonds gain value, and the NAV rises. The fund's modified duration tells you the size of the move:
Approximate change in NAV (%) = − Modified duration (years) × Change in yield (percentage points)
This formula gives a close estimate for yield changes of up to about 1 percentage point.
Learn more about government securities.
What are the benefits of gilt mutual funds?
The main benefit of a gilt mutual fund is that you lend to the government, not to a company. SEBI's Potential Risk Class matrix, introduced in June 2021, places this credit risk in Class A, the lowest of its three classes.
- Low default risk. The central or a state government owes the money on at least 80% of the portfolio.
- Gains when rates fall. A fund with a 6-year duration gains about 6% when yields fall by 1 percentage point.
- Redemption on any business day. You can sell units on any business day, subject to the exit load in the scheme documents.
- Small starting amounts. You can start with a monthly SIP instead of buying individual bonds.
These benefits come with interest rate risk. The next section explains each risk that affects your money.
What are the 5 risks of gilt mutual funds?
The main risk of a gilt mutual fund is interest rate risk: when yields rise, the NAV falls. The table sets out all 5 risks.
| Risk | What it means for you |
|---|---|
| Interest rate risk | A fund with a 6-year duration loses about 6% when yields rise by 1 percentage point |
| Duration risk | A fund with a 10-year duration loses about 10% for the same rise |
| Inflation risk | If prices rise faster than your return, your money buys less when you redeem |
| Liquidity risk | In a falling market, the fund can sell bonds only at lower prices, which reduces the NAV |
| Reinvestment risk | When rates fall, the fund reinvests maturing bonds at lower yields |
A gilt mutual fund does not suit money you need on a fixed date within the next 12 months. It also does not suit you if a 6% fall in value would force you to sell. SEBI's Riskometer, set out in its October 2020 circular and shown in the scheme documents, rates each scheme on 6 levels, from Low to Very High.
How do gilt mutual funds compare with fixed deposits?
A gilt mutual fund offers a market-linked return with no fixed maturity, while a fixed deposit (FD) pays a fixed rate for a fixed term. The table compares the two with buying government securities directly.
| Feature | Gilt mutual fund | Fixed deposit | Direct government securities |
|---|---|---|---|
| Return | Changes daily with bond prices | Fixed when you invest | Fixed coupon if held to maturity |
| Value before maturity | Rises or falls with yields | Fixed, minus any early-withdrawal penalty | Rises or falls with yields |
| Access | Any business day, subject to exit load | At maturity, or early with a penalty | Sell in the market, or hold to maturity |
| Tax on gains or interest | Slab rate, for units bought on or after 1 April 2023 | Slab rate on interest | Slab rate on interest; capital gains rules on sale |
If you need a known amount on a known date, an FD matches that need. If you can hold for longer than the fund's duration and want to gain when rates fall, a gilt fund matches that need. You can buy G-secs directly through the Reserve Bank of India (RBI) Retail Direct portal, but you then choose and manage each bond yourself.
How much can a gilt mutual fund gain or lose?
A gilt mutual fund can gain or lose about its modified duration, in percent, for each 1 percentage point move in yields. The worked example below applies the formula from the previous section.
Example: Meera is a salaried professional who takes home Rs. 1,20,000 a month and already keeps 6 months of expenses in a savings account. She invests a Rs. 3,00,000 lumpsum for her daughter's college fees, due in 7 years. She picks a gilt fund with a modified duration of 6 years, which is shorter than her 7-year horizon.
If yields rise by 1 percentage point in the first month after she invests, the NAV changes by about −6 × 1 = −6%. Her Rs. 3,00,000 becomes about Rs. 2,82,000. If yields fall by 1 percentage point instead, her investment becomes about Rs. 3,18,000.
These figures are before expenses, exit load and tax, and they ignore the interest the fund earns each year. They assume a single 1 percentage point change in yields and no other change in the portfolio.
Two practical limits apply. The fund's expense ratio, the annual fee the fund house deducts from the NAV, reduces every return Meera earns. Her 7-year horizon also gives the interest the fund earns time to offset a fall in bond prices, which a 1-year horizon does not.
How are gilt mutual funds taxed?
You pay tax at your income tax slab rate on gains from gilt mutual fund units bought on or after 1 April 2023, however long you hold them. This rule, from Section 50AA of the Income-tax Act, 1961, carries into the Income-tax Act, 2025, in force from 1 April 2026, without a material change. From financial year (FY) 2025-26, it covers any mutual fund that invests more than 65% of its money in debt and money market instruments, which includes every gilt fund.
For units bought before 1 April 2023 and held for more than 24 months, you pay long-term capital gains tax at 12.5% without indexation, under the Finance (No. 2) Act, 2024 (August 2024). If you hold those units for 24 months or less, you pay tax at your slab rate. Confirm the treatment for your units with a tax adviser before you redeem.
How do you invest in gilt mutual funds?
To invest in a gilt mutual fund, you compare schemes on duration, costs and risk, and then invest through an SIP or a lumpsum. An SIP invests a fixed amount each month, while a lumpsum invests the full amount at once.
- Match the duration to your horizon. Pick a fund whose modified duration is shorter than the years until you need the money.
- Check the expense ratio. Compare the annual fee across gilt funds in the scheme documents.
- Check the exit load. The exit load is the fee a fund charges if you redeem within a set period.
- Read the Riskometer and the portfolio. Confirm the share of central and state government securities.
- Invest through an SIP or a lumpsum. Use a mutual fund platform such as the Bajaj Broking website, a distributor or the fund house directly.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
Interest rates and returns
Choosing a fund and a method
What happens to a gilt mutual fund when the RBI cuts the repo rate?
Its NAV rises if bond yields fall after the cut. The repo rate is the rate at which the RBI lends to banks, and it sets the base for yields on government securities. A fund with a 6-year duration gains about 6% for a 1 percentage point fall in yields. If markets expected the cut, yields can already have moved, so you see a smaller change.
Can a gilt mutual fund give a negative return?
Yes. When yields rise faster than the interest the fund earns, the NAV falls, and your return over that period is negative. A fund with a 6-year duration loses about 6% for a 1 percentage point rise in yields. The interest the fund earns each year offsets part of that fall, so your chance of a negative return drops as you hold longer.
What is a gilt fund with 10-year constant duration?
It is a separate SEBI category that invests at least 80% in government securities and keeps its portfolio duration at 10 years. Its NAV moves about 10% for each 1 percentage point change in yields, and the duration does not shrink as its bonds approach maturity. Choose it only if you can hold for at least 10 years and accept larger swings in value.
Should you invest in a gilt mutual fund through an SIP or a lumpsum?
Use an SIP if you invest from monthly income, and a lumpsum if you already hold the full amount. An SIP buys units at different NAVs across interest rate movements, so no single entry date sets your whole cost. A lumpsum puts all your money in at one NAV. Both methods carry the same tax treatment and the same interest rate risk once invested.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.