








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
Alternative Investment Options
In summary
A Unit Investment Trust (UIT) is a pooled investment structure that holds a generally predefined portfolio of securities for a stated period.
- A UIT generally holds a fixed portfolio of securities.
- Investors buy units representing an interest in the portfolio.
- A UIT usually has a stated termination date.
- The value of units can rise or fall with the underlying securities.
- A fixed portfolio does not mean fixed or guaranteed returns.
Costs, redemption terms, and tax treatment vary between UITs.
As of September 2026, Investor.gov identifies UITs as one of three basic types of investment companies in the US, alongside open-end and closed-end funds.
A UIT is different from a standard Indian mutual fund. It is also not the same thing as Unit Trust of India (UTI).
What is a Unit Investment Trust?
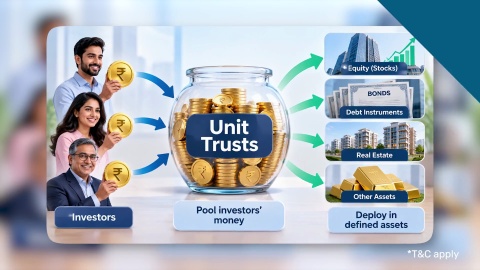
A Unit Investment Trust is an investment structure that pools money from investors and holds a predefined portfolio of securities, such as shares or bonds. Investors buy units that represent an interest in the trust's underlying portfolio.
Unlike an actively managed fund, a UIT generally does not continuously trade securities to change its portfolio. The securities are selected when the trust is created and are generally held with limited changes during its stated term.
The exact structure, fees, redemption arrangements, investment objective, and termination provisions can vary between UITs.
How does a UIT work?
A UIT is created with a stated investment objective and a portfolio of securities.
The basic process is:
- Portfolio creation: Securities are selected according to the trust's investment objective.
- Units are issued: Investors purchase units representing an interest in the trust.
- Portfolio is held: The securities are generally held with little or no active trading during the trust's life.
- Value changes: The value of the units changes as the underlying securities change in value.
- Income may be distributed: Interest, dividends, or other income may be distributed according to the trust's terms.
- Trust terminates: The UIT generally ends on a date specified when it is created, after which the assets may be sold and proceeds distributed according to its terms.
For example, a UIT could be created with a predefined portfolio of 20 shares. If you buy units, you gain an interest in that portfolio rather than purchasing each of the 20 shares separately.
What are the main characteristics of a UIT?
Here are the main characteristics of a UIT:
Predefined portfolio
The securities are generally identified when the UIT is created. This gives investors a clearer idea of what the trust intends to hold.
Limited portfolio changes
A UIT generally does not actively trade its portfolio in response to changing market conditions. This differs from an actively managed fund, where the investment manager can buy and sell securities as part of the fund's strategy.
Defined investment period
A UIT generally has a termination date set when it is created. The trust's documents explain what happens when it reaches that date.
Redeemable units
UIT units can generally be redeemable at approximately their NAV, although some UITs may also have a secondary market. The exact redemption arrangements depend on the specific trust.
Exposure to multiple securities
A single UIT can hold several securities, allowing an investor to gain exposure to a portfolio rather than relying on one security.
What are the benefits and limitations?
Benefits
- Portfolio transparency: Because the portfolio is generally predefined, you can understand what securities the UIT is designed to hold.
- Diversification: A UIT can provide exposure to several securities through one investment.
- Defined investment period: The stated termination date gives the investment a defined structure and timeframe.
- Limited portfolio turnover: Since the portfolio is generally not actively traded, there may be less portfolio turnover than in an actively managed fund.
Rules-based structure: The trust follows its stated investment objective and portfolio structure rather than relying on frequent discretionary changes.
Limitations
- Limited flexibility: The predefined portfolio may not be adjusted quickly when the outlook for a security or sector changes.
- Market risk: If the underlying securities lose value, the value of the UIT can also fall.
- Concentration risk: A UIT focused on a particular sector, theme, or type of security can be affected significantly by events affecting that area.
- Redemption conditions: Selling units before termination may be subject to the specific trust's terms, charges, or other conditions.
- No guaranteed returns: A fixed portfolio does not mean the investment has a fixed return.
What are the risks of a UIT?
The main risk is that the underlying investments can lose value. The level of risk therefore depends on what the UIT holds.
For example, a UIT holding equities can experience significant price fluctuations. A UIT holding bonds can be affected by interest rates, credit quality, and other fixed-income risks.
You should also consider:
- Market risk: The value of the underlying securities can decline.
- Concentration risk: A narrowly focused portfolio may be affected more by a particular sector or issuer.
- Liquidity risk: The ease and cost of selling units depend on the specific UIT and its redemption or secondary-market arrangements.
- Interest-rate risk: Bond-focused UITs can be affected by changes in interest rates.
- Credit risk: A bond issuer may fail to make required payments.
- Termination risk: The trust ends according to its stated terms, which may require you to reinvest or receive the proceeds at that time.
Investor.gov also advises investors to review the UIT's prospectus and understand its risks, fees, and expenses before investing.
What does a UIT cost?
Costs vary by UIT. They can include an initial sales charge, deferred sales charge, operating expenses, transaction costs, and trustee or administrative fees.
Some UITs may also involve costs when units are redeemed or when investors roll their proceeds into another trust.
Do not assume that a predefined portfolio means low costs. Check the specific offering documents for all applicable charges before investing.
How is a UIT different from a mutual fund?
Both structures pool money from investors and provide exposure to a portfolio of securities, but their structures can differ.
| Factor | Unit Investment Trust | Mutual fund |
|---|---|---|
| Portfolio | Generally predefined | Can be actively managed or follow a predefined strategy |
| Portfolio changes | Generally limited | Depends on the fund's strategy |
| Term | Generally has a stated termination date | Depends on the fund structure |
| Management | Generally no active portfolio trading | May be actively or passively managed |
| Units/shares | Units represent an interest in the trust | Investors hold units or shares in the fund |
Last updated: September 2026
A mutual fund is therefore not always actively managed. Index funds, for example, follow a defined investment strategy.
You can learn more about what is an active fund and what are index funds.
How are UITs taxed?
Tax treatment depends on the jurisdiction, structure of the UIT, type of income or gains, and applicable tax rules.
A UIT investor may receive income such as dividends or interest and may also realise a capital gain or loss when units are sold. The applicable tax treatment cannot be stated as one universal rate.
If you are considering a UIT outside India, check the tax rules that apply to your residence, the country where the investment is held, and the specific product documentation.
What should you check before investing in a UIT?
Before investing, read the UIT's prospectus and check the details that determine how the investment will work.
- Underlying securities: Understand what the trust holds.
- Investment objective: Check what the UIT is designed to achieve.
- Termination date: Know when the trust is scheduled to end.
- Redemption rules: Check whether and how you can sell units before termination.
- Fees: Review sales charges, operating expenses, and other applicable costs.
- Risk: Assess the risks of the underlying securities.
- Distributions: Understand how dividends, interest, or other income will be handled.
- Tax treatment: Check the rules that apply to your circumstances.
Conclusion
A Unit Investment Trust is a pooled investment structure built around a generally predefined portfolio and a stated termination date. This can make its holdings and investment period easier to understand, but it also limits the flexibility to change the portfolio.
A UIT is not the same as an Indian mutual fund, and it should not be confused with Unit Trust of India. Before considering one, review its underlying securities, risks, fees, redemption terms, termination date, and applicable tax rules.
Last reviewed: September 2026
Mutual funds are subject to market risk. Please read the scheme-related documents carefully before investing.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
Overview
Is a UIT a mutual fund?
No, a Unit Investment Trust (UIT) is not a mutual fund. UITs have a fixed portfolio of securities and a defined expiration date, unlike mutual funds that continuously issue and redeem shares and have actively managed or index-tracking portfolios.
Who can sell UIT?
UITs can be sold by financial advisors, brokers, and financial institutions that are licensed to sell securities.
Is unit trust a good investment?
Unit Investment Trusts (UITs) can be a good investment for those seeking a fixed portfolio with predictable returns and lower management fees. However, they may not be ideal for those who prefer active management or need flexibility in their investment choices.
What are the benefits of a UIT?
Key benefits of a Unit Investment Trust (UIT) can include a predetermined portfolio, transparent holdings, limited portfolio turnover and a defined investment horizon. However, the benefits vary by UIT, and investors should consider the underlying securities, fees, risks, redemption terms and termination date before investing.
What type of investment is a UIT?
A Unit Investment Trust (UIT) is a pooled investment vehicle that allows investors to own units representing an interest in a portfolio of securities. The portfolio is generally predetermined and held for a defined period, with the underlying assets determining the investment’s risk and return.
How are UITs taxed?
UITs are taxed on the income they generate, such as interest and dividends, which is passed to investors. These earnings are taxed as ordinary income. Capital gains from selling UIT units are also taxed based on whether they are short-term or long-term.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.