








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
In summary
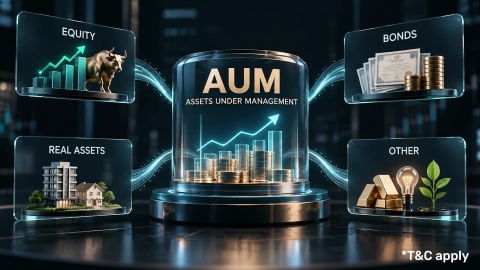
Assets under management
Assets Under Management, or AUM, tells you the total value of assets managed by a mutual fund scheme at a particular point in time. It can increase or decrease as investors add or withdraw money and as the market value of the scheme's investments changes. AUM is useful for understanding the size of a mutual fund, but it does not tell you whether the fund will deliver better returns.
The key points to remember are:
- AUM stands for Assets Under Management.
- It represents the total value of assets managed by a mutual fund scheme.
- AUM can change because of fresh investments, redemptions and market movements.
- A simple illustration of AUM can use NAV multiplied by the number of outstanding units.
- AUM and NAV are different. AUM refers to the total value of assets, while NAV is the value per unit.
- A higher AUM does not automatically mean that a mutual fund is better or will provide higher returns.
You should consider AUM along with factors such as the fund's objective, risk level, costs and investment strategy.
Understanding AUM can help you read mutual fund information and compare schemes more confidently.
What is Assets Under Management (AUM)?
Assets Under Management (AUM) is the total market value of the investments managed by a financial entity, fund or individual on behalf of clients. For a mutual fund, this includes the value of the assets held by the scheme.
These assets can include shares, bonds, government securities, cash and money market instruments, depending on the scheme's investment objective.
For example, if a mutual fund manages assets worth Rs. 500 crore, its AUM is Rs. 500 crore at that point in time. The figure can change as investors invest or redeem units and as the value of the investments changes.
You can learn more about mutual funds to understand how these investment products work.
AUM is also used in other areas of financial services, such as hedge funds and wealth management. However, the way AUM is calculated and reported can vary depending on the type of financial entity.
Why is AUM important?
AUM helps you understand the size of a mutual fund scheme or investment entity. It can also help you understand how the size of a scheme changes over time.
However, AUM should not be treated as a direct measure of fund performance, safety or future returns.
For example, a scheme with AUM of Rs. 10,000 crore is larger than a scheme with AUM of Rs. 1,000 crore. This tells you about the size of the two schemes, but it does not tell you which one will perform better.
You can use AUM as one factor while studying a mutual fund, along with its investment objective, risk level, portfolio, costs and performance.
How to calculate Assets Under Management?
AUM represents the value of the assets managed by a fund. The value can change when investors buy or redeem units and when the market value of the securities held by the scheme changes.
For a simple mutual fund illustration, you can understand the relationship between AUM and Net Asset Value using the following example.
H3: A simple AUM calculation
Suppose a mutual fund has a NAV of Rs. 20 and 20,000 outstanding units.
For this simple illustration:
AUM = NAV × Total number of outstanding units
= Rs. 20 × 20,000
= Rs. 4,00,000
This gives an asset value of Rs. 4,00,000 for the units in the example.
In practice, a mutual fund scheme's assets and liabilities are valued according to the applicable rules. The reported AUM can therefore change with market movements and investor transactions.
Why does AUM change?
AUM is not a fixed number. It can change even when the number of investors remains the same.
The main reasons include:
- Fresh investments: When investors add money to a scheme, its assets can increase.
- Redemptions: When investors withdraw money by redeeming units, the scheme's assets can decrease.
- Rise in asset values: If the market value of the securities held by the scheme increases, AUM can rise.
- Fall in asset values: If the market value of the securities decreases, AUM can fall.
For example, a scheme may have AUM of Rs. 4 crore. If investors add Rs. 50 lakh, its AUM can increase to Rs. 4.5 crore, assuming there are no other changes. A subsequent rise or fall in the value of its investments can change the figure further.
AUM and expense ratio
AUM and the expense ratio are related, but a higher AUM does not automatically mean a lower actual expense ratio.
The expense ratio is the cost charged by a mutual fund for managing and operating the scheme. It is expressed as a percentage of the fund's assets.
SEBI prescribes limits for the Total Expense Ratio based on applicable asset-size slabs and the type of scheme.
This means the relationship between AUM and permissible expenses is regulated. However, you should not assume that:
Higher AUM = lower actual expense ratio
When comparing mutual funds, check the actual expense ratio of each scheme along with other relevant factors.
Does high AUM mean a better mutual fund?
No. A high AUM does not automatically mean that a mutual fund is better or will deliver higher returns.
A high AUM mainly tells you that the scheme manages a larger pool of assets. It may also mean that many investors have invested in the scheme, but this alone does not tell you why they invested or whether the scheme is suitable for you.
Similarly, a smaller AUM does not automatically mean that a fund is poorly managed.
When comparing funds, consider factors such as:
- The fund's investment objective
- Its portfolio
- Its risk level
- Its expense ratio
- Its performance over relevant periods
Its investment strategy
Your choice should also match your financial goals and risk appetite.
AUM vs NAV: what is the difference?
AUM and NAV are related but have different meanings.
AUM refers to the total value of assets managed by a mutual fund scheme. NAV, or Net Asset Value, refers to the value of one unit of the scheme after accounting for the scheme's assets and liabilities.
The basic difference is shown below:
| Term | Meaning |
|---|---|
| AUM | Total value of assets managed by a mutual fund scheme |
| NAV | Value of one unit of the mutual fund scheme |
For example, a scheme may have AUM of Rs. 100 crore while its NAV is Rs. 25 per unit. These figures measure different things.
NAV can change when the value of the securities held by the scheme changes. AUM can also change because of investor inflows and redemptions.
Does AUM affect how a mutual fund is managed?
AUM tells you the size of the assets being managed. It does not tell you how well those assets are managed.
A fund manager manages the scheme according to its investment objective and strategy.
The size of a scheme can matter in some situations. For example, a very large scheme may need to consider the availability and liquidity of securities when making large transactions. The effect depends on the scheme and the assets in its portfolio.
A smaller AUM does not automatically mean poor management. Similarly, a larger AUM does not guarantee better performance.
How should you use AUM when comparing mutual funds?
AUM can help you understand the size of a mutual fund scheme. It can be one of the factors you consider when comparing funds, but it should not be the only one.
Suppose you are comparing two equity mutual funds. One has AUM of Rs. 10,000 crore and another has AUM of Rs. 1,000 crore. The first scheme is larger in terms of assets managed, but this information alone does not tell you which fund is more suitable.
You should also consider the funds' objectives, risk levels, portfolios, costs and relevant performance information.
AUM as a measure of fund size
AUM is often used to describe the size of a mutual fund scheme or financial institution.
A larger AUM means a larger value of assets is being managed. However, size should not be confused with performance.
A fund can have a large AUM and still deliver lower returns than another fund. Similarly, a smaller fund can perform well.
Therefore, AUM is best understood as a size-related measure, rather than a score for judging a fund.
AUM and investment management strategy
AUM can be relevant when understanding how a fund manages its assets, but it is not a measure of the quality of the investment strategy.
For example, the size of a scheme can affect how it manages large transactions, particularly when it invests in securities with lower liquidity.
However, a large AUM does not automatically mean that a fund has better research, more experienced managers or better investment decisions.
You should assess the fund based on its investment objective, strategy, portfolio, costs and other relevant information.
AUM across different types of financial entities
AUM is used in several areas of financial services. These include mutual funds, hedge funds, wealth management and private equity.
The meaning and calculation can differ depending on the type of financial entity.
For a mutual fund, AUM generally refers to the value of the assets managed by the scheme. In other financial businesses, AUM may be based on different assets, valuation methods or reporting practices.
For this reason, always consider the context when you see an AUM figure.
What are the limitations of AUM?
AUM is useful for understanding fund size, but it has limitations.
The main limitations are:
- AUM does not predict future returns.
- AUM does not tell you whether a fund suits your financial goals.
- AUM can rise because of market movements even when investors have not added new money.
- AUM can fall because of market declines even when investors have not redeemed their units.
- A high AUM does not guarantee lower risk.
A low AUM does not automatically indicate poor fund management.
Therefore, AUM should be treated as one piece of information rather than a measure of fund quality.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
Understanding AUM
Can AUM fall even when investors do not withdraw money?
Yes. AUM can fall when the market value of the securities held by a mutual fund decreases. For example, if a scheme owns shares and their market prices decline, the value of the scheme's assets can fall even if no investor redeems units. AUM can therefore change because of both investor transactions and market movements.
Does AUM include the value of securities held by a mutual fund?
Yes. A mutual fund's AUM reflects the value of the assets managed by the scheme. Depending on the scheme, these assets can include equities, bonds, government securities and money market instruments. The value of these investments can change with market conditions, which can cause the scheme's AUM to rise or fall.
Is AUM the same for every mutual fund scheme?
No. Each mutual fund scheme has its own AUM based on the value of the assets it manages. Two schemes can have very different AUM figures even if they belong to the same category. AUM can also change over time because of investor transactions and changes in the market value of the investments.
Should you choose a mutual fund based on AUM?
No. AUM should not be the only factor you use when selecting a mutual fund. It tells you about the size of the scheme but does not predict future returns or tell you whether the fund suits your goals. You should also consider the fund's objective, risk level, portfolio, costs and relevant performance information.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.