








Return on Investment (ROI)
-
In summary
Return on Investment (ROI) is a financial metric that measures the profit or loss generated by an investment relative to its cost. Expressed as a percentage, ROI helps individuals understand investment performance and compare different financial opportunities.
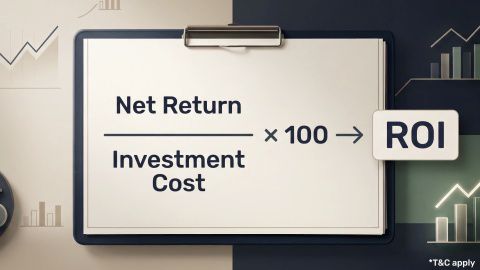
- ROI formula: Divide the net profit or loss by the total investment cost and multiply by 100.
- Purpose: ROI helps evaluate investment performance, compare alternatives and assess whether an investment has met its financial objectives.
- Calculation: An investment of Rs. 10,000 that grows to Rs. 12,000 generates a 20% ROI, before considering any additional charges or taxes.
- Applications: ROI can be used to evaluate shares, mutual funds, fixed deposits, real estate and business expenditure.
- Limitations: ROI does not independently account for investment duration, risk, inflation, compounding or the timing of cash flows.
What is Return on Investment (ROI)?
Avoid these mistakes while booking FD
-
Return on Investment (ROI) is a financial measure used to calculate the profit or loss earned from an investment in relation to the amount invested. The ROI full form is Return on Investment. It is generally expressed as a percentage, making it easier to compare the financial outcomes of different investments.
For example, if an individual invests Rs. 20,000 in an asset and its value increases to Rs. 24,000, the investment generates a profit of Rs. 4,000. The ROI is 20%, excluding additional costs and taxes.
ROI is used by individuals, businesses and organisations to evaluate financial performance. For individual investors, it can help assess how an investment has performed over a particular period. Businesses may use it to evaluate expenditure on marketing, equipment, technology or other projects.
A positive ROI indicates a gain relative to the initial investment cost, while a negative ROI indicates a loss. An ROI of zero means that the investment has neither generated a net gain nor incurred a net loss after accounting for the costs included in the calculation.
How to calculate Return on Investment (ROI)?
-
ROI is calculated by dividing the net profit or loss from an investment by its total investment cost and multiplying the result by 100.
What is the ROI formula?
The standard formula for calculating ROI is:
ROI = (Net profit or loss ÷ Total investment cost) × 100
Net profit or loss is calculated as:
Net profit or loss = Total value received − Total investment cost
The total value received may include the amount realised from selling an investment and any income earned from it, such as dividends or interest, provided these amounts are not counted twice. Relevant expenses should also be included when calculating the overall investment cost or deducting costs from the returns.
How is ROI calculated with an example?
Consider an individual who invests Rs. 10,000 in shares and later sells them for Rs. 12,000. For simplicity, assume there are no dividends, brokerage charges, taxes or other expenses.
The calculation is as follows:
Particulars Amount Initial investment Rs. 10,000 Final sale value Rs. 12,000 Net profit Rs. 2,000 ROI 20% Using the formula:
ROI = (Rs. 2,000 ÷ Rs. 10,000) × 100
ROI = 20%
This means the investment generated a profit of Rs. 20 for every Rs. 100 invested over the holding period. It does not mean the investment earned 20% every year.
If the investment had instead been sold for Rs. 9,000, the loss would have been Rs. 1,000, resulting in an ROI of -10%.
Why is ROI important in investment?
ROI helps investors understand the financial outcome of an investment relative to the amount committed. It provides a simple way to assess performance, although it should not be used as the sole basis for an investment decision.
The following are some key uses of ROI.
How does ROI help measure investment performance?
ROI indicates the percentage gain or loss relative to the investment cost. Tracking this measure over a specified period can help investors understand whether an investment has performed in line with their expectations.
For example, an investment with a positive ROI has generated a gain over the period being assessed, whereas a negative ROI indicates a loss. The result should be interpreted alongside the investment's duration and associated costs.
How does ROI help compare investments?
ROI provides a common percentage-based measure for comparing investments of different sizes. For instance, a Rs. 10,000 investment generating a profit of Rs. 2,000 and a Rs. 50,000 investment generating a profit of Rs. 10,000 both produce an ROI of 20%.
However, the comparison is meaningful only when the measurement periods and the costs included in the calculations are understood. Two investments with the same ROI may differ considerably in terms of risk, liquidity and the time required to generate the return.
How does ROI support financial planning?
ROI can help individuals assess whether their investments are contributing towards financial goals, such as education expenses, a home purchase or retirement.
Estimating possible returns may help with financial planning, but actual outcomes can differ from estimates. Market-linked investments do not provide predictable returns, while fixed-return products remain subject to their terms, applicable taxes and the issuer's ability to meet its obligations.
Does ROI measure investment risk?
ROI alone does not measure risk. A higher return may be associated with greater uncertainty or a higher possibility of loss, while an investment with a lower return may have different liquidity or capital-preservation characteristics.
Investors can evaluate ROI alongside factors such as volatility, credit risk, liquidity, investment duration and the possibility of losing the amount invested.
How is ROI calculated for different investment options?
The method of calculating ROI depends on the type of investment, the income it generates and the costs associated with it. The following examples explain how ROI can be applied to common investment categories.
How is ROI calculated for a fixed deposit?
A fixed deposit (FD) is a deposit in which money is placed with a bank or eligible financial institution for a specified tenure at an agreed interest rate. The applicable terms determine how interest is calculated and paid.
For a basic ROI calculation, the total interest received is compared with the amount deposited.
ROI = (Net interest earned ÷ Initial deposit) × 100
For example, suppose an individual deposits Rs. 1,00,000 in an FD and receives total interest of Rs. 21,000 over the selected tenure. If the principal is repaid in full and no additional costs are considered, the ROI based on interest earned is 21%.
This is the total return over the entire tenure, not an annual return of 21%. The annualised return depends on the duration of the deposit, the interest calculation method and the payout structure.
For an accurate estimate, the applicable interest rate, tenure, compounding frequency, payout option and tax treatment should be considered. Actual proceeds may differ depending on the product's terms and any premature withdrawal conditions.
How is ROI calculated for mutual funds?
Mutual funds pool money from multiple investors and invest it in assets such as shares, bonds or money market instruments, depending on the scheme's investment objective.
The value of a mutual fund investment changes with its Net Asset Value (NAV), which represents the per-unit value of the scheme's assets after accounting for its liabilities. Returns may also include distributions received by the investor.
A simplified ROI formula for a mutual fund is:
ROI = (Net gain or loss ÷ Initial investment) × 100
For example, suppose an individual invests Rs. 10,000 in a mutual fund. The value of the investment later increases to Rs. 12,000, and no distributions or additional expenses are assumed.
ROI = (Rs. 12,000 − Rs. 10,000) ÷ Rs. 10,000 × 100
ROI = 20%
This calculation represents the total return over the holding period. If the investment generated distributions, those should also be included when calculating the overall return. Applicable charges and taxes may reduce the net amount received.
Mutual fund returns are market-linked and may be positive or negative. Past performance does not guarantee future results.
How is ROI calculated for shares?
Shares represent ownership in a company. An investment in shares may generate returns through an increase in share price and dividends, if declared by the company.
The total ROI can be calculated by considering both capital gains or losses and dividends received, after accounting for relevant expenses.
For example, an individual purchases shares for Rs. 20,000 and later sells them for Rs. 24,000. During the holding period, the individual also receives dividends of Rs. 500. Assuming no other expenses or taxes:
- Initial investment: Rs. 20,000
- Sale proceeds: Rs. 24,000
- Dividends received: Rs. 500
- Total gain: Rs. 4,500
ROI = (Rs. 4,500 ÷ Rs. 20,000) × 100
ROI = 22.5%
This is the total ROI over the holding period. Share prices fluctuate with market conditions and company performance, and dividends are not assured.
How is ROI calculated for real estate?
Real estate ROI measures the financial return generated by a property relative to its total cost. The calculation may include rental income and any gain or loss realised when the property is sold.
For a more accurate estimate, costs such as registration charges, stamp duty, maintenance, repairs, property taxes, brokerage and applicable financing expenses should be considered.
For example, suppose a property costs Rs. 20,00,000 and is later sold for Rs. 23,00,000. The owner also receives Rs. 1,00,000 in net rental income after relevant operating expenses. If no other costs are assumed, the total gain is Rs. 4,00,000.
ROI = (Rs. 4,00,000 ÷ Rs. 20,00,000) × 100
ROI = 20%
This represents the total return over the holding period under the stated assumptions. It is not an annualised return. The actual ROI may be lower after including acquisition expenses, financing costs, taxes and other applicable charges.
Check out different FD Rates
What are the limitations of ROI?
ROI is useful for measuring profitability, but it does not provide a complete picture of an investment's performance. The following limitations are important when interpreting the result.
Does ROI account for the investment period?
No. The basic ROI formula measures the total gain or loss relative to the initial cost but does not account for how long the investment was held.
For example, a 20% ROI earned over two years is different from a 20% ROI earned over five years. Comparing these investments using only total ROI may therefore be misleading.
Annualised return or Compound Annual Growth Rate (CAGR) can help compare returns over different periods when their underlying assumptions are appropriate.
Does ROI account for compounding?
The basic ROI formula does not separately show the effect of compounding. Compounding occurs when accumulated interest or returns generate additional returns over time.
For investments where earnings are reinvested, the total return may reflect compounding, but the simple ROI figure does not explain how that return accumulated. CAGR or other time-adjusted measures may provide additional information.
Does ROI account for risk?
No. ROI measures the financial outcome but does not indicate how much risk was taken to achieve it. Two investments may report the same ROI while differing in volatility, credit quality, liquidity and potential losses.
The level and nature of risk should therefore be assessed separately.
Does ROI include taxes and additional costs?
ROI can be misleading if expenses are excluded from the calculation. Depending on the investment, relevant costs may include brokerage, transaction charges, fund expenses, property maintenance, stamp duty, financing costs and taxes.
A calculation based on gross returns may differ from the net ROI received after these expenses. The costs included in the calculation should be clearly defined before comparing investment outcomes.
Does ROI account for inflation?
No. The basic ROI formula does not adjust for changes in purchasing power caused by inflation.
For example, an investment may generate a positive nominal return, but the increase in the cost of goods and services can reduce the actual improvement in purchasing power. Considering inflation-adjusted returns can provide a more complete understanding of an investment's outcome.
Does ROI account for the timing of cash flows?
The basic ROI formula does not consider when money is invested or when returns are received. This can limit comparisons between investments involving multiple deposits, withdrawals or income payments.
Measures such as the Internal Rate of Return (IRR) may be more appropriate when the timing and amount of cash flows need to be considered.
What is a good ROI for an investment?
There is no single ROI percentage that is considered good for every investment. An appropriate return depends on the investment category, holding period, financial objective, prevailing economic conditions and level of risk.
For example, an investor evaluating a fixed deposit may focus on the applicable interest rate, tenure and reliability of payments. Someone evaluating shares or mutual funds may also consider market volatility, potential capital losses and long-term performance.
A higher ROI does not automatically make one investment more suitable than another. A fair comparison should account for the period over which returns were earned, costs, taxes, liquidity and the possibility of loss.
ROI should also be assessed against a relevant benchmark. Comparing the return from an investment with a suitable market index or an alternative with a similar risk profile may provide more context than examining the percentage in isolation.
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
How can ROI be improved?
ROI can be influenced by the returns generated and the costs incurred. The following practices may help individuals evaluate and manage their investments more effectively.
- Review investment costs: Account for applicable charges, taxes and other expenses to understand the net return.
- Set clear financial goals: Define the purpose and time horizon of an investment before evaluating its performance.
- Diversify investments: Spreading investments across suitable asset categories can help manage concentration risk, although diversification does not eliminate the possibility of losses.
- Review performance periodically: Compare actual returns with relevant benchmarks and financial objectives over an appropriate period.
- Understand risk and liquidity: Evaluate the possibility of losses and whether the money can be accessed when required.
- Use appropriate return measures: Consider annualised returns, CAGR or IRR when a simple ROI calculation does not adequately represent the investment's performance.
These practices do not guarantee higher returns. Their purpose is to support a more informed assessment of investment performance and associated risks.
Conclusion
Return on Investment is a simple financial metric that helps measure the profit or loss generated relative to the amount invested. It can be used to evaluate shares, mutual funds, fixed deposits, real estate and business expenditure.
However, ROI is only one part of investment evaluation. The holding period, costs, taxes, inflation, risk and timing of cash flows can all affect the actual financial outcome. Comparing investments using consistent assumptions and suitable return measures provides a more meaningful understanding of their performance.
Understanding these factors can help individuals assess investment outcomes in the context of their financial goals and risk tolerance.
Locate to your nearest FD branch

Related Articles
Frequently Asked Questions
Overview
Is 7% a good ROI?
A 7% ROI may suit a stable, lower-risk investment, but its suitability depends on duration, inflation, taxation, and financial objectives.
Which investment has the highest rate of return?
No investment consistently offers the highest return. Investments with greater return potential generally involve higher volatility, uncertainty, or capital-loss risk.
Is ROI in FDs better than in mutual funds?
FDs provide assured returns, while mutual fund returns are market-linked. The better choice depends on risk tolerance, goals, and investment duration.
What does a 20% ROI mean?
A 20% ROI means the investment generated a profit equal to 20% of its original cost during the measured period.
Who is responsible for maximizing the return on investment (ROI)?
Individual investors remain responsible for their investment decisions, while business managers oversee ROI on organisational projects and allocated company capital.
How to maximize return on investment?
FD interest rate is the annual percentage return offered by the bank, and it determines the interest earned on the principal amount over the investment tenure.
What is a good return on investment ROI?
A good ROI varies by investment type and risk level, but many investors generally consider returns around 10% or higher as favourable over time.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.