








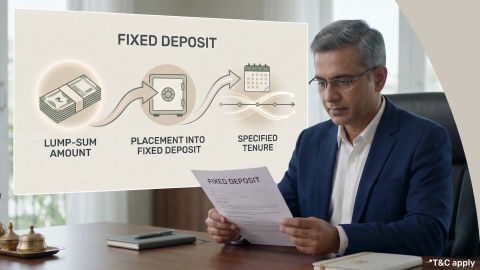
Difference Between Fixed Deposit and Recurring Deposit
-
In summary
A 5-year Recurring Deposit (RD) allows you to deposit a fixed amount regularly for five years and earn interest at the rate applicable to the RD when it is opened. The Post Office 5-year RD currently carries a 6.70% annual interest rate, while bank RD rates vary by institution and customer category. Post Office small-savings rates are notified by the Government, whereas banks can revise their deposit rates periodically.
- Post Office 5-year RD: 6.70% p.a. under the current notified small-savings rate.
- Bank RD rates: Vary across banks, tenure and customer category. For example, Axis Bank's published 60-month RD rate is 7.00% for general customers and 7.75% for senior citizens in its cited rate schedule.
- Monthly deposits: Unlike an FD, the full investment is not made on day one. Each RD instalment earns interest for a different period.
- Tax: RD interest is taxable as income under the applicable income-tax provisions. A 5-year RD should not be treated as automatically eligible for a tax deduction merely because it has a five-year tenure.
- Maturity: The final amount depends on the monthly instalment, applicable interest rate, deposit dates and the institution's prescribed RD calculation method.
- Rates can change: Bank rates are subject to revision, while Post Office small-savings rates are reviewed and notified periodically.
What is a 5-year Recurring Deposit?
How Is Fixed Deposit Interest Calculated
-
A 5-year Recurring Deposit is a savings product in which you deposit a predetermined amount at regular intervals, generally every month, for 60 months.
The institution pays interest on the deposits according to its RD rules, and the accumulated principal and interest are paid at maturity.
An RD can therefore be useful for someone who wants to build a corpus gradually rather than deposit a large lump sum at the beginning.
How does a 5-year RD work?
The basic process is:
- Choose the bank or Post Office.
- Select the monthly instalment.
- Open the RD for the applicable five-year tenure.
- Deposit the instalment on the prescribed due date each month.
- Earn interest according to the applicable RD rate.
- Receive the maturity amount after completing the tenure.
The exact interest-crediting and maturity calculation method varies between institutions.
What are the current 5-year RD interest rates?
-
The Post Office's 5-year National Savings Recurring Deposit currently carries an interest rate of 6.70% p.a. The rate is government-notified and can change when the Ministry of Finance revises small-savings rates.
Bank rates are institution-specific. They can also differ for regular customers and senior citizens.
For example, an Axis Bank published RD schedule shows the following 60-month rates:
Institution 5-year/general rate Senior-citizen rate Rate basis Post Office RD 6.70% 6.70% Government-notified rate Axis Bank 7.00% 7.75% Bank-specific rate schedule HDFC Bank Rate varies Rate varies Check current bank schedule ICICI Bank Rate varies Rate varies Check current bank schedule SBI Rate varies Rate varies Check current bank schedule PNB Rate varies Rate varies Check current bank schedule Kotak Mahindra Bank 6.25% 6.75% Current published schedule Axis Bank's published schedule specifies 7.00% for a 60-month RD for general customers and 7.75% for senior citizens. Kotak Mahindra Bank's schedule effective 10 June 2026 lists 6.25% for 5–10-year RDs, with a 0.50 percentage-point senior-citizen premium for eligible customers.
Important: Bank rates can change without notice. Therefore, the rate shown on a bank's official website when the RD is opened should be used for an actual return calculation.
-
Eligibility & Documents for opening an RD
Eligibility and documentation requirements depend on the bank or Post Office offering the account.
RD accounts are generally available to:
- Resident Indian adults
- Adults opening joint accounts
- Minors represented by guardians
- Eligible minors opening accounts independently
- Senior citizens
NRIs using eligible NRE or NRO accounts
Banks may require the following documents:
- PAN
- Aadhaar or another accepted identity document
- Address proof
- Passport-size photograph for branch applications
- Bank account details for automated deposits
- Age proof when claiming senior citizen rates
PAN requirements depend on applicable tax rules, transaction values, and the institution’s KYC policy. Existing customers may not need to resubmit documents when their KYC details remain complete and updated. Bajaj Finance Fixed Deposit requires PAN and an accepted KYC document. Investments begin from Rs. 15,000.
Quick Tip: You’ll need the same documents for starting a Fixed Deposit! Bajaj Finance provides interest of up to 7.75% p.a. on FDs, click here and open an FD now!
-
How is the interest under the recurring deposit scheme calculated?
Each monthly instalment earns interest for a different period. Earlier instalments therefore earn more interest than later instalments.
For quarterly compounding, the approximate maturity formula is:
M = R × [((1 + i)ⁿ − 1) ÷ (1 − (1 + i)⁻¹/³)]
Where:
- M represents the maturity amount.
- R represents the monthly instalment.
- n represents the number of quarters.
- i represents the annual interest rate divided by 400.
For example, consider Rs. 1,000 deposited monthly for five years at 6.70% p.a.
Here, R equals Rs. 1,000, n equals 20, and i equals 6.70 divided by 400.
The estimated maturity amount is approximately Rs. 71,366.
Actual maturity may differ slightly because of deposit dates, institutional calculations, and rounding.
-
Taxation on RD: What you need to know
RD interest is taxable under “Income from Other Sources”. It is added to your taxable income and taxed accordingly.
For Tax Year 2026–27, banks, cooperative banks, and post offices generally apply these annual TDS thresholds:
Depositor category Annual interest threshold Customers below 60 Rs. 50,000 Resident senior citizens Rs. 1 lakh TDS is generally deducted at 10% when the interest exceeds the applicable threshold and a valid PAN is available. A higher TDS rate may apply when PAN is unavailable or inoperative. From 1 April 2026, Form 121 replaces Forms 15G and 15H under the revised income-tax framework. Eligible resident depositors may submit Form 121 when their estimated tax liability for the year is nil.
TDS is not the final tax liability. You must report the complete RD interest while filing your income tax return. You may claim eligible TDS credit through your return.
Learn more about TDS before estimating your post-tax RD returns.
-
Can you break an RD mid-way?
Post Office RD accounts cannot normally be closed during their first three years. Premature closure becomes available after three years, subject to the scheme’s conditions.
The Post Office Savings Account rate applies instead of the original RD rate after premature closure. Therefore, early closure can reduce the expected return. Banks follow their own premature closure rules. These may include minimum holding periods, reduced interest, or penalties. A loan against the Post Office RD may provide liquidity without immediately closing the account.
Planning for short-term needs? Consider a 1-year Bajaj Finance FD instead of locking into a 5-year RD. Check FD rates.
Also read: Can we break an RD before maturity?
-
RD vs FD: Which is better for you?
An RD uses monthly deposits, while a Fixed Deposit generally requires one lump-sum investment.
Feature Post Office RD Bajaj Finance Fixed Deposit Deposit method Fixed monthly instalments One-time lump sum Minimum amount Rs. 100 monthly Rs. 15,000 Tenure Five years 12 to 60 months Current maximum rate 6.70% p.a. 7.40% p.a. below age 60 Senior citizen rate No separate rate Up to 7.75% p.a. Interest option Compounded quarterly Cumulative or periodic payouts Premature withdrawal After three years Available under specified conditions Suitable for Monthly saving Investing an available lump sum Bajaj Finance Fixed Deposit rates are effective from 1 May 2026 and may change subsequently.
A five-year RD supports regular saving and offers predictable returns without market-linked fluctuations. The Post Office RD currently earns 6.70% p.a., compounded quarterly, for accounts opened during the applicable quarter. Choose it when monthly contributions match your income and five years suits your financial goal. Consider Bajaj Finance Fixed Deposit when you have a lump sum and prefer tenures between 12 and 60 months. Compare liquidity, taxation, rates, and investment timing before deciding.
Calculate your expected investment returns with the help of our investment calculators
Investment Calculator FD Interest calculator Provident Fund Calculator PPF Calculator Recurring Deposit Calculator Gratuity Calculator Sukanya Samriddhi Yojana Calculator
How is interest calculated on a 5-year RD?
An RD differs from a fixed deposit because the entire principal is not invested at the beginning.
Consider a monthly deposit of Rs. 5,000:
- The first Rs. 5,000 instalment remains invested for most of the five-year period.
- A deposit made halfway through the tenure earns interest for a shorter period.
- The final Rs. 5,000 instalment earns interest for only a limited period before maturity.
This is why an RD and an FD offering the same annual interest rate do not produce the same maturity amount when the total amount deposited over five years is compared.
Does every instalment earn interest for five years?
No.
Each instalment has a different investment period. The first instalment has the longest period, while the final instalment has the shortest.
This is one of the most important differences between an RD and a lump-sum FD.
How much does a 5-year RD return?
The maturity amount depends on the institution's calculation method and the applicable rate.
For illustration, assume a monthly instalment of Rs. 5,000 for 60 months:
Total amount deposited = Rs. 5,000 × 60 = Rs. 3,00,000
The maturity value will be higher than Rs. 3,00,000 because the deposits earn interest. However, the exact maturity amount should be obtained from the institution's RD calculator or maturity-value table rather than applying a lump-sum FD formula to the entire Rs. 3,00,000.
Illustrative investment amounts
| Monthly instalment | Total deposits over 5 years |
|---|---|
| Rs. 1,000 | Rs. 60,000 |
| Rs. 2,500 | Rs. 1,50,000 |
| Rs. 5,000 | Rs. 3,00,000 |
| Rs. 10,000 | Rs. 6,00,000 |
| Rs. 25,000 | Rs. 15,00,000 |
The actual maturity value will depend on the applicable RD rate and the institution's calculation methodology.
Can you use an RD calculator to estimate maturity?
Yes. An RD calculator can estimate the maturity value using:
- Monthly instalment
- Interest rate
- Tenure
- Deposit frequency
- Applicable institution's RD calculation method
A typical calculation follows the principle that each monthly instalment earns interest for a different duration.
For example, changing the monthly instalment from Rs. 5,000 to Rs. 10,000 approximately doubles the total principal deposited over the same 60-month period. The interest earned will also generally increase, although the exact maturity amount depends on the rate and calculation method.
What is the difference between a Post Office RD and a bank RD?
| Feature | Post Office RD | Bank RD |
|---|---|---|
| Provider | India Post | Commercial bank |
| Current 5-year rate | 6.70% | Varies by bank |
| Rate setting | Government-notified small-savings rate | Bank-specific |
| Senior-citizen premium | No separate general senior-citizen rate | Many banks offer an additional rate |
| Monthly deposit | Starts from Rs. 100 under Post Office rules | Depends on bank |
| Tenure | 5 years | Depends on bank |
| Interest calculation | As prescribed under Post Office RD rules | As prescribed by the bank |
| Premature closure | Subject to Post Office rules | Subject to bank's terms |
| Deposit protection | Government small-savings framework | Eligible bank deposits covered by DICGC subject to applicable limits |
The Post Office RD's Rs. 100 minimum deposit is documented in India Post's scheme material, while bank minimums vary by institution.
What happens if you miss an RD instalment?
Missing an instalment can result in a default charge or other consequences under the institution's rules.
For a Post Office RD, the applicable default fee is prescribed under the National Savings Recurring Deposit Scheme. The account may also be treated as discontinued after multiple consecutive defaults unless it is revived according to the applicable rules.
Because bank policies differ, a bank RD's missed-payment charge should be checked against the specific bank's current terms.
How can you avoid missed instalments?
A standing instruction or automated debit can help maintain regular payments, provided sufficient funds are available in the linked account.
It is also useful to select a monthly instalment that remains manageable throughout the five-year period.
Check out different FD Rates
Can you withdraw money before five years?
Yes, but premature withdrawal is subject to the rules of the institution.
Post Office RD
The Post Office permits premature closure of an RD subject to the applicable scheme conditions. The amount payable may differ from the value that would have been received if the account had continued until maturity.
Bank RD
Banks generally permit premature closure subject to their terms and applicable interest-rate adjustments or penalties.
There is therefore no single premature-withdrawal rule applicable to every bank RD.
Is a 5-year RD eligible for a tax deduction?
A regular five-year RD should not be confused with a 5-year tax-saving fixed deposit.
The fact that an RD has a five-year tenure does not by itself make its monthly contributions eligible for a Section 80C deduction under the earlier Income-tax Act, 1961.
For tax year 2026-27 and later periods, the Income-tax Act, 2025 applies to relevant income and transactions from 1 April 2026. The new Act reorganises the earlier TDS provisions while retaining the broad tax policy and thresholds.
Tax deductions should therefore be checked against the provisions applicable to the relevant tax year rather than relying on the tenure alone.
How is RD interest taxed?
RD interest is generally taxable as income in the hands of the depositor and is included in the computation of taxable income at the applicable rate.
The tax treatment is different from the question of TDS.
What is the difference between tax and TDS?
Tax: The actual income-tax liability calculated on your taxable income.
TDS: Tax deducted by the institution at source when the applicable threshold and conditions are met.
TDS does not necessarily equal your final tax liability. The amount deducted can be considered when calculating the overall tax payable or refundable
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
What are the current TDS rules for RD interest?
For interest payments or credits from 1 April 2026, the Income-tax Act, 2025 applies. The Income Tax Department states that the new Act retains the TDS rates and monetary thresholds while consolidating the earlier TDS provisions under Section 393.
The applicable threshold and TDS treatment can depend on the type of institution and depositor. Therefore, the earlier blanket statement that every bank RD is subject to TDS only after Rs. 40,000, or Rs. 50,000 for senior citizens, should not be used without checking the applicable current provision.
For tax-year 2026-27 onward, the relevant provision under the Income-tax Act, 2025 should be referred to when determining the applicable TDS.
What are the advantages of a 5-year RD?
Regular savings
An RD allows a person to build a corpus through relatively small, periodic deposits instead of requiring a large initial amount.
Predictable returns
The applicable RD interest rate is generally fixed according to the product terms when the RD is opened.
Structured saving
A fixed monthly commitment can make it easier to set aside money for a defined five-year goal.
Suitable for planned expenses
An RD may be considered for goals such as education expenses, planned purchases or other medium-term financial requirements where a predictable maturity amount is useful.
What are the limitations of a 5-year RD?
Monthly commitment
The depositor needs to maintain sufficient funds for regular instalments.
Lower compounding on later instalments
Later deposits have less time to earn interest than earlier deposits.
Premature withdrawal conditions
Closing an RD before maturity may affect the interest payable.
Interest-rate differences
The rate offered by one bank may differ significantly from another institution's rate.
Tax on interest
The interest earned is generally taxable according to the applicable income-tax provisions.
RD vs FD: What is the difference?
| Feature | Recurring Deposit | Fixed Deposit |
|---|---|---|
| Investment method | Monthly or periodic instalments | Lump sum |
| Initial capital required | Lower | Higher |
| Interest-earning period | Different for each instalment | Entire principal starts earning from deposit date |
| Suitable for | Regular savers | People with an available lump sum |
| Maturity calculation | Based on periodic deposits | Based on deposited principal and tenure |
| Monthly saving discipline | High | Not applicable after initial deposit |
If the same total amount is available at the start, an FD and RD should not be compared only by their headline interest rate because their cash-flow patterns are different.
Is a Post Office RD safer than a bank RD?
Post Office small-savings schemes operate under the Government's small-savings framework, while eligible bank deposits are covered by DICGC deposit insurance subject to the applicable limit and conditions.
These are different protection mechanisms and should not be described as identical.
For bank deposits, DICGC deposit insurance is subject to the applicable aggregate limit per depositor per bank. The coverage includes principal and interest within the prescribed limit.
Who may consider a 5-year RD?
A 5-year RD may be relevant for someone who:
- Has regular monthly income.
- Wants to save towards a medium-term goal.
- Prefers a structured deposit product.
- Does not have a large lump sum available at the start.
- Wants relatively predictable returns rather than market-linked returns.
The suitability of an RD depends on the individual's cash flow, tax position, financial goal and other available savings options.
Locate to your nearest FD branch

Related Articles

Frequently Asked Questions
Overview
What is the Post Office RD maturity for Rs. 1,000 monthly over five years?
At 6.70% p.a., Rs. 1,000 monthly may grow to approximately Rs. 71,366. The total deposited amount is Rs. 60,000.
What is the Post Office RD scheme for five years in 2026?
It requires 60 monthly deposits and currently earns 6.70% p.a., compounded quarterly. The minimum monthly deposit is Rs. 100.
What will Rs. 2,000 monthly become after five years?
At 6.70% p.a., Rs. 2,000 monthly may mature to approximately Rs. 1,42,732. Actual maturity can differ slightly.
What will Rs. 3,000 monthly become after five years?
A monthly deposit of Rs. 3,000 may reach approximately Rs. 2,14,097 at 6.70% p.a. over five years.
Which RD is suitable for five years?
Compare interest rates, issuer credibility, minimum deposits, missed-instalment rules, and withdrawal conditions. The suitable RD depends on your requirements.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.