








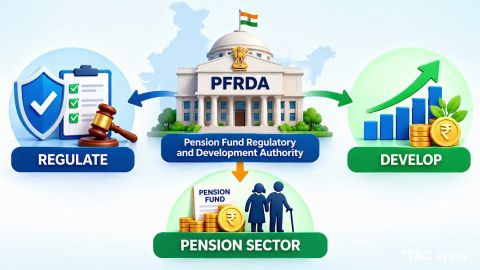
PFRDA - Pension Fund Regulatory and Development Authority
-
In summary
PFRDA establishes regulatory frameworks, supervises pension intermediaries, protects subscriber interests, and supports the development of India's pension sector.
- PFRDA stands for Pension Fund Regulatory and Development Authority.
- The Interim PFRDA was established on 23 August 2003.
- PFRDA became a statutory authority after enactment of the PFRDA Act, 2013.
- It regulates the National Pension System and supervises registered pension intermediaries.
- PFRDA also administers Atal Pension Yojana within the NPS architecture.
Its current ecosystem includes NPS, NPS Vatsalya and the Unified Pension Scheme framework.
The authority therefore performs both regulatory and developmental functions rather than directly operating every subscriber-facing pension service itself.
-
What is PFRDA and Its Full Form?
PFRDA stands for Pension Fund Regulatory and Development Authority, India's statutory pension-sector regulator established under the PFRDA Act, 2013. The Government initially established the Interim Pension Fund Regulatory and Development Authority on 23 August 2003 through an executive resolution. The PFRDA Act was enacted on 19 September 2013 and became effective on 1 February 2014, creating today's statutory authority.
The original article's term “IPRDA” should therefore not be used as the current or historical official abbreviation. PFRDA's statutory objective includes promoting old-age income security, developing pension funds, regulating them, and protecting pension-scheme subscribers.
-
PFRDA Role and Responsibilities
PFRDA regulates pension schemes and intermediaries through legislation, regulations, circulars, guidelines, registrations, supervision, and subscriber-protection mechanisms.
Role Current responsibility Pension regulation Frames and enforces regulations governing pension schemes and intermediaries Subscriber protection Establishes standards intended to protect subscriber rights and pension assets Intermediary supervision Registers and supervises pension funds, CRAs, PoPs and other regulated entities Compliance Monitors compliance with the PFRDA Act, regulations, circulars and directions Grievance framework Provides structured mechanisms for escalating unresolved subscriber grievances Pension development Supports wider participation and development of organised retirement savings Disclosure standards Requires regulated entities to follow applicable reporting and disclosure requirements PFRDA's current regulatory activity continues evolving, with multiple active circulars and guidelines issued during 2026.
Objectives of PFRDA
Avoid these mistakes while booking FD
-
PFRDA's broader objectives centre on building a sustainable, organised, transparent, and subscriber-focused pension system.
Key objectives include:
- Promoting old-age income security
- Developing and regulating pension funds
- Protecting subscriber interests
- Supporting orderly pension-sector development
- Registering and supervising regulated intermediaries
- Strengthening grievance-redressal systems
- Improving retirement-planning awareness
Establishing appropriate governance and disclosure frameworks
These objectives extend beyond investment management because pension administration also involves recordkeeping, fund movement, distribution, custody, and annuity services.
-
Functions of the Pension Fund Regulatory and Development Authority (PFDRA)
PFRDA supervises the broader National Pension System architecture and sets regulatory requirements for its participating entities.
Its important functions include:
- Regulating pension funds and approved pension structures
- Registering and supervising pension intermediaries
- Monitoring investment-management and operational standards
- Protecting pension subscribers through regulatory requirements
- Supporting pension and retirement awareness
- Establishing withdrawal and exit frameworks
- Overseeing grievance-redressal mechanisms
- Issuing regulations, circulars, guidelines, and supervisory directions
PFRDA also supervises Central Recordkeeping Agencies, Trustee Banks and Annuity Service Providers through dedicated regulatory and supervisory functions.
Also read: What is Employee Pension Scheme
Intermediaries under PFRDA
-
PFRDA's pension architecture uses specialised intermediaries rather than requiring one organisation to perform every administrative and investment-management function.
Intermediary Main function NPS Trust Oversees subscriber assets and specified intermediary activities Central Recordkeeping Agencies Maintain subscriber records, accounts and administrative systems Pension Funds Invest pension contributions according to applicable regulations Points of Presence Provide subscriber registration and servicing facilities Trustee Bank Manages regulated fund-flow and settlement activities Custodian Safekeeps securities and performs related custodial functions Retirement Advisors Provide regulated NPS advisory services Annuity Service Providers Provide eligible annuity products during applicable exits -
PFRDA guidelines for NPS
NPS operates as a defined-contribution system where accumulated value depends upon contributions, investment performance, charges, and the selected investment structure.
For many non-government subscribers, current Common Schemes include:
- Equity: Up to 75% under applicable Active Choice rules
- Corporate Bonds: Up to 100%
- Government Securities: Up to 100%
- Alternative Investment Funds: Up to 5%
Auto Choice provides age-linked lifecycle allocations, while PFRDA has also introduced a Multiple Scheme Framework for eligible non-government subscribers.
PFRDA's exit regulations were most recently amended on 20 July 2026, making older fixed withdrawal descriptions unsuitable for current migration content.
-
Online services of PFRDA
Many subscriber services are delivered digitally through registered CRAs, Points of Presence, and authorised pension-system platforms operating under PFRDA oversight.
Depending on the scheme and subscriber category, digital facilities can include:
- Opening eligible NPS accounts
- Making pension contributions
- Updating permitted subscriber information
- Changing eligible investment choices
- Activating eligible Tier II facilities
- Viewing or downloading transaction statements
- Submitting eligible exit or withdrawal requests
- Registering grievances
- Accessing electronic PRAN information
PFRDA itself primarily acts as regulator, while registered intermediaries provide much of the operational interface used by individual subscribers.
Also read: What is Atal Pension Yojana
-
PFRDA contact information
PFRDA's official contact information has changed from the telephone numbers appearing in several older articles.
Contact detail Current information Address E-500, Tower E, 5th Floor, World Trade Centre, Nauroji Nagar, New Delhi – 110029 Main phone 011-40717900 NPS toll-free 1800 110 708 UPS toll-free 1800 571 2930 APY toll-free 1800 110 069 Official website pfrda.org.in Also Read: What is Commutation of Pension?
-
Conclusion
PFRDA is the statutory authority responsible for regulating and developing India's organised pension sector while protecting the interests of pension subscribers.
Its ecosystem has changed considerably, making current regulations and intermediary details important when understanding NPS, APY, UPS, or NPS Vatsalya. The Department of Financial Services, Ministry of Finance, handles legislative and policy matters concerning PFRDA as India's pension-sector regulatory body.
Pension products should also be distinguished from Fixed Deposits because they serve different purposes, structures, risks, and retirement-planning requirements. For predictable fixed returns outside the PFRDA pension framework, investors may separately consider Bajaj Finance Fixed Deposit. Current rates reach 7.40% p.a. for customers below 60 and 7.75% p.a. for eligible senior citizens.
Calculate your expected investment returns with the help of our Fixed Deposit and Recurring Deposit calculators.
Check out different FD Rates
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
Locate to your nearest FD branch

Related Articles

Frequently Asked Questions
Overview
What is the role of PFRDA?
PFRDA regulates and develops India's pension sector, supervises registered intermediaries, and establishes frameworks intended to protect pension subscribers. It also regulates the NPS ecosystem and administers specified pension initiatives according to applicable legislation, regulations, and government frameworks.
Which companies are under the Pension Fund Regulatory and Development Authority?
PFRDA regulates registered pension intermediaries including Pension Funds, CRAs, Points of Presence, the Trustee Bank, custodian, and retirement advisors. It also oversees specified functions involving NPS Trust and empanelled Annuity Service Providers within the regulated pension architecture.
Is Pension Fund Regulatory and Development Authority a statutory body?
Yes, PFRDA is a statutory authority established under the Pension Fund Regulatory and Development Authority Act, 2013. The Act became effective on 1 February 2014, replacing the earlier interim regulatory arrangement with a statutory framework.
Where is the headquarter of PFRDA?
PFRDA's head office is located at E-500, Tower E, World Trade Centre, Nauroji Nagar, New Delhi – 110029. Its official main telephone number is currently 011-40717900, according to the authority's published contact information.
Which ministry department is PFRDA under?
PFRDA functions under the Ministry of Finance, Government of India.
Who regulates PFRDA in India?
PFRDA itself is an independent statutory regulator whose powers, structure, and responsibilities are established through the PFRDA Act and related rules. The Department of Financial Services handles relevant legislative and policy matters rather than functioning as another pension regulator above PFRDA.
What are the investment options under PFRDA's NPS?
Eligible NPS subscribers can access asset classes including equity, corporate bonds, government securities, and specified alternative investments under applicable rules.
Available choices can include Active Choice, lifecycle-based Auto Choice, and newer scheme structures depending upon subscriber category and prevailing PFRDA regulations.
How can I withdraw my pension funds from PFRDA?
NPS withdrawals are submitted through the applicable CRA, Point of Presence, or authorised digital facility rather than withdrawing money directly from PFRDA. Eligibility, lump-sum treatment, annuity requirements, and other payout choices depend upon the subscriber's exit category and current PFRDA regulations.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.