








Types of Fixed Deposit: Features, Options & Comparison
-
In Summary
An NRI Fixed Deposit allows eligible non-residents to place money in a deposit with an Indian financial institution and earn interest over a specified tenure. Before investing, it is important to check the deposit type, source of funds, applicable interest rate, payout frequency, tax treatment and rules governing the transfer of money outside India.
Bajaj Finance accepts NRI Fixed Deposit applications through its branch or representative process. The published requirements include a PAN, passport, visa or relevant residence or work-permit documentation, and funds from an eligible Non-Resident Ordinary (NRO) bank account.
Interest earned on an NRI deposit may be subject to Indian tax and tax deducted at source (TDS). Relief under a Double Taxation Avoidance Agreement (DTAA) may be available if the relevant conditions are met.
Before applying:
- Confirm your eligibility and the latest NRI-specific deposit terms.
- Check the interest rate and tenure available for your deposit.
- Understand tax and repatriation rules.
- Prepare the required documents and confirm the accepted payment method.
What is an NRI Fixed Deposit?
-
An NRI Fixed Deposit is a deposit held by an eligible non-resident with a bank or other financial institution in India. The depositor places a sum of money for a specified period and earns interest according to the agreed terms.
The exact rules depend on the type of deposit and the institution accepting it. For example, bank deposits under the Non-Resident External (NRE), Non-Resident Ordinary (NRO) and Foreign Currency Non-Resident (Bank) [FCNR(B)] categories have different currency, tax and repatriation features. These bank deposit categories should not be confused with a corporate fixed deposit offered by a non-banking financial company (NBFC).
A Bajaj Finance Fixed Deposit for eligible non-residents is a company deposit. According to the published application information, the investment must be funded through an eligible NRO account and the application must be submitted through the prescribed offline process.
What are the features of an NRI Fixed Deposit?
Avoid these mistakes while booking FD
-
The features vary by issuer and deposit type. Before investing, review the following.
1. Interest earnings
The interest rate is determined by the issuer and may vary according to the tenure, deposit amount and payout option. Check the rate applicable specifically to NRI applicants before completing an application.
Do not assume that the rates displayed on a general resident FD page apply to NRI deposits. Ask the issuer or its authorised representative to confirm the current rate and the estimated maturity or periodic interest amount in writing.
2. Choice of tenure
The tenure determines how long the money remains deposited. Choose a period that fits your expected financial needs, including any planned expenses in India or overseas.
Bajaj Finance’s NRI Fixed Deposit page refers to tenures of 12 to 36 months. Confirm the currently available tenure options and the applicable terms before applying.
3. Interest payout options
Depending on the product, an FD may offer:
- Cumulative payout: Interest accumulates and is paid with the principal at maturity, according to the deposit terms.
- Non-cumulative payout: Interest is paid periodically, such as monthly, quarterly, half-yearly or annually, where offered.
A periodic payout may be useful if you need regular income in India. A cumulative deposit may suit a goal for which you expect to use the proceeds at maturity. Confirm which options are available to NRI applicants rather than relying on the options listed for resident customers.
4. Credit ratings
Bajaj Finance states that its Fixed Deposit carries CRISIL AAA/STABLE and [ICRA]AAA(Stable) ratings. Credit ratings provide an assessment of credit risk under the rating agency’s methodology; they are not a guarantee of repayment.
A company fixed deposit is not the same as an insured bank deposit. Deposits accepted by NBFCs are not covered by DICGC deposit insurance. Consider the issuer’s financial position, the deposit terms and your ability to keep the money invested for the selected period.
5. Renewal at maturity
The renewal process depends on the issuer and the instructions provided by the depositor. Before the maturity date, confirm whether renewal is available for NRI customers, what rate would apply to a renewed deposit and how the maturity proceeds can be paid.
Do not assume that an existing deposit automatically renews at the original rate.
Calculate returns on FD using Fixed Deposit Calculator
Who can invest in a Bajaj Finance NRI Fixed Deposit?
Bajaj Finance’s published NRI Fixed Deposit page identifies the following customer groups:
- Non-Resident Indians (NRIs)
- Overseas Citizens of India (OCI)
- Eligible Persons of Indian Origin (PIO)
Eligibility remains subject to the issuer’s requirements, applicable law and the documents provided. A person’s immigration status or nationality alone should not be treated as confirmation of eligibility.
Before applying, contact Bajaj Finance or its authorised representative to confirm whether your category of residence, citizenship or overseas documentation is accepted.
What documents are required for an NRI Fixed Deposit?
The documents required depend on the applicant’s circumstances and the issuer’s KYC requirements. Bajaj Finance’s published information identifies the following documents for NRI applicants.
- PAN: Permanent Account Number details.
- Passport: A valid passport as proof of identity.
- Visa or residence documentation: Relevant visa, work permit, permanent residence permit or other documentation requested by the issuer.
- Address proof, where required: An accepted Indian address document or other evidence specified during the application.
- NRO bank details: Bank statement, passbook or other account evidence as requested.
- Signed application form: The completed and signed form required for the deposit.
Additional documentation may be requested depending on the applicant’s circumstances. Confirm the latest checklist before sending documents or arranging payment.
How can an NRI open a Bajaj Finance Fixed Deposit?
Bajaj Finance’s published information states that NRIs need to submit the required KYC documents and a signed application form at a Bajaj Finance branch. NRIs should confirm the current application procedure with an authorised representative before proceeding.
The general process is as follows:
- Contact Bajaj Finance or an authorised representative. Confirm your eligibility, current NRI deposit options, interest rates, tenure and application requirements.
- Obtain the application form. Request the relevant NRI Fixed Deposit application form and instructions for submission.
- Prepare the documents. Gather your PAN, passport, visa or relevant residence or work-permit documents, and any address or bank documents requested.
- Select the deposit terms. Confirm the deposit amount, tenure, interest payout option, maturity instructions and premature withdrawal conditions.
- Arrange payment from your NRO account. Bajaj Finance’s published guidance specifies an NRO account as the source of funds. Confirm the accepted payment method and account details before making the transfer.
- Submit the signed application and supporting documents. Follow the branch or representative’s instructions and retain proof of submission.
- Confirm the booking. Obtain the deposit acknowledgement and receipt. Check that the deposit amount, applicable interest rate, tenure and maturity details are accurate.
Do not transfer funds from an NRE or FCNR(B) account on the assumption that the payment will be accepted. Confirm the permitted source of funds and payment instructions before initiating the transaction.
Which bank account can be used to invest in a Bajaj Finance NRI Fixed Deposit?
Bajaj Finance’s published NRI Fixed Deposit information specifies that funds must be received from an NRO account. It also lists cheque, NEFT and RTGS as accepted payment methods, subject to the current terms.
An NRO account is generally used to manage eligible income and financial transactions in India for a person resident outside India. It is distinct from an NRE account, which has different rules for permitted credits, tax treatment and repatriation.
Before transferring funds, verify the following with the issuer:
- The NRO account from which payment must be made.
- Whether a cheque, NEFT or RTGS is accepted for your application.
- The correct beneficiary and payment reference details.
- How funds will be returned if the application cannot be completed.
- The bank account to which interest or maturity proceeds will be paid.
This check can help avoid delays caused by an incorrect source account or an unsupported payment method.
How is an NRI Fixed Deposit taxed in India?
Tax treatment depends on the type of deposit, the depositor’s tax status and the applicable law. Do not assume that all deposits held by NRIs are tax-free.
Is TDS applicable to NRI Fixed Deposit interest?
Interest earned on a company fixed deposit may be subject to tax deducted at source (TDS) under the applicable Indian tax rules. The applicable rate, documentation requirements and final tax liability depend on the circumstances and rules in force.
TDS is a tax deduction made at the time specified by law. It is not necessarily the final amount of tax payable. An NRI may need to consider the interest when determining Indian tax-filing obligations.
Check the current guidance from the Income Tax Department and obtain tax advice if you are unsure how the rules apply to your deposit.
Can an NRI claim benefits under a DTAA?
India has Double Taxation Avoidance Agreements (DTAAs) with various countries. These agreements may provide relief where income is taxable under the laws of more than one country.
However, relief is not automatic. Eligibility depends on the agreement between India and the country concerned, the nature of the income, tax residency and the documentation or other conditions required. A DTAA does not necessarily mean that no Indian tax or TDS will apply.
Before investing, check the rules relevant to your country of tax residence and seek professional advice where necessary.
Is a Bajaj Finance NRI Fixed Deposit tax-free?
Do not assume that interest from a Bajaj Finance NRI Fixed Deposit is tax-free. The tax treatment should be confirmed under the rules applicable to the deposit and the depositor’s circumstances. TDS may apply, and any treaty relief is subject to the relevant conditions.
Check out different FD Rates
Can an NRI repatriate the interest and maturity proceeds?
Repatriation means transferring money from India to another country. The rules depend on the type of account, source of funds, nature of the deposit and applicable foreign-exchange regulations.
NRE, NRO and FCNR(B) bank deposits have different repatriation features. For example, balances in an NRO account are generally subject to prescribed conditions and limits when transferred abroad. These rules should not be automatically applied to every company deposit.
Before investing in a Bajaj Finance Fixed Deposit, ask the issuer how interest and maturity proceeds will be paid and what documentation is needed if you intend to transfer the money overseas. You may also need advice from your bank or a qualified tax professional.
Can an NRI withdraw a Bajaj Finance Fixed Deposit before maturity?
Premature withdrawal conditions depend on the specific deposit terms and applicable rules. An early withdrawal may be restricted or may change the interest payable.
Before booking, confirm:
- Whether premature withdrawal is permitted for the deposit.
- Any minimum holding period or other restrictions.
- How interest would be calculated if the deposit is closed early.
- The process and documents needed to request withdrawal.
Do not assume that the rules for an NRE bank FD or an ordinary resident FD automatically apply to a company deposit held by an NRI.
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
Can an NRI take a loan against a Bajaj Finance Fixed Deposit?
The NRI Fixed Deposit page states that loans against fixed deposits are not available to NRIs, OCIs and other eligible people of Indian origin under this product. Confirm the current terms with the issuer if this feature is important to your financial planning.
If access to funds during the deposit tenure is a priority, compare the withdrawal conditions and liquidity arrangements before investing. Do not commit money that may be needed for immediate expenses without understanding the restrictions.
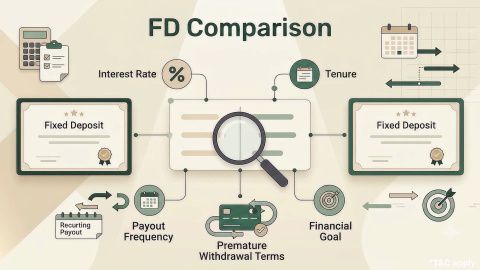
How should you compare an NRI Fixed Deposit before investing?
Compare the terms that affect the amount you receive and your ability to access the money.
| Factor | What to check |
|---|---|
| Interest rate | Confirm the current rate applicable specifically to NRI applicants. |
| Tenure | Choose a period that matches when you expect to need the funds. |
| Interest payout | Compare cumulative and periodic payout options available to you. |
| Source of funds | Confirm which NRI account may be used to make the deposit. |
| Tax treatment | Check Indian tax and TDS rules, as well as any relevant DTAA conditions. |
| Repatriation | Understand the rules for transferring proceeds overseas. |
| Premature withdrawal | Check restrictions and the effect on interest if you need the money early. |
| Credit risk | Review the issuer’s financial information and credit ratings, without treating ratings as a repayment guarantee. |
| Deposit insurance | Check whether the deposit is covered by any applicable insurance scheme. |
| Maturity instructions | Confirm how proceeds will be paid and whether renewal is available. |
The most suitable option depends on your financial goals, the time for which you can set aside the funds, and the tax and repatriation rules relevant to your circumstances.
Locate to your nearest FD branch

Related Articles

Frequently Asked Questions
Overview
Can an NRI invest in a fixed deposit in India?
Yes, eligible NRIs can invest in certain fixed deposits in India, subject to the institution’s eligibility criteria and applicable regulations. The permitted source of funds, tax treatment, documents and repatriation rules depend on the deposit type and issuer.
Can an NRI open a Bajaj Finance Fixed Deposit online?
Bajaj Finance’s published information states that NRI applicants must submit KYC documents and a signed application form at a Bajaj Finance branch. Contact the company or an authorised representative to confirm the current process before applying.
What is the tenure of a Bajaj Finance NRI Fixed Deposit?
The NRI Fixed Deposit page refers to tenures between 12 and 36 months. Confirm the current options and the rate applicable to your chosen tenure with Bajaj Finance before booking.
Which account can an NRI use to invest in a Bajaj Finance Fixed Deposit?
The published NRI-specific guidance specifies payment from an NRO account. Confirm the permitted source account and accepted payment method before transferring money. Do not assume that payment from an NRE or FCNR(B) account will be accepted.
Does an NRI have to pay tax on FD interest in India?
Interest on an NRI deposit may be taxable in India, and TDS may apply. The actual tax treatment depends on the deposit, the applicable tax rules and the depositor’s circumstances. DTAA relief may be available if the relevant conditions are met.
Are NRI Fixed Deposits covered by DICGC insurance?
DICGC deposit insurance applies to eligible deposits held with insured banks, subject to its rules and limits. Company fixed deposits accepted by NBFCs are not covered by DICGC insurance. Check the nature of the deposit before investing.
Can an NRI nominate someone for a Bajaj Finance Fixed Deposit?
Bajaj Finance’s published NRI Fixed Deposit page states that nomination is available. Confirm the nomination process, required details and applicable terms when completing the application.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.