








- Life cover with built-in savings
- Guaranteed returns on maturity
- Ideal for long-term goals like education or retirement
- Flexible premium payment options
- Peace of mind with financial protection for your family
-
People’s trust in Bajaj
-
10 million+
Customers
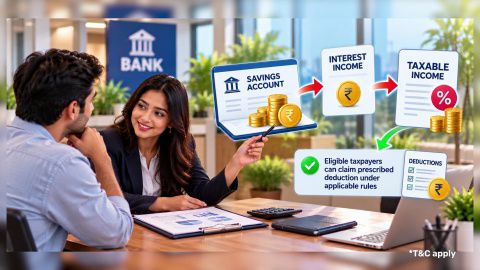
How to avoid tax on savings account interest
In summary
Savings account interest is taxable, but you can legally reduce the tax payable on eligible interest through the available deduction.
- Section 153 allows a deduction of up to Rs. 10,000 on savings account interest for individuals who are not senior citizens and HUFs.
- Resident senior citizens can claim up to Rs. 50,000 on interest from eligible deposits, including time deposits.
- The deduction is available under the old tax regime. Interest should still be reported in your income tax return.
Managing savings account interest can help reduce your tax burden through eligible deductions. For long term goals, savings plans can combine disciplined savings with life cover and financial protection.
How is interest from a savings account taxed?
Easy Savings for Big Goals
From 1 April 2026, the earlier Sections 80TTA and 80TTB have been consolidated into Section 153 of the Income Tax Act, 2025. The deduction limits continue at Rs. 10,000 for eligible non senior individuals and HUFs, and Rs. 50,000 for eligible senior citizens.
| Taxpayer | Eligible interest | Maximum deduction |
|---|---|---|
| Individual who is not a senior citizen | Savings account interest | Rs. 10,000 |
| HUF | Savings account interest | Rs. 10,000 |
| Resident senior citizen | Interest on eligible deposits, including time deposits | Rs. 50,000 |
The deduction is not a blanket exemption from tax. For example, if an eligible non senior individual earns Rs. 14,000 as savings account interest, up to Rs. 10,000 may qualify for deduction and the remaining Rs. 4,000 remains taxable, subject to the applicable tax rules.
How is savings account interest calculated?
A simple formula is:
Interest for a day = End of day balance × annual interest rate ÷ number of days in the year
For example, if you maintain Rs. 1 lakh throughout a 365 day year and the applicable interest rate is an illustrative 3% per year:
Rs. 1,00,000 × 3% = Rs. 3,000
The actual amount depends on the bank's applicable interest rate and your daily balance. Interest may be credited monthly, quarterly or at another frequency according to the bank's terms.
What are the most preferred strategies to reduce tax on savings interest?
1. Claim the Section 153 deduction:
Section 153 of the Income Tax Act, 2025 allows eligible taxpayers to claim a deduction on interest from deposits:
- Up to Rs. 10,000 for individuals who are not senior citizens and HUFs on savings account interest.
- Up to Rs. 50,000 for resident senior citizens on interest from eligible deposits, including time deposits.
The deduction is available under the old tax regime. You should include your interest income when calculating your taxable income.
2. Manage funds across multiple accounts:
Keeping money across multiple savings accounts can help you organise funds for different expenses and goals, but it does not increase the Section 153 deduction limit or make the interest tax exempt.
Track the interest earned across all your accounts so that you report the correct amount while filing your tax return.
3. Consider life insurance savings plans for long term goals:
Life insurance savings plans can combine long term savings with life cover and may suit goals such as retirement or children's education.
Eligible term insurance premiums may qualify for a deduction of up to Rs. 1.5 lakh per financial year under Section 123, replacing Section 80C from 1 April 2026, subject to applicable conditions and the old tax regime. Eligible death cover payouts may also qualify for exemption under Section 11, replacing Section 10(10D).
For ULIPs, returns are linked to market performance and are not guaranteed.
4. Consider eligible tax saving investments:
If you have surplus funds beyond your immediate savings needs, you can consider investments that qualify for deductions under applicable tax provisions, such as:
- Public Provident Fund (PPF)
- National Savings Certificate (NSC)
- Sukanya Samriddhi Yojana
- Eligible provident fund contributions
- Certain five year tax saving deposits
- Eligible life insurance premiums
Section 123 provides an aggregate deduction of up to Rs. 1.5 lakh for specified payments and investments, subject to applicable conditions.
5. Track your interest earnings actively:
Most people forget to include savings account interest while filing ITRs—or worse, underreport it unintentionally. This can attract notices from the IT Department.
Stay compliant by:
- Monitoring your bank statements regularly
- Downloading TDS certificates from NetBanking or the TRACES portal
- Logging interest income in a simple spreadsheet each year
Being proactive protects you from scrutiny and helps you maximise deductions.
Explore life insurance plans based on your age, income, lifestyle and life goals. Choose the one that suits you the most and get quote in a few minutes!.
Can you avoid tax on savings account interest in the new tax regime?
For the old regime:
- Section 80TTA: Individuals other than senior citizens and HUFs can claim up to Rs. 10,000 on interest from eligible savings accounts.
- Section 80TTB: Resident senior citizens can claim up to Rs. 50,000 on eligible deposit interest, including savings and fixed deposits.
So, if your main aim is to reduce tax on savings account interest, Section 80TTA or Section 80TTB cannot be used after choosing the new tax regime.
How can you avoid tax on savings account interest in India?
| Strategy | Who it applies to | Tax saving potential | New regime availability |
|---|---|---|---|
| Section 80TTA deduction | Individuals below 60 and HUFs | Up to Rs. 10,000 on eligible savings account interest | Not available |
| Section 80TTB deduction | Resident senior citizens | Up to Rs. 50,000 on eligible deposit interest | Not available |
| Eligible tax saving investments | Taxpayers choosing the old regime | Deduction depends on the investment and applicable limit | Generally not available |
| Report interest correctly in ITR | Taxpayers earning savings interest | Helps claim eligible deductions and avoid incorrect reporting | Applicable |
| Submit Form 15G or 15H where applicable | Eligible taxpayers meeting the conditions | Can help avoid TDS where permitted; it does not make interest tax exempt | Subject to applicable rules |
Section 80TTA covers up to Rs. 10,000 of eligible savings account interest, while Section 80TTB allows resident senior citizens to claim up to Rs. 50,000 on eligible deposit interest. These deductions are available under the old tax regime.
Tax saving investments such as eligible life insurance policies may provide separate deductions under the applicable provisions when you choose the old regime. However, moving money from a savings account into another investment does not automatically make the original interest tax exempt.
Always report your interest income in your income tax return and claim only the deductions applicable to you.
Conclusion
Savings account interest is taxable, but eligible taxpayers can reduce their taxable interest through the Section 153 deduction. For an eligible non senior individual or HUF, the deduction is capped at Rs. 10,000, while a resident senior citizen can claim up to Rs. 50,000 on eligible deposit interest.
The deduction is available under the old tax regime. You should report the interest earned and compare the tax impact of both regimes before making your choice. For long term financial protection, consider life insurance separately from your savings strategy. Term insurance can provide life cover for dependants, while savings accounts can continue to meet short term liquidity needs.
Income Tax Sections and Saving Tips
Explore more and stay informed
Frequently asked questions
Frequently asked questions
How much savings account interest is tax exempt?
Savings account interest is not automatically tax exempt. Under Section 153 of the Income Tax Act, 2025, an eligible individual who is not a senior citizen or an HUF can claim a deduction of up to Rs. 10,000 on savings account interest. A resident senior citizen can claim up to Rs. 50,000 on eligible deposit interest, including time deposits.
Is there a legal way to avoid tax on savings account interest?
You cannot simply make taxable interest disappear by transferring, spending or reinvesting it. However, eligible taxpayers can reduce their taxable interest through the Section 153 deduction. The maximum deduction is Rs. 10,000 for eligible non senior individuals and HUFs and Rs. 50,000 for resident senior citizens on qualifying deposit interest.
Can I reinvest savings interest to avoid tax?
No. Reinvesting or transferring the interest does not by itself remove the tax liability. The interest earned must be considered when calculating your income. If you are eligible, you can claim the applicable Section 153 deduction. Any interest remaining after the eligible deduction is included in your taxable income.
How is tax calculated on interest earned from a savings account?
Savings account interest is generally added to your income from other sources and taxed according to the applicable tax regime and slab. For example, if you earn Rs. 14,000 as savings interest and qualify for the Rs. 10,000 Section 153 deduction, Rs. 4,000 remains after that deduction and is considered for taxation.
What is the maximum savings account balance allowed in India without tax?
There is no general maximum savings account balance below which the account balance itself becomes taxable. Tax is generally linked to the income earned, such as interest, rather than the amount lying in the account. Savings account interest must be considered for tax purposes, with eligible deductions available under Section 153.
Is savings account interest taxable under the new tax regime in India?
Yes. Savings account interest is taxable under the new tax regime and must be included in your taxable income. Section 80TTA and Section 80TTB deductions cannot be claimed under the new regime. These deductions are available when you choose the old tax regime and meet the applicable conditions.
How do I report savings account interest in my ITR?
Report savings account interest as income from other sources in your ITR. Check your bank statements, interest certificates and AIS to report the correct amount. If you choose the old regime, claim any eligible Section 80TTA or 80TTB deduction while filing your return.
Should I submit Form 15G or Form 15H to avoid tax on savings interest?
Form 15G is generally used by eligible resident individuals below 60 and certain other taxpayers, while Form 15H is for resident individuals aged 60 or above. They request non deduction of TDS where conditions are met; they do not make interest tax exempt.




