








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
In summary
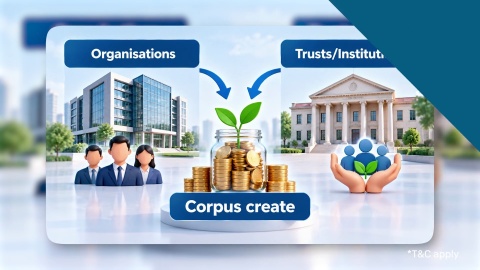
Corpus Fund
A corpus fund helps an organisation set aside money for a defined long-term purpose.
- A corpus fund is a long-term reserve.
- It is kept for a defined purpose.
- Donations and grants can build the corpus.
- Its use depends on applicable rules.
- It may be invested if permitted.
A corpus fund is different from a mutual fund. An organisation may invest part of its corpus in permitted investment avenues, but the corpus itself is not a mutual fund.
What is a corpus fund?
A corpus fund is money set aside and maintained for a specific long-term purpose. It is generally separate from money used for an organisation's routine expenses.
For a charitable organisation, a donation can form part of the corpus when the donor gives a specific direction that it should be treated as corpus. Current Income Tax Department rules require records of donations received with such a specific direction.
The exact rules for creating, maintaining, investing, or using a corpus depend on the organisation's structure, governing documents, donor conditions, and applicable laws.
A corpus fund should therefore not be viewed as money that can automatically be used for any expense.
Corpus fund and mutual fund: understanding the difference
A corpus fund and a mutual fund serve different purposes.
A corpus fund is a pool of money maintained by an organisation or for a defined purpose. A mutual fund is an investment vehicle that pools money from investors and invests it according to a stated investment objective.
An organisation may choose to invest part of its corpus in mutual funds if its governing documents, investment policy, and applicable rules allow it. However, the corpus itself does not become a mutual fund simply because some of the money is invested in one.
You can learn more about mutual funds to understand how this investment product works.
Sources of a corpus fund
The source of a corpus depends on the type of organisation and the rules that apply to it. Common sources can include donations, grants, and other permitted contributions.
Corpus donations
A corpus donation is a contribution made with a specific direction that it should form part of the corpus. The organisation should maintain the required records and follow the applicable conditions.
For charitable or religious organisations, the Income Tax Department has specific requirements relating to donations received with a direction that they form part of the corpus.
Grants and other permitted contributions
An organisation may receive grants or other contributions that can support its long-term financial resources. However, a grant should not automatically be treated as corpus.
The terms attached to the grant or contribution should be checked before classifying it as part of the corpus.
How a corpus fund can be used
The use of corpus money depends on the purpose for which it was created and the conditions governing it. It may support long-term activities, projects, or other permitted requirements.
Possible uses can include:
- Supporting a defined long-term project.
- Funding permitted capital expenditure.
- Supporting charitable or institutional activities.
- Meeting an approved financial requirement.
- Providing funds for a specified long-term objective.
The organisation should check its governing documents, donor conditions, and applicable laws before using corpus money. The fact that money is held as a corpus does not by itself mean that it can be used without restrictions.
How an organisation establishes a corpus fund
Creating a corpus involves more than setting money aside in a separate account. The organisation should establish a clear purpose and determine how the money will be managed.
The process may include:
- Define the purpose of the corpus.
- Identify the permitted sources of funding.
- Establish the rules governing its use.
- Decide how the money will be held.
- Set up appropriate accounting and record-keeping.
- Establish the required approval and oversight process.
- Review the corpus periodically.
The exact process can vary between organisations. A charitable trust, educational institution, and other types of organisations may be subject to different legal and governance requirements.
A suitable investment strategy can also be considered when the corpus is permitted to be invested.
Investing a corpus fund
An organisation may invest its corpus when this is permitted by its governing documents, investment policy, donor conditions, and applicable regulations.
The investment decision should consider:
- Purpose of the corpus.
- Investment horizon.
- Liquidity requirements.
- Risk level.
- Applicable restrictions.
- Tax treatment.
- Diversification.
Investment returns are not guaranteed. If the corpus is invested in market-linked products such as mutual funds, its value can rise or fall with market conditions.
SEBI's investor material highlights that mutual fund investments involve market risks and that there is no assurance or guarantee that a scheme will achieve its investment objective.
Mutual funds as a possible investment avenue
Mutual funds can be one possible investment avenue for a corpus where the organisation is permitted to use them.
For example, an organisation may consider a mutual fund based on its investment horizon, liquidity needs, and risk level. The choice should be made according to the organisation's investment policy and applicable requirements rather than simply because a particular fund has delivered strong past returns.
You can explore mutual fund schemes to understand the range of schemes available. You can also compare mutual funds based on relevant factors before making an investment decision.
If an organisation invests in mutual funds through an applicable platform, it should also complete the required KYC and other formalities.
Worked example of a corpus fund
Suppose an educational trust receives a Rs. 10 lakh donation with a specific direction that the amount should form part of its corpus.
The trust records the donation as corpus according to the applicable requirements. It then follows its governing documents and applicable rules to decide how the money should be held or invested.
If the trust is permitted to invest part of the corpus in a mutual fund, it would need to consider the purpose of the corpus, how soon the money may be required, its liquidity needs, and the level of market risk it can take.
The example is illustrative. The actual treatment of corpus money depends on the organisation's legal structure, governing documents, donor conditions, and applicable regulations.
Benefits and limitations of maintaining a corpus
A corpus can give an organisation a dedicated pool of money for its defined long-term objectives. It can also help separate long-term financial resources from funds intended for routine expenses.
However, maintaining a corpus also requires careful governance. Money may be subject to restrictions, and investments made with corpus funds can carry risks.
If the corpus is invested, inflation can also reduce its purchasing power over time. At the same time, taking excessive investment risk may expose money meant for a long-term purpose to losses.
The organisation therefore needs to balance its purpose, liquidity requirements, investment horizon, and risk level.
Common considerations for corpus fund management
Good corpus management requires clear records and appropriate oversight.
An organisation should:
- Keep records of the source of corpus money.
- Document conditions attached to donations or grants.
- Follow the rules governing use of the corpus.
- Maintain appropriate accounting records.
- Review investments periodically.
- Keep investment decisions aligned with the corpus objective.
For charitable organisations, current Income Tax Department guidance also requires specific records relating to corpus donations and their application or investment.
Explore Investment Tools
Articles and Insights

Frequently asked questions
Understanding corpus funds
Managing and using corpus funds
Investing corpus funds
What is the main purpose of a corpus fund?
A corpus fund provides a pool of money for a defined long-term purpose. An organisation may maintain it separately from funds used for routine expenses. The exact purpose and rules for using the corpus depend on the organisation's governing documents, donor conditions, and applicable laws. A corpus can support long-term financial planning, but it should not be treated as an unrestricted pool of money.
What types of organisations can establish a corpus fund?
Charitable trusts, non-profit organisations, educational institutions, and other organisations may establish or maintain corpus funds where appropriate. The rules depend on the organisation's legal structure and governing documents. A corpus may be created from donations, grants, or other permitted sources. Before treating a contribution as corpus, the organisation should check whether any specific direction or condition applies to that contribution.
Can a corpus fund be used for expenses?
It can be used in some circumstances, but there is no single rule that allows every organisation to use corpus money for any expense. The organisation should check its governing documents, donor conditions, applicable laws, and required approvals. If the corpus is subject to a specific purpose, using it for an unrelated expense may not be permitted.
Can a corpus fund be withdrawn?
A corpus fund is not normally a personal investment account that an individual can simply withdraw from. Whether corpus money can be used, transferred, or withdrawn depends on the organisation's governing documents, the conditions attached to the money, applicable laws, and the required approvals. If the corpus is invested, the terms of the particular investment will also apply.
Can a corpus fund be invested in mutual funds?
Yes, an organisation may invest corpus money in mutual funds where this is permitted by its governing documents, investment policy, donor conditions, and applicable regulations. The organisation should consider the corpus's purpose, investment horizon, liquidity needs, and risk level. Mutual fund investments are market-linked, so their value can rise or fall and returns are not guaranteed.
What should an organisation consider before investing its corpus?
The organisation should first consider when the money may be needed and whether it must remain readily accessible. It should then assess the permitted investment options, market risk, liquidity, diversification, costs, and applicable tax or regulatory requirements. The investment should support the purpose of the corpus rather than being selected only because of its past performance.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.