






Health insurance goes beyond hospitalization—it covers OPD visits, medicines, ambulance charges, preventive checkups, and even alternative treatments, giving you all-around financial security.

Check health insurance plans with comprehensive coverage
Get Quote
Health plans from leading insurers | Comprehensive coverage | Offers multiple optional add-ons to enhance coverage
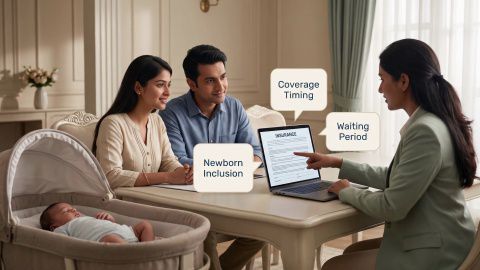
Newborn Health Insurance Coverage, Benefits & Plans
In summary
Maternity health insurance helps manage the medical expenses associated with pregnancy, childbirth and newborn care. Understanding waiting periods, coverage limits and available benefits can help families plan their finances and choose suitable health insurance coverage before conception.
- The reality of maternity waiting periods: Standard retail health insurance policies enforce a statutory waiting period of twelve to thirty-six months for maternity benefits to mitigate anti-selection risks. Source: Insurance Regulatory and Development Authority of India
- Zero waiting period avenues: True Day-1 maternity coverage without waiting periods is predominantly available through employer-sponsored Group Medical Cover (GMC) schemes or specialised corporate health policies.
- Innovative reduced-waiting riders: Leading partner insurers on Bajaj Finance offer modern individual policies featuring truncated 9-month or 12-month waiting period riders upon payment of additional premium loading.
- Comprehensive delivery and newborn protection: Plans cover normal delivery, planned or emergency caesarean section, pre- and post-natal diagnostic scans, and immediate newborn vaccination and care for 90 days. Source: General Insurance Council
- Proactive policy planning is essential: Securing coverage before conception ensures that waiting periods are completed comfortably, guaranteeing 100 percent cashless delivery in private multi-speciality hospitals.
Planning maternity coverage early can help you prepare for delivery expenses and understand the benefits available for newborn care. Explore health insurance plans through Bajaj Finance and check premiums to compare available options and find coverage that suits your needs.
What is maternity insurance?
Maternity insurance is a specialised medical insurance benefit—offered either as an embedded component within a comprehensive family floater policy or as an optional rider—designed to indemnify the substantial costs associated with pregnancy, childbirth, and early neonatal care.
In modern private healthcare across Indian metros, maternity care represents a significant financial commitment. A routine uncomplicated normal delivery in a premier private hospital routinely ranges between Rs. 60,000 and Rs. 1,20,000, while a planned or emergency caesarean section (C-section) frequently exceeds Rs. 1,50,000 to Rs. 2,50,000. If maternal complications (such as pre-eclampsia or post-partum haemorrhage) or neonatal complications arise requiring intensive care (NICU), hospital invoices can rapidly escalate into several lakhs of rupees.
A high-grade maternity health policy secured through the Bajaj Finance digital insurance marketplace covers inpatient hospitalisation, surgeon fees, anaesthetist charges, operation theatre tariffs, pre-natal consultations, and immediate medical care for the newborn child, providing complete financial security during this transformative milestone.
Did you know?
Nearly 30 percent of urban deliveries in private Indian hospitals involve caesarean section surgeries, which cost approximately 60 to 100 percent more than standard natural vaginal births.
Pro tip
Why is the waiting period for pregnancy insurance important?
The concept of a waiting period in maternity health insurance exists primarily to manage the fundamental insurance underwriting principle of risk pooling and prevent moral hazard or anti-selection.
Unlike unexpected medical events—such as acute appendicitis, heart attacks, or accidental fractures—pregnancy is largely a planned biological event. If insurers allowed individuals to purchase a retail policy after becoming pregnant and immediately claim delivery expenses, healthy policyholders who are not planning pregnancy would bear the cost, leading to unsustainable premium spikes across the entire market.
To maintain affordable premium structures for all consumers, the Insurance Regulatory and Development Authority of India (IRDAI) allows insurers to establish statutory specific waiting periods Source: IRDAI. During this designated period, policyholders must maintain continuous, unbroken coverage before maternity-related claims become admissible. Understanding this mechanism underscores why securing coverage early—ideally upon marriage or before conception—is paramount.
What is the waiting period for maternity insurance coverage?
Maternity waiting periods vary considerably depending on the category of health insurance policy selected:
| Insurance policy category | Standard maternity waiting period | Primary underwriting mechanism | Applicability on Bajaj Finance |
| Standard individual / family floater | 24 to 36 months | Standard statutory retail underwriting; requires 2 to 3 consecutive policy renewals | Available across all major partner health insurance policies |
| Specialised low-waiting retail plans | 9 to 12 months | Premium-loaded maternal care plans designed for couples planning childbirth within a year | Transparent multi-insurer comparison with instant digital issuance |
| Employer group medical cover (GMC) | 0 days (Day-1 coverage) | Employer-sponsored corporate policy where risk is pooled across hundreds of employees | Immediate Day-1 delivery coverage with zero waiting period |
| Retail policies with waiting reduction rider | 12 to 24 months | Optional rider reducing standard 36-month waiting period upon upfront payment | Configurable add-on feature on selected partner health plans |
To explore tailored plan configurations and calculate exact annual premiums, couples can explore plans on Bajaj Finance within minutes.
Popular plans for you
Maternity insurance plans with no waiting period
While standard retail health policies typically mandate waiting periods, couples can leverage specific, proven structural pathways to secure zero-waiting-period or immediate maternity protection:
- Employer-sponsored group health schemes (corporate GMC): This represents the most widespread and effective route to zero-waiting maternity cover in India. Corporate policies negotiate customized group terms with insurers, waiving all pre-existing conditions and maternity waiting periods from Day 1 of employee onboarding.
- Corporate top-up on existing group covers: If your employer provides a basic group health policy with Day-1 maternity but caps the benefit at Rs. 50,000, you can purchase a super top-up policy on Bajaj Finance to expand catastrophic coverage for maternal and neonatal complications.
- Portability from corporate to retail policies: Under IRDAI portability regulations, employees leaving corporate jobs can port their accrued group insurance tenure into an individual retail policy, retaining credit for years served and eliminating retail waiting periods.
- Accelerated 9-Month waiting period retail riders: Certain progressive health insurers on Bajaj Finance offer retail plans with shortened 9-month waiting periods, allowing newly married couples who purchase the policy immediately prior to conception to be fully covered by the time delivery occurs.
Quick fact:
An already pregnant woman cannot purchase an individual retail health insurance policy with zero waiting period to cover her ongoing pregnancy; any policy purchased during an active pregnancy will treat that pregnancy as a pre-existing condition excluded from immediate claims.
What is covered under maternity health insurance plans?
A comprehensive maternity health policy secured through Bajaj Finance provides end-to-end clinical protection:
- Normal and caesarean delivery expenses: Full settlement of private hospital room rent, nursing charges, obstetrician fees, anaesthetist fees, and surgical theatre expenses.
- Pre-natal and post-natal diagnostic costs: Reimbursement for routine blood tests, ultrasound scans, anomaly scans, and physician consultations incurred up to 30 to 60 days before delivery and up to 60 days after discharge.
- Management of obstetric complications: Unrestricted coverage for emergency hospitalisation resulting from gestational diabetes, pre-eclampsia, ectopic pregnancy, or post-partum haemorrhage.
- Immediate newborn baby cover: Automatic coverage for the newborn infant from Day 1 up to 90 days under the mother’s policy, covering routine checks, congenital disorder evaluations, and NICU admissions.
- Newborn vaccination coverage: Many comprehensive policies include financial allowances for essential statutory childhood immunisations during the first year of life.
Common exclusions in maternity insurance plans
Understanding contractual exclusions prevents unexpected financial surprises and ensures realistic claim expectations in accordance with General Insurance Council guidelines Source: GIC:
- Deliveries occurring during the waiting period: Any delivery occurring before the completion of the policy’s designated waiting period (e.g., 9, 12, or 24 months) will be repudiated.
- Voluntary medical termination of pregnancy (MTP): Non-therapeutic or voluntary terminations of pregnancy are excluded unless certified by an obstetrician as medically necessary to save the mother’s life.
- In vitro fertilisation (IVF) and infertility treatments: Assisted reproductive technologies, fertility investigations, and hormone priming are excluded unless explicitly protected under a specialised fertility add-on rider.
- Ectopic pregnancies in base indemnity: While ectopic pregnancy surgery is covered as an emergency life-saving procedure under general health insurance, it is not deducted from maternity sub-limits.
- Non-medical hospital consumables: Disposable maternity pads, breast pump equipment, and personal comfort items unless covered via a consumable protection rider.
Did you know?
Health insurance premiums paid for policies with maternity benefits qualify for personal income tax deductions up to Rs. 25,000 for self and family, plus up to Rs. 50,000 for senior citizen parents under Section 80D.
How to choose the best maternity health insurance plan
Selecting the optimal maternity health insurance plan requires evaluating several critical contractual and clinical parameters:
- Examine maternity financial sub-limits: Many basic health policies impose low sub-limits on delivery (e.g., capping normal delivery at Rs. 40,000 and C-section at Rs. 60,000). Prioritise comprehensive plans on Bajaj Finance that offer higher limits of Rs. 1,00,000 to Rs. 2,00,000 or zero sub-limits up to the sum insured.
- Verify room rent category eligibility: Settle only for policies offering single private room occupancy with zero room rent capping, preventing proportional deduction penalties across surgical and nursing invoices.
- Assess newborn and NICU coverage: Ensure the policy covers newborn intensive care unit (NICU) hospitalisation from Day 1, which represents the single largest financial exposure in neonatal medicine.
- Confirm cashless maternity hospital networks: Verify that leading private maternity hospitals and boutique birthing centres in your city are active network partners on the National Health Claims Exchange Source: NHA.
- Opt for automatic restoration of sum insured: Select policies featuring 100 percent automatic restoration to replenish the sum insured if exhausted during maternal hospitalisation.
Whether looking at family health insurance or comprehensive individual health insurance, Bajaj Finance simplifies comparing coverage features side by side.
Practical scenario: How proactive maternity planning saved a young family from high private hospital bills
Sneha Kapoor, a 29-year-old financial analyst residing in Gurugram, got married and planned to start a family within the next two years. Aware that private hospital deliveries in Gurugram routinely exceed Rs. 1,50,000 and that retail policies require waiting periods, Sneha evaluated plans on Bajaj Finance and purchased a comprehensive family health cover of Rs. 15 lakh with zero room rent capping and an attached maternity rider with a 12-month waiting period.
Fourteen months later, Sneha conceived, and at thirty-eight weeks of gestation, her obstetrician recommended an emergency caesarean section due to foetal distress and umbilical cord presentation. Sneha was admitted to a premier private multi-speciality maternity network hospital in Gurugram, where she underwent an emergency C-section and spent four days recovering in a private suite.
The hospitalisation invoice for the delivery, surgical team fees, anaesthesia, and four days of private room stay totalled Rs. 1,85,000. Because Sneha had already completed her 12-month waiting period before delivery, the hospital insurance desk processed the claim cashlessly, settling Rs. 1,72,000 directly within three hours, leaving Sneha with an out-of-pocket payment of only Rs. 13,000 for non-medical items. Furthermore, the newborn was covered under the policy from Day 1, protecting the family’s savings completely.
Quick fact:
Neonatal intensive care (NICU) in private metro hospitals can cost between Rs. 15,000 and Rs. 35,000 per day; ensuring your maternity policy covers the newborn from Day 1 is the most vital safety feature for young parents.
Show More
Show Less
Do's and don'ts: Best practices in maternity health insurance
| Do | Why it matters | Don’t | Risk to avoid |
| Purchase maternity health insurance at marriage or well before conception occurs. | Ensures that statutory 9 to 24 month waiting periods are fully served before childbirth occurs. | Wait until pregnancy is confirmed before shopping for retail maternity insurance. | Disqualification and complete claim rejection because pregnancy is treated as an active pre-existing condition. |
| Insist on a policy offering single private room occupancy with zero room rent capping. | Eliminates proportional deductions on ICU, surgeon fees, and nursing charges during hospitalisation. | Settle for entry-level policies with 1% room rent ceilings to save on annual premiums. | Substantial out-of-pocket penalties deducted across all surgical and hospital bill line items. |
| Verify that the policy explicitly covers the newborn baby from Day 1 of life. | Guarantees instant financial protection against expensive neonatal incubator or NICU care. | Assume all maternity policies automatically include full neonatal intensive care coverage. | Out-of-pocket medical bills amounting to several lakhs of rupees for premature infant care. |
| Check the maternity financial sub-limit in your policy schedule carefully. | Ensures that delivery expense limits align with actual room and surgical charges at your chosen hospital. | Overlook delivery sub-limits assuming the entire base sum insured applies to normal delivery. | Unexpected out-of-pocket expenses when hospital bills exceed capped maternity sub-limits. |
*Source: National Health Authority and official scheme guidelines.*
Show More
Show Less
What to do next: action roadmap
Follow this structured five-phase roadmap to secure optimal maternity healthcare protection:
- Phase 1: Assess family planning timeline (days 1 to 2): Determine your anticipated pregnancy timeline, review corporate benefits, and identify whether a 9-month or 24-month retail plan is needed.
- Phase 2: Compare maternity-friendly policies on Bajaj Finance (days 3 to 4): Review partner insurer offerings featuring low waiting periods, high delivery sub-limits, and zero room rent capping.
- Phase 3: Select coverage and attach newborn baby riders (days 5 to 6): Choose a baseline sum insured of Rs. 15 lakh to Rs. 20 lakh and ensure newborn coverage from Day 1 is activated.
- Phase 4: Complete digital onboarding with complete medical history (day 7): Complete the online proposal form transparently on Bajaj Finance, upload KYC documents, and secure instant digital policy issuance.
- Phase 5: Secure preventative health insurance via Bajaj Finance (ongoing): Serve statutory waiting periods smoothly, track annual preventative health checks, and maintain uninterrupted lifelong renewable coverage.
Sources and references
| Source / reference authority | Document / research topic | Relevant insights and context | Publication month and year |
| Insurance Regulatory and Development Authority of India (IRDAI) | Master circular on operations and health insurance business | Specific-illness waiting periods, maternity benefit norms, and claim settlement SLAs | October 2026 |
| General Insurance Council (GIC) | Standard health insurance terms and network hospital cashless protocols | Cashless hospitalisation standards and newborn coverage underwriting norms | October 2026 |
| National Health Authority (NHA) | Digital health infrastructure and National Health Claims Exchange standards | Seamless cashless hospitalisation exchange protocols for maternity patients | October 2026 |
Data last updated as of October 2026.
Glossary of maternity health insurance terms
| Technical term | Definition and regulatory context |
| Specific waiting period | A statutory timeframe during which designated medical conditions (such as maternity or joint replacement) are excluded from coverage. |
| Group medical cover (GMC) | An employer-sponsored health insurance policy covering employees and dependants, often featuring Day-1 maternity benefits. |
| Maternity sub-limit | A contractual cap that restricts the maximum financial claim admissible for normal or caesarean childbirth. |
| Cashless pre-authorisation | Written approval granted by an insurer or TPA to a network hospital confirming coverage eligibility and approved tariffs prior to hospital admission. |
| Proportionate deduction penalty | Financial deduction applied across all hospital bill items when a policyholder selects a hospital room exceeding their policy's daily room rent ceiling. |
| Portability | The legal right granted by IRDAI to transfer health insurance coverage from one insurer to another without losing accrued waiting period credits. |
Health Insurance in different cities

Health Insurance in Bangalore

Health Insurance in Jaipur

Health Insurance in Pune

Health Insurance in Mumbai

Health Insurance in Kerala
Compare types of Health Insurance Plans
Tax-savings plans for you
What our customer say about us
+ Customers
Play Store Rating
Reviews
Arjun Mehta
13 Jul 2025
I opted for the Health Infinity plan for my parents. The digital onboarding was incredibly fast with no medical tests required since they are under 50. We had a minor daycare procedure last month, and the cashless approval came through in less than 2 hours. Very impressed with the efficiency.
Priya Sharma
28 Feb 2025
The Bajaj Finance Health app is a lifesaver. I use it for my regular OPD consultations and medicine orders. The 10% discount on pharmacy bills and the easy reimbursement for doctor visits make it much more than just a 'hospitalization' policy. It’s daily health support.
Sneha Kapoor
15 Mar 2025
Switched my family floater to Bajaj General this year. The network of hospitals in my city (Pune) is excellent. The only downside was a slight delay in getting my physical card, but the digital copy on the app works everywhere. The 'Wellness Rewards' for hitting step goals is a cool touch!
Conclusion
Welcoming a new child into the family is one of life’s most joyous and memorable milestones. However, the rising costs of private maternity hospitalisation, diagnostic evaluations, and specialised neonatal intensive care require thoughtful, proactive financial planning.
While retail maternity insurance policies with absolute zero waiting periods are rare outside corporate group medical covers, modern policies with accelerated 9-month and 12-month waiting periods offer an accessible, powerful solution for newly married couples. Sourcing a high-coverage family health insurance policy through the Bajaj Finance digital insurance marketplace ensures that your waiting periods are completed early, delivery costs are covered cashlessly, and your newborn is protected from Day 1.
Take charge of your family’s future today: explore quotes, tailor deductibles, and secure comprehensive coverage: explore plans on Bajaj Finance to welcome your baby with complete financial peace of mind. Whether exploring health insurance, evaluating family health insurance plans, or securing individual health insurance, Bajaj Finance simplifies coverage discovery with transparent quotes and instant digital onboarding.
Top health insurance plans
Explore and stay informed
Can you buy health insurance on EMI
Why buy health insurance
Health Insurance for family
Health Insurance Claim settlement ratio
Health Insurance waiting period
Importance of health insurance
Health Insurance for Senior Citizens
Health Insurance tax benefits
Health Insurance for parents
Health Insurance premium calculator
Health Insurance for Other Diseases

Antral Gastritis

Hepatomegaly Symptoms Causes & Treatment

Blood Pressure Range

PCOS Causes and Symptoms

Health insurance for Obesity
Frequently asked questions
Maternity waiting periods and immediate coverage
Can I get maternity insurance with zero waiting period in India?
Zero waiting period for maternity is predominantly available through employer-sponsored Group Medical Cover (GMC) policies, which cover delivery from Day 1. Individual retail policies mandate a waiting period of 9 to 36 months, which can be shortened using specific low-waiting riders on Bajaj Finance.
Can I buy maternity insurance if I am already pregnant?
You can purchase health insurance while pregnant, but the ongoing pregnancy and delivery will be treated as an existing condition and will not be covered for the current childbirth. However, future pregnancies will be covered once the policy waiting period is served.
What is the shortest waiting period available for retail maternity insurance?
The shortest waiting period for retail maternity insurance available through partner insurers on Bajaj Finance is typically 9 to 12 months, designed specifically for newly married couples planning childbirth after policy inception.
Does maternity insurance cover both normal and caesarean deliveries?
Yes. Comprehensive maternity health insurance covers both normal vaginal deliveries and planned or emergency caesarean sections (C-sections), including surgeon fees, anaesthetist charges, operation theatre costs, and private room hospitalisation.
Is the newborn baby covered immediately under maternity insurance?
Yes. High-grade maternity plans available on Bajaj Finance provide automatic coverage for the newborn infant from Day 1 up to 90 days under the mother’s policy, covering routine paediatric evaluations and neonatal intensive care (NICU) admissions.
Does maternity insurance cover pre-natal and post-natal expenses?
Yes. Most maternity policies cover diagnostic ultrasounds, blood tests, and doctor consultations incurred up to 30 to 60 days before delivery and up to 60 days post-discharge as pre- and post-hospitalisation expenses.
How do I file a cashless claim for planned delivery at a network hospital?
For a planned delivery, submit your health insurance e-card, valid photo ID, and treating obstetrician’s admission note to the network hospital insurance desk at least 48 to 72 hours prior to admission to obtain cashless pre-authorisation.
What is a maternity sub-limit in health insurance?
A maternity sub-limit is a contractual financial cap specified in your policy schedule that limits the maximum amount payable for delivery (for example, capping normal delivery at Rs. 50,000 and C-section at Rs. 75,000), regardless of your total base sum insured.
Can I port my corporate health insurance to retain maternity waiting period credits?
Yes. Under IRDAI portability regulations, an employee leaving a company can port their corporate group coverage into an individual retail policy with the same insurer without losing credit for the years served under the corporate policy.
Articles and Insights
Disclaimer
*T&C Apply - Bajaj Finance Limited (‘BFL’) is a registered corporate agent of third party insurance products of Bajaj Allianz Life Insurance Company Limited, HDFC Life Insurance Company Limited, Life Insurance Corporation of India (LIC), Bajaj Allianz General Insurance Company Limited, SBI General Insurance Company Limited, ACKO General Insurance Company Limited, HDFC ERGO General Insurance Company, TATA AIG General Insurance Company Limited, ICICI Lombard General Insurance Company Limited, New India Assurance Limited, Chola MS General Insurance Company Limited, Zurich Kotak General Insurance Co. Limited , Star Health & Allied Insurance Co. Limited, Care Health Insurance Company Limited, Niva Bupa Health Insurance Company Limited , Aditya Birla Health Insurance Company Limited and Manipal Cigna Health Insurance Company Limited under the IRDAI composite CA registration number CA0101. Please note that, BFL does not underwrite the risk or act as an insurer. Your purchase of an insurance product is purely on a voluntary basis after your exercise of an independent due diligence on the suitability, viability of any insurance product. Any decision to purchase insurance product is solely at your own risk and responsibility and BFL shall not be liable for any loss or damage that any person may suffer, whether directly or indirectly. Please refer insurer's website for Policy Wordings. For more details on risk factors, terms and conditions and exclusions please read the product sales brochure carefully before concluding a sale. Tax benefits applicable if any, will be as per the prevailing tax laws. Tax laws are subject to change. Tax laws are subject to change. BFL does NOT provide Tax/Investment advisory services. Please consult your advisors before proceeding to purchase an insurance product. Visitors are hereby informed that their information submitted on the website may also be shared with insurers. BFL is also a distributor of other third-party products from Assistance Services providers such as CPP Assistance Services Pvt. Ltd., Bajaj Finance Health Ltd. etc. All product information such as premium, benefits, exclusions, sum insured, value added services, etc. are authentic and solely based on the information received from the respective insurance company or the respective Assistance service provider company.
Note – While we have made all efforts and taken utmost care in gathering precise information about the products, features, benefits, etc. However, BFL cannot be held liable for any direct or indirect damage/loss. We request our customers to conduct their research about these products and refer to the respective product’s sales brochures before concluding their sale.