








₹ 2 lakh – ₹ 80 lakh
Check your pre-approved offer and other benefits
Enter mobile and OTP | Check offer | Know your exact loan terms
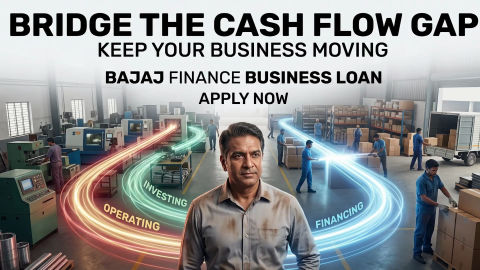
Cash Flow Statement Explained
-
In summary
A cash flow statement tracks cash and cash equivalents entering and leaving a business. It complements the income statement and balance sheet by focusing on cash movement.
- It classifies cash flows into operating, investing, and financing activities.
- Operating activities relate to the principal revenue-producing activities of the business.
- Investing activities generally cover purchases and sales of long-term assets and investments.
- Financing activities reflect changes in equity and borrowings, including raising and repaying finance.
- Operating cash flow can be presented using the direct or indirect method, subject to the applicable reporting framework.
- The statement helps analyse liquidity, cash generation, investment spending, financing, and changes in cash and cash equivalents.
- A positive net cash flow does not automatically mean the business is profitable, while a negative cash flow does not necessarily indicate poor performance.
Read it alongside the income statement and balance sheet for context on profitability, liquidity, investment, and financing.
What is a cash flow statement?
-
A cash flow statement is a financial statement that reports historical changes in cash and cash equivalents during a reporting period. It explains how cash was generated and used through operating, investing, and financing activities.
Unlike the income statement, which can include non-cash items and accrual-based income and expenses, the cash flow statement focuses on cash movements. It also helps explain why the opening cash balance changed into the closing cash balance.
Ind AS 7, Statement of Cash Flows, requires entities within its scope to present a statement of cash flows as an integral part of their financial statements for each period presented. The applicable reporting framework depends on the entity and its reporting requirements.
Why is a cash flow statement important?
-
A cash flow statement helps you assess whether a business generates enough cash from its activities to meet obligations, fund investment, and manage financing requirements.
- Liquidity assessment: It shows the movement in cash and cash equivalents and helps identify periods of cash surplus or shortage.
- Operating strength: Operating cash flow indicates how much cash the principal business activities generate.
- Investment planning: Investing cash flows show spending on assets and other investments that may support future income.
- Financing analysis: Financing cash flows show how the business raises and repays capital and borrowings.
- Financial planning: Historical cash movements can support cash budgeting and future funding decisions.
Cash flow information is most useful when read with the other financial statements rather than in isolation.
What are the three types of cash flow?
Cash flows are classified into operating, investing, and financing activities. Ind AS 7 uses these three categories to show how different business decisions affect cash and cash equivalents.
| Activity | What it covers | Common examples |
| Operating activities | Cash flows from the principal revenue-producing activities and other activities that are not investing or financing. | Cash received from customers; payments to suppliers and employees; operating taxes. |
| Investing activities | Cash flows relating to acquisition and disposal of long-term assets and investments that are not cash equivalents. | Purchase or sale of property, plant and equipment; acquisition or disposal of certain investments. |
| Financing activities | Cash flows that change the size or composition of contributed equity and borrowings. | Proceeds from issuing shares or borrowing; repayment of borrowings; certain dividend payments. |


What is cash flow from operating activities?What is cash flow from operating activities?
Cash flow from operating activities reflects cash generated or used by the principal revenue-producing activities of a business. It can include cash receipts from sales or services and cash payments to suppliers, employees, and for operating expenses.
Operating cash flow is often analysed closely because it indicates whether the core business is generating cash without relying primarily on asset sales or new financing. However, the appropriate classification of individual items depends on the applicable accounting framework.
Under the indirect method, operating cash flow starts with profit or loss and adjusts for non-cash items and relevant changes in operating assets and liabilities. Under the direct method, major classes of gross cash receipts and payments are presented.
What is cash flow from investing activities?
Cash flow from investing activities captures cash paid or received for long-term assets and certain investments. It helps show how much cash a business is deploying to build or change its productive capacity.
- Purchase of property, plant and equipment is generally an investing cash outflow.
- Proceeds from selling property, plant and equipment are generally investing cash inflows.
- Payments to acquire certain investments can be investing outflows.
- Receipts from disposing of qualifying investments can be investing inflows.
A negative investing cash flow is not automatically a weakness. Significant investing outflows may occur when a business is buying equipment, technology, or other assets intended to generate future income.
What is cash flow from financing activities?
Cash flow from financing activities reflects transactions that change the size or composition of contributed equity and borrowings. It helps explain how a business funds its operations and investments.
- Proceeds from issuing shares can create a financing cash inflow.
- Borrowing can create a financing cash inflow.
- Repayment of borrowings is generally a financing cash outflow.
- Certain dividend payments are presented as financing cash flows under the applicable framework.
Financing cash flow should be interpreted with the business's debt, equity, repayment obligations, and investing plans. A financing inflow may increase available cash while also creating future repayment or return obligations.
How do you prepare a cash flow statement?
Preparing a cash flow statement requires financial information from the income statement, balance sheet, accounting records, and bank records. A practical process is:
- Define the reporting period and identify the opening cash and cash equivalents.
- Collect the income statement, balance sheet, relevant ledgers, and bank information.
- Identify cash receipts and payments and exclude movements that do not involve cash or cash equivalents.
- Classify the relevant cash flows into operating, investing, and financing activities.
- Choose the direct or indirect method for operating cash flows where the applicable framework permits the choice.
- Calculate the net change in cash and cash equivalents for the period.
- Reconcile the closing cash and cash equivalents with the corresponding financial statement balance.
- Review unusual movements and investigate material differences before finalising the statement.
Ind AS 7 also requires disclosure of the components of cash and cash equivalents and a reconciliation between the amounts in the cash flow statement and the corresponding amounts in the balance sheet.
What is the direct method of cash flow statement?
The direct method presents major classes of gross cash receipts and gross cash payments from operating activities. For example, it can show cash collected from customers and cash paid to suppliers and employees.
The method gives a direct view of operating cash receipts and payments, but it can require detailed cash transaction information. Accounting Standard 3 describes the direct and indirect methods as alternatives for reporting operating cash flows, while noting the usefulness of the direct method for estimating future cash flows.
| Item | Direct method treatment |
| Customer receipts | Show major cash receipts from customers. |
| Supplier payments | Show major cash payments for goods and services. |
| Employee payments | Show cash paid to employees where separately presented. |
| Operating taxes | Present applicable cash tax payments according to the reporting framework. |
What is the indirect method of cash flow statement?
The indirect method begins with profit or loss and adjusts it for non-cash items, changes in operating assets and liabilities, and items whose cash effects belong to investing or financing activities.
- Add back relevant non-cash expenses such as depreciation, subject to the applicable reporting framework.
- Adjust for changes in inventories, operating receivables, and operating payables.
- Remove or adjust items whose cash effects are investing or financing cash flows.
- Arrive at net cash flow from operating activities.
The indirect method does not mean that non-cash items are treated as cash. The adjustments convert an accrual-based profit figure into operating cash flow.
How do you read a cash flow statement?
Read the three activity sections together and then reconcile them with the opening and closing cash balances. The aim is to understand where cash came from, where it went, and whether the pattern is sustainable.
| Area to review | What to ask |
| Operating cash flow | Is the core business consistently generating cash? |
| Investing cash flow | Is cash being used for productive assets or received from asset disposals? |
| Financing cash flow | Is the business raising finance, repaying debt, distributing funds, or changing its capital structure? |
| Net change in cash | Why did the cash balance increase or decrease during the period? |
| Closing cash and equivalents | Does the reported closing balance reconcile with the financial statements? |
Avoid judging one year's cash flow without context. Compare multiple periods and investigate material changes in receivables, inventory, payables, capital expenditure, borrowing, and other significant cash movements.
What does a cash flow statement example look like?
Consider ABC Traders for a simple illustration. During a financial year, the business receives Rs. 10 lakh from customers and pays Rs. 6 lakh for salaries, rent, suppliers, and other operating costs. Its net operating cash flow is Rs. 4 lakh.
ABC Traders then spends Rs. 1 lakh on a delivery vehicle. This is an investing cash outflow. It also repays Rs. 50,000 of borrowing, creating a financing cash
outflow.
| Cash flow category | Amount | Effect |
| Operating activities | Rs. 4 lakh | Cash generated from core operations |
| Investing activities | Rs. 1 lakh outflow | Purchase of a long-term asset |
| Financing activities | Rs. 50,000 outflow | Repayment of borrowing |
| Net change in cash | Rs. 2.5 lakh | Increase in cash for the period |
This simplified example shows why a business can have positive operating cash flow while also spending cash on expansion and repaying finance. The closing cash balance must still be reconciled with the opening balance and other cash-equivalent movements.
What is the difference between cash flow and fund flow?
A cash flow statement focuses on movements in cash and cash equivalents. A fund flow statement traditionally analyses sources and uses of funds and changes in working capital. The two statements therefore answer different questions.
| Basis | Cash flow statement | Fund flow statement |
| Main focus | Cash and cash equivalents | Sources and uses of funds and working-capital movement |
| Classification | Operating, investing, and financing activities | Sources and applications of funds |
| Primary use | Liquidity and cash management | Analysis of changes in financial position and working capital |
| Cash emphasis | Directly tracks cash and cash equivalents | Broader funds concept rather than only cash |
For current financial reporting, use the applicable accounting framework and statutory requirements rather than assuming that a traditional fund flow statement has the same reporting status as a cash flow statement.
Check your pre-approved business loan offer
What are the advantages of a cash flow statement?
- Liquidity visibility: It shows how cash and cash equivalents change during the period.
- Cash-generation analysis: It helps separate cash generated by operations from cash raised through financing.
- Debt management: It helps track borrowing and repayment cash flows.
- Planning support: Historical cash patterns can support cash budgeting and funding decisions.
These advantages are strongest when the statement is analysed alongside profitability, assets, liabilities, working capital, and business plans.
What are the limitations of a cash flow statement?
- It does not measure profitability on its own because profit and cash flow can differ.
- It is historical and therefore cannot by itself show future cash availability.
- A negative cash flow can reflect investment in growth rather than weak operations.
- A positive cash flow can result from borrowing or asset sales rather than stronger operating performance.
- It does not replace the balance sheet or income statement when assessing overall financial position.
For example, a business can report profit while customers have not yet paid their invoices. Conversely, selling an asset can generate cash without improving recurring operating performance.
How does cash flow differ from profit?
Profit and cash flow measure different aspects of business performance. Profit is determined under the applicable accounting framework and can include accrued income, accrued expenses, depreciation, and other non-cash items. Cash flow tracks actual cash and cash-equivalent movements.
| Point | Profit | Cash flow |
| Primary focus | Income and expenses recognised for the period | Cash and cash equivalents received and paid |
| Non-cash items | Can affect reported profit | Do not represent cash movement |
| Credit sales | Can increase revenue before cash is collected | Cash flow records the receipt when cash is collected |
| Depreciation | Reduces accounting profit | Is a non-cash expense and is adjusted in the indirect method |
| Liquidity | Does not directly show available cash | Directly analyses cash movement and closing cash position |
What should you check before using a cash flow statement?
Before drawing a conclusion from a cash flow statement, check the reporting period, accounting framework, classification of material items, and reconciliation with the balance sheet.
- Confirm the opening and closing cash and cash-equivalent balances.
- Check whether operating, investing, and financing classifications are consistent with the applicable framework.
- Review major movements in receivables, inventory, payables, capital expenditure, and borrowings.
- Compare operating cash flow with reported profit and investigate significant differences.
- Review cash flows across more than one reporting period where available.
- Consider the notes and accounting policies for material or unusual transactions.
How can a business use cash flow analysis in practice?
Consider Rohan, a 35-year-old entrepreneur in Pune who operates an established wholesale distribution business. His income statement shows a profit, but his cash balance has fallen because customers are taking longer to pay and the business has increased inventory before a seasonal sales period.
- Rohan reviews operating cash flow and identifies higher receivables and inventory as key cash uses.
- He reviews investing cash flow to separate routine asset purchases from larger expansion spending.
- He checks financing cash flow to understand existing borrowing and scheduled repayments.
- He compares the cash position with upcoming supplier payments, employee costs, taxes, and other obligations.
- He uses the combined picture to decide whether to tighten collections, reduce inventory, defer discretionary spending, or evaluate additional funding.
The example shows why profit alone may not reveal a short-term cash requirement. Cash flow analysis helps connect accounting results with the timing of actual cash movements.
What can a cash flow gap mean for a business?
A business can generate sales and report a profit while still facing a temporary cash gap when customer payments are delayed, inventory rises, or major operating and expansion expenses fall due together. Without sufficient working capital, these timing differences can put pressure on routine payments and planned business activities.
For an established business that meets the applicable eligibility criteria, a Bajaj Finance Business Loan can help fund working capital, equipment, expansion, or digitisation. Loan amounts range from Rs. 2 lakh to Rs. 80 lakh, with repayment tenures from 12 months to 96 months, subject to business loan eligibility and applicable terms. Reviewing your cash flow statement can help you understand the funding requirement before evaluating whether a Bajaj Finance Business Loan suits that requirement.


Select loan by amount
Applicable fees and charges on our business loan

Loans for business needs
Get business loan for your needs
Women Business Loan
Get Women Business Loan upto 80 Lakh
Medical Store Business Loan
Get Medical Store Business Loan upto 80 Lakh
Manufacturer Business Loan
Get Manufacturer Business Loan upto 80 Lakh
Business loan in different cities

Business loan in bangalore

Business loan in mumbai

Business loan in pune

Business loan in Jaipur

Business loan in Kerala
Business loan for different budgets

2 lakh business loan
3 lakh business loan
5 lakh business loan
10 lakh business loan

15 lakh business loan
20 lakh business loan
25 lakh business loan
30 lakh business loan
50 lakh business loan
Types of business loan
Unsecured Business Loan
Secured Business Loan
Term Loan
Cash Credit
Working Capital Loan
Machinery Loan
Line of Credit
Micro Loan
Merchant cash Loan
Frequently asked questions
Overview
What is a cash flow statement in simple words?
A cash flow statement shows how cash and cash equivalents moved into and out of a business during a reporting period. It groups those movements into operating, investing, and financing activities. It differs from the income statement because it focuses on cash movement rather than profit or loss alone. It helps you understand whether the business is generating cash from operations, spending cash on assets, or raising and repaying finance.
What are the three types of cash flow statements?
A cash flow statement classifies cash movements into three activity categories: operating, investing, and financing. Operating activities cover the principal revenue-producing activities. Investing activities generally cover purchases and sales of long-term assets and qualifying investments. Financing activities cover changes in contributed equity and borrowings. These categories help you see how routine operations, investment decisions, and funding decisions affect cash and cash equivalents.
What is the difference between direct and indirect cash flow methods?
The direct method presents major classes of gross operating cash receipts and payments, such as cash received from customers and cash paid to suppliers. The indirect method starts with profit or loss and adjusts for non-cash items, changes in operating assets and liabilities, and items classified under investing or financing activities. Both methods are used to determine operating cash flow where the applicable accounting framework permits the relevant presentation.
Can a company have profit but negative cash flow?
Yes. A company can report accounting profit while experiencing negative cash flow, particularly when customers have not yet paid invoices, inventory has increased, or other cash payments have occurred before related cash receipts. Profit can include accrual-based income and non-cash items, while the cash flow statement records cash movements. Therefore, reviewing both profit and cash flow provides a more complete view of business performance and liquidity.
Is negative cash flow always bad?
No. Negative cash flow needs context. A business may report negative investing cash flow because it is purchasing equipment, technology, or other assets for future growth. It may also have financing outflows because it is repaying debt. The key is to identify which activity caused the negative cash flow and whether operating cash generation, available reserves, or other funding sources can support the business's obligations and plans.
How do you calculate net cash flow?
Net cash flow for a period is determined by combining the net cash flows from operating, investing, and financing activities, after considering applicable cash and cash-equivalent movements. The result explains the change between the opening and closing cash and cash-equivalent balances, subject to the applicable reporting framework. The closing balance should reconcile with the corresponding balance reported in the financial statements.
Can a cash flow statement show whether a business is financially healthy?
It provides important information about liquidity and cash generation, but it cannot establish overall financial health by itself. A complete assessment should also consider the income statement, balance sheet, debt obligations, working capital, profitability, and business plans. For example, positive cash flow may result from new borrowing, while negative cash flow may reflect investment in productive assets. Context is therefore essential when interpreting the statement.
More articles
Manage cash flow during lean periods with business finance
Read More
Top 7 Government Business Loan Schemes in India (2026)
Read More

MSME Loan Scheme in 2025 - Types, Interest Rate, Eligibility, and How to Apply Online
Read More
MSME Loan vs MUDRA Loan: Key Differences and Eligibility
Read More
Disclaimer
Bajaj Finance Limited has the sole and absolute discretion, without assigning any reason to accept or reject any application. Terms and conditions apply*.