







An OTP will be sent to this number for verification

You may have a pre-approved offer
Enter required home loan amount
In summary
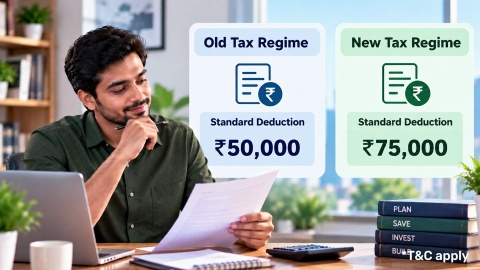
Standard Deduction- Know What It is and Its Benefits in 2025
Last updated: Sept 2026
Standard deduction is one of the few tax benefits available under both regimes, though at different amounts, which makes it worth understanding regardless of which regime you eventually choose.
- Old regime amount: Rs. 50,000, unchanged since FY 2019-20
- New regime amount: Rs. 75,000, effective FY 2024-25 onward
- Eligibility: salaried employees and pensioners only, not self-employed individuals or those with only business income
- No documentation required: applied automatically to eligible income, unlike deductions requiring receipts
Introduced in its current form in FY 2018-19, at Rs. 40,000, replacing separate transport and medical allowances
Standard deduction applies automatically if your income qualifies. There is nothing to claim or submit separately.
Why do the amounts differ by regime?
It was reintroduced in FY 2018-19 to simplify compliance for salaried employees, replacing a more complex set of separate allowances with one flat figure. The new regime's higher Rs. 75,000 amount, against the old regime's Rs. 50,000, is a deliberate policy design, intended to offset the loss of other deductions for salaried taxpayers with few remaining claims.
The amount you receive depends entirely on which regime you choose for the year, not on your income level or employer. The realistic comparison points for a salaried taxpayer are:
- Under the new regime, the amount is higher, but most other deductions (Section 80C, HRA, home loan interest) are unavailable
- Under the old regime, it is lower, but a wider range of deductions remain available if you have investments, rent, or a home loan
The right regime depends on your total eligible deductions under the old regime, compared against the new regime's higher flat amount and lower slab rates
This single figure rarely decides which regime suits you on its own. It is one input into a larger comparison.
Show more
Show less
Who is actually eligible for it?
Eligibility depends on income type, not income level, employer type, or employment tenure.
| Income type | Eligible |
|---|---|
| Salaried employee, any employer | Yes |
| Pension, government or private | Yes |
| Freelance or professional income | No |
| Business income (proprietorship, partnership) | No |
| Rental income | No |
Pension is treated as salary income for this purpose, so pensioners receive the same amount as salaried employees. Freelancers and business owners can instead deduct actual, documented business expenses against their income, which serves a related but different purpose.
Show more
Show less
How does it apply in a tax calculation?
Four steps place standard deduction correctly in the overall calculation sequence.
- Start with your gross salary or pension income for the financial year.
- Subtract the applicable amount: Rs. 50,000 under the old regime, or Rs. 75,000 under the new regime.
- Continue with any other eligible deductions (old regime only) to arrive at net taxable income.
Apply the relevant tax slabs to the resulting figure.
This deduction is subtracted before any other deduction in the sequence, which is why it lowers your net taxable income regardless of what other benefits you do or do not claim.
Show more
Show less
A worked example: comparing the two regime amounts
Consider Ashwin, a 34-year-old bank employee in Chennai with a gross salary of Rs. 11 lakh a year and a CIBIL Score of 752, comparing his net taxable income under each regime.
Formula used: Net taxable income = Gross salary − Standard deduction amount − Other eligible deductions (old regime only)
| Item | Old regime | New regime |
|---|---|---|
| Gross salary | Rs. 11,00,000 | Rs. 11,00,000 |
| Deduction amount | Rs. 50,000 | Rs. 75,000 |
| Other deductions (80C, home loan interest) | Rs. 2,50,000 | Not applicable |
| Net taxable income | Rs. 8,00,000 | Rs. 10,25,000 |
Despite the new regime's higher amount, Ashwin's net taxable income is lower under the old regime, because his Rs. 2.5 lakh in other deductions outweighs the Rs. 25,000 gap between the two figures.
Show more
Show less
Home loan for professionals
Financing a home while planning your regime choice with Bajaj Finance
| Loan feature | Detail |
|---|---|
| Interest rate | From 7.25% p.a.*, subject to credit assessment |
| Loan amount | Up to Rs. 15 crore* |
| Tenure | Up to 32 years |
If a home loan's interest deduction under Section 24(b) is part of your regime decision, factor it in alongside standard deduction before choosing. Approval timelines can extend where self-employed applicants' income documentation needs cross-verification, and minimum income thresholds for salaried applicants can differ by city. Check your home loan eligibility once your regime choice and net income are confirmed.
Show more
Show less
Frequently Asked Questions
Eligibility and amounts
Applying it correctly
Does it apply if I have both salary and freelance income?
Yes, but only to the salary portion. Standard deduction applies specifically to salary or pension income, so freelance or professional income in the same tax year is not covered by it. You would instead deduct actual, documented expenses against your freelance income separately, since a different rule governs that portion.
Why is the new regime's standard deduction higher than the old regime's?
This is a deliberate policy design. The new regime removes most other deductions, so a higher flat standard deduction partly compensates, which offsets the loss of the old regime's fuller deduction list for salaried taxpayers with few other claims to make. It is one of the levers used to make the new regime's overall numbers work for a typical salaried applicant.
Do I need to submit any proof to claim standard deduction?
No. Unlike deductions requiring receipts or investment proof, standard deduction applies automatically to eligible salary or pension income. There is no documentation to submit or claim form to file separately. Your employer's payroll system, and the pre-filled figures on the e-filing portal, apply it without any action needed from you.
Can I choose different regimes in different years to maximise my standard deduction and other benefits?
Salaried individuals can switch between regimes each financial year when filing, as a rule, subject to current rules on how often a change is permitted. Self-employed individuals face more restrictive switching rules, often limited to a single switch back to the old regime in their lifetime. Confirm the current year's specific switching rule before assuming you can alternate freely every year.
Home Loan in Different Cities

Home Loan in Mumbai

Home Loan in Ahmedabad

Home Loan in Bangalore

Home Loan in Chennai

Home Loan in Delhi

Home Loan in Hyderabad

Home Loan in Cochin

Home Loan in Noida

Home Loan in Pune
Home Loan for different budget
Check your pre-approved offer now
Our Calculators
What do our customers say about us
customers
Play Store rating
reviews
Amit Shiva
Reviewed on
Smooth and transparent home loan process. The interest rates were competitive, and documentation was minimal. The team guided me clearly at every step, making my first home purchase stress-free. Highly recommended for quick approvals.
Sandeep Kulkarni
Reviewed on
The loan disbursal was fast, and the customer support team was extremely patient with all my queries. Flexible EMIs helped me manage my monthly expenses easily. A great experience for salaried homebuyers.
Ritika Agarwal
Reviewed on
I had a great experience while transferring my existing home loan. The process was quick, and I saved significantly with the lower interest rate. Customer service was helpful throughout. Highly recommended for balance transfers.
Manoj Verghese
Reviewed on
Clear guidance, quick approval, and flexible repayment options made buying my new house easier than expected. The team handled everything professionally. Very satisfied and would definitely recommend their home loans
Find your nearest branch

More Articles
Watch our videos
Documents required to get a Bajaj Finserv Home Loan
Tips to increase your Home Loan eligibility
Things you need to know about pre-approved home loan
Things you need to know before applying for a Home Loan
How does Repo Rate affect your Home Loan
Download App
Now request money from your friends and family and make instant payments.
- Choose from personal, business, gold loans and more
- Pay utility bills, use UPI, get FASTag and more
- Buy over 1 million products on No Cost EMI
- Buy stocks, mutual funds and invest in FD
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (NBFC) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.