






780 CIBIL Score

780 CIBIL Score

Simple tips to improve CIBIL Score and secure better financial options. Check your eligibility for personal loan with your phone and OTP.

Rs. 40,000 - Rs. 55 lakh

You may be eligible for a pre-approved loan offer

Enter mobile number and OTP | Check free credit score


In summary


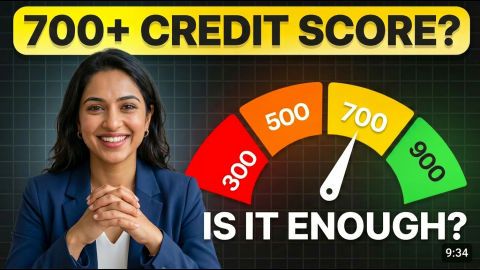
A 780 CIBIL Score falls within the 750–900 range on the 300–900 scale and generally indicates a strong credit profile. However, lenders also consider your repayment history, credit utilisation, existing loan obligations, income, and other eligibility factors before making a decision.


To maintain your 780 CIBIL Score:

  • Pay all EMIs and credit card dues on time
  • Keep credit card utilisation low
  • Avoid multiple credit applications within a short period

A CIBIL Score reflects how you have managed credit over time. Maintaining responsible repayment and borrowing habits can support your credit profile and may improve your access to loans and competitive terms, subject to applicable eligibility criteria.

How good is a 780 CIBIL Score?

A 780 CIBIL Score is generally considered a strong score within the 300–900 range. It indicates a healthy credit profile, although the exact loan terms you receive depend on your overall financial profile and the applicable eligibility criteria.


  • Strong credit profile: A 780 score indicates a consistent history of responsible credit management.
  • Broader credit access: A strong score may support eligibility for different credit products, subject to applicable criteria.
  • Potentially favourable terms: A strong credit profile may help you access competitive interest rates and loan terms, depending on the lender and other factors.

If your score is 780, maintaining responsible credit habits can help protect your profile. You can check your personal loan eligibility in just 2 steps to understand your potential eligibility, subject to applicable criteria.

Show More Show Less

What else do lenders check beyond your CIBIL Score?

A 780 CIBIL Score is one part of your credit profile. Lenders may also assess your financial circumstances and repayment capacity before deciding on a loan application.

Here's what may be evaluated:


  • Repayment history: Timely EMI and credit card payments help demonstrate responsible credit behaviour.
  • Credit utilisation ratio: Lower and controlled credit utilisation can support a healthy credit profile.
  • Existing obligations: Current loans and outstanding balances are considered when assessing repayment capacity.
  • Enquiry history: Multiple recent credit enquiries may affect how your credit profile is assessed.
  • Length of credit history: A longer record of responsible credit management can contribute to your overall credit profile.
  • Income and repayment capacity: Your income and existing financial commitments may also influence loan eligibility.

Therefore, a 780 CIBIL Score does not by itself guarantee loan approval or specific loan terms.

Show More Show Less

How a 780 CIBIL Score affects your personal loan

A 780 CIBIL Score can support your personal loan application by indicating a strong credit profile. However, the loan amount, interest rate and other terms depend on your income, repayment capacity and applicable eligibility criteria.


  • Potentially competitive interest rates: A strong credit profile may help you access competitive rates, depending on the lender's assessment.
  • Loan eligibility: Your score can support your credit profile, while the eligible loan amount also depends on income and repayment capacity.
  • Credit assessment: A strong score may support the overall assessment of your application, although processing times vary.
  • Repayment options: Available repayment structures depend on the loan product and applicable terms.

If you are considering a personal loan, a 780 CIBIL Score indicates a strong credit profile. Check your eligibility and review the applicable loan terms before applying.

Show More Show Less

How a 780 CIBIL Score impacts interest rates?

A 780 CIBIL Score indicates a strong credit profile, which may support access to competitive personal loan interest rates. However, interest rates are determined by the lender based on your overall credit profile and other applicable factors.


For example, two borrowers may have different CIBIL Scores and receive different interest rates for the same loan amount because lenders consider factors beyond the score. These can include income, repayment capacity, existing obligations, loan amount and tenure.


A strong score can therefore support your credit profile, but it does not guarantee a particular interest rate.

Show More Show Less

CIBIL Score range: What each band means

A CIBIL Score ranges from 300 to 900. A higher score generally indicates a stronger credit profile, although loan eligibility and terms depend on several factors.

CIBIL Score rangeGeneral interpretationWhat it means for credit
300–549LowerMay indicate a weaker credit profile and could make obtaining credit more difficult.
550–649ModerateCredit may be available, but eligibility and terms depend on the lender's criteria.
650–749GoodIndicates a relatively healthy credit profile, with higher scores generally viewed more favourably.
750–900StrongGenerally indicates a strong credit profile and may support access to credit on competitive terms.

A score of 780 falls within the 750–900 range, which is generally considered strong. However, a CIBIL Score alone does not determine loan approval, interest rates or the loan amount offered.

Show More Show Less

How to maintain your CIBIL 780 Score?

A 780 CIBIL Score reflects a strong credit profile, so maintaining responsible credit habits can help protect it over time:


  • Pay all EMIs and credit card dues on time
  • Keep credit utilisation low and manageable
  • Avoid multiple loan or credit card applications within a short period
  • Monitor your credit report regularly and report inaccuracies when identified
  • Maintain a balanced credit mix and avoid unnecessary borrowing
  • Assess your repayment capacity before taking on new debt

A 780 CIBIL Score gives you a strong credit profile to maintain. Continuing timely repayments, responsible credit usage and careful borrowing can help preserve your score and support your future credit needs.

Show More Show Less

Key offerings: 3 loan types

Personal loan interest rate and applicable charges

Type of fee

Applicable charges

Rate of interest per annum

10% to 30.5% p.a.

Processing fees

Up to 4.13% of the loan amount (inclusive of applicable taxes).

Flexi Facility Charge

Term Loan – Not applicable

Flexi Loans –Up To Rs 1,999 To Up To Rs 18,999/- (Inclusive Of Applicable Taxes)

Will be deducted upfront from loan amount.

Bounce charges

Rs. 700 to Rs. 1,200/- per bounce

“Bounce charges” shall mean charges for (i) dishonor of any payment instrument; or (ii) non-payment of instalment (s) on their respective due dates due to dishonor of payment mandate or non-registration of the payment mandate or any other reason.

Part-prepayment charges

Full Pre-payment:

  • Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount as on the date of full pre-payment

  • Flexi Term (Dropline) Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

  • Flexi Hybrid Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

Part Pre-payment

  • Up to 4.72% (Inclusive of applicable taxes) of the principal amount of Loan prepaid on the date of such part Pre-Payment.

  • Not Applicable for Flexi Term (Dropline) Loan and Flexi Hybrid Term Loan.

Penal charge

Delay in payment of instalment(s) shall attract Penal Charge at the rate of up to 36% per annum per instalment from the respective due date until the date of receipt of the full instalment(s) amount.

Stamp duty (as per respective state)

Payable as per state laws and deducted upfront from loan amount.

Annual maintenance charges

Term Loan: Not applicable

Flexi Term (Dropline) Loan:

Up to 0.295% (Inclusive of applicable taxes) of the Dropline limit (as per the repayment schedule) on the date of levy of such charges.


Flexi Hybrid Term Loan:

Up to 0.472% (Inclusive Of Applicable Taxes) Of The Dropline Limit During Initial Tenure. Up to 0.295% (Inclusive Of Applicable Taxes) Of Dropline Limit During Subsequent Tenure

Credit guarantee scheme feeUp to 1.18% p.a. (pro-rated daily till 31st March) (inclusive of all applicable taxes) of the loan amount
Credit guarantee scheme renewal feeUp to 1.18% p.a. (inclusive of all applicable taxes) on the outstanding loan amount as on April 01 of the subsequent Financial Year.
*Renewal Fee to be collected only for 3 subsequent financial years.
 
**If the Remaining Tenure is less than 12 months, the CG Fee in subsequent years shall be charged prorated.

Frequently asked questions

Overview

Is 780 CIBIL score good?

Yes, a 780 CIBIL score is excellent. It reflects responsible credit behaviour and ensures that lenders will offer you low-interest rates and favourable loan terms. With this score, you can expect quick loan approvals and access to premium financial products. It also makes you a highly attractive candidate for competitive offers from banks and financial institutions. Check your eligibility for personal loan using just mobile number and OTP – 100% online process. 

No, a 780 credit score is not bad at all; it is excellent. This score demonstrates strong financial discipline and makes you a low-risk borrower. Lenders will likely offer you the best interest rates and loan terms, given your excellent credit history. A score of 780 ensures access to premium financial products with favourable terms and conditions.

A 780 credit score is considered excellent, significantly improving your chances of securing favorable loan terms. The exact financing amount depends on factors like income, debt-to-income ratio, and lender-specific policies. However, with a 780 score, you're likely to qualify for larger loan amounts and lower interest rates.

While there's no strict minimum CIBIL score for personal loans, lenders generally prefer scores above 650. However, some lenders may consider applications with lower scores, especially if you have a strong income and a good repayment history. Lower scores might result in higher interest rates and stricter terms.

While a 780 credit score is already excellent, maintaining and potentially improving it requires consistent responsible financial behaviour. Here are some tips:

  • Pay bills on time: Consistent timely payments are crucial for a healthy credit score.
  • Maintain low credit utilisation: Keep your credit card balances low compared to your credit limit.
  • Avoid excessive credit applications: Limit new credit inquiries to avoid unnecessary score impacts.
  • Monitor your credit report regularly: Check for errors and dispute any inaccuracies.
  • Consider a credit builder loan: Responsible repayment of a small loan can positively impact your credit history.
Show More Show Less

Disclaimer

Bajaj Finance Limited has the sole and absolute discretion, without assigning any reason to accept or reject any application. Terms and conditions apply*.
For customer support, call Personal Loan IVR: 7757 000 000