








₹ 2 lakh – ₹ 80 lakh
Check your pre-approved offer and other benefits
Enter mobile and OTP | Check offer | Know your exact loan terms
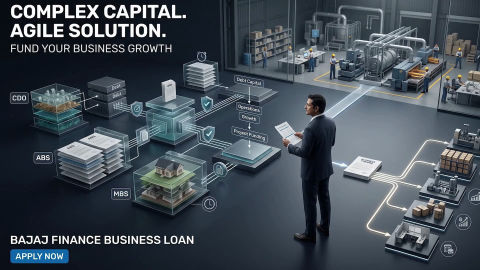
Structured Finance and Debt Capital
-
In summary
Structured finance is a financing approach that uses customised structures, asset pools, or cash flows to address complex funding and risk-management requirements.
- Common instruments include asset-backed securities (ABS), mortgage-backed securities (MBS), and collateralised debt obligations (CDOs).
- Securitisation can convert eligible pools of financial assets into tradeable securities with different risk profiles.
- Structured finance is used in areas such as project finance, receivables financing, real estate securitisation, and corporate transactions.
- The structure can distribute credit risk and create liquidity from assets or future cash flows.
- Complexity, credit risk, liquidity risk, interest-rate risk, and operational risk require detailed due diligence.
- In India, securitisation by regulated lenders is governed by the Reserve Bank of India's applicable directions.
Once a business has identified its funding requirement, it can also assess whether conventional business financing is more suitable than a complex structured-finance arrangement.
What is structured finance?
-
Structured finance is a specialised financial arrangement designed for funding requirements that may not be adequately addressed through conventional loans or other standard financial products.
A structured-finance transaction can involve pooling financial assets, separating associated risks and cash flows, and creating securities or financing arrangements around those assets. The structure is designed according to factors such as the underlying assets, expected cash flows, credit risk and requirements of the parties involved.
For example, a lender may hold a portfolio of eligible loans that generates periodic repayments. Through securitisation, eligible loans can be pooled and transferred into a structure from which securities are issued to investors. The resulting securities can have different risk and return characteristics.
The Reserve Bank of India (RBI) defines securitisation as a transaction in which credit risk in assets is redistributed by repackaging them into tradeable securities with different risk profiles. Its Securitisation of Standard Assets Directions, 2021 apply to specified regulated lenders, including non-banking financial companies (NBFCs).
How does structured finance work?
-
Structured finance works by designing a financing structure around specific assets, cash flows, risks, and funding requirements.
A simplified securitisation structure can work as follows:
- Asset creation: A lender originates eligible loans or other financial assets.
- Asset pooling: Similar eligible assets are grouped into a pool.
- Transfer to a special purpose entity: The assets may be transferred to a special purpose entity (SPE) under the transaction structure.
- Security issuance: The SPE can issue securities backed by the underlying assets and their cash flows.
- Risk allocation: Securities can be divided into different tranches with different levels of risk and priority of payment.
- Investor payments: Cash flows generated by the underlying assets are used to service the securities, according to the transaction structure.
The exact structure varies according to the transaction. Not every structured-finance transaction involves securitisation, and not every transaction uses the same type of asset, security or risk allocation.
Example
Consider a financial institution with a pool of eligible loans generating regular repayments.
Instead of waiting for the loans to mature, the institution could use a permitted securitisation structure to transfer eligible exposures and issue securities backed by the underlying cash flows. Investors then receive payments according to the terms and priority established for the securities.
The arrangement can provide liquidity to the originating institution while giving investors exposure to the underlying asset pool through the securities issued.
What are the types of structured finance?
Structured finance includes several instruments and transaction structures. The appropriate structure depends on the underlying assets, cash flows, risk allocation and financing objective.
| Type | How it works |
| Asset-backed securities (ABS) | Securities backed by pools of eligible assets such as loans or receivables. |
| Mortgage-backed securities (MBS) | Securities backed by pools of mortgage-related assets. |
| Collateralised debt obligations (CDOs) | Structured securities backed by a pool of debt exposures and divided into different risk tranches. |
| Credit-linked notes (CLNs) | Debt instruments whose payments are linked to the credit performance of specified reference assets or entities. |
| Structured investment vehicles (SIVs) | Specialised structures that have historically been used to invest in financial assets using a combination of funding sources. |
The regulatory treatment, permitted structures and risks vary across instruments. Investors and businesses should therefore assess the specific transaction documents rather than treating all structured-finance products as equivalent.


What are the benefits of structured finance?
Structured finance can provide access to customised funding structures, liquidity and risk-allocation mechanisms for suitable transactions.
Access to capital
Structured finance can provide an alternative source of funding for large or specialised transactions that do not fit conventional lending structures.
Liquidity generation
Securitisation can convert eligible financial assets and their associated cash flows into securities, allowing the originating institution to raise funds against the underlying pool.
Risk distribution
A structured transaction can allocate different levels of credit risk among securities or participants. The RBI notes that securitisation can facilitate credit-risk distribution and improve lender liquidity when appropriately structured.
Customised financing
The structure can be designed around the characteristics of the underlying assets, expected cash flows, repayment priorities, and risk requirements of the transaction.
Capital management
For eligible regulated entities, structured transactions can form part of broader capital and balance-sheet management strategies, subject to applicable regulatory requirements.
What are the disadvantages and risks of structured finance?
Structured finance involves risks that can arise from the underlying assets, transaction structure, market conditions, and operational processes.
| Risk | What it means |
| Credit risk | Borrowers underlying the asset pool may fail to make their scheduled payments, affecting cash flows available to investors. |
| Liquidity risk | A structured security may be difficult to sell at its expected value during stressed market conditions. |
| Interest-rate risk | Changes in interest rates can affect the value, funding cost or cash flows associated with certain structured instruments. |
| Operational risk | Errors in servicing, reporting, valuation or transaction administration can affect the structure. |
| Structural complexity | Multiple parties, contractual provisions and payment priorities can make the transaction difficult to analyse. |
| Regulatory risk | Changes in applicable regulations can affect how a transaction is structured, held or reported. |
The RBI has specifically recognised that complicated and opaque securitisation structures can create financial-stability concerns, which is why regulated securitisation transactions are subject to prudential requirements.
Where is structured finance used?
Structured finance can be used where a transaction involves substantial funding requirements, identifiable assets or receivables, and a need to allocate risk or cash flows through a customised structure.
- Project finance: Funding large infrastructure or development projects against expected project cash flows.
- Receivables financing: Using eligible receivables or future cash flows within an appropriate financing structure.
- Real estate finance: Structuring funding around property-related assets or cash flows.
- Corporate transactions: Supporting certain mergers, acquisitions or other capital-intensive transactions.
- Securitisation: Converting eligible pools of financial assets into securities for investors.
- Working capital structures: Arranging funding around eligible business receivables or other assets.
The suitability of structured finance depends on the transaction's size, asset quality, cash-flow characteristics, legal structure, regulatory requirements and the parties involved.
How is structured finance regulated in India?
Structured finance transactions can be subject to different regulatory frameworks depending on their structure and the entities involved.
For securitisation, the Reserve Bank of India (Securitisation of Standard Assets) Directions, 2021 apply to specified regulated entities, including scheduled commercial banks, certain all-India financial institutions, small finance banks and NBFCs. The framework sets requirements covering matters such as eligible assets, minimum holding periods, minimum retention requirements, disclosures and reporting.
The RBI's handbook also records requirements relating to securitisation, including restrictions on certain underlying assets and minimum retention requirements for specified regulated entities.
Because the applicable requirements depend on the transaction and participating entities, businesses and investors should review the relevant RBI directions and transaction documentation before entering into a structured-finance arrangement.
How is structured finance different from traditional finance?
Structured finance differs from conventional finance mainly in its complexity, customisation and use of underlying assets or cash flows.
| Factor | Structured finance | Traditional finance |
| Structure | Customised for specific assets, cash flows or risks | Based on standard lending or investment terms |
| Transaction size | Often used for complex or large transactions | Suitable across a broader range of funding requirements |
| Risk allocation | Can divide risk through different tranches or contractual arrangements | Risk is generally allocated through standard loan or investment terms |
| Underlying assets | Can involve pools of loans, receivables or other eligible assets | May rely on borrower creditworthiness, collateral or standard investment assets |
| Documentation | Often more extensive and transaction-specific | Usually more standardised |
| Participants | Can involve originators, investors, servicers, trustees and other parties | Often involves fewer parties |
Structured finance is therefore not simply a larger version of a conventional loan. It involves a different method of designing and allocating funding, cash flows and risk.
What is the difference between corporate finance and structured finance?
Corporate finance covers the broader financial management of a company, while structured finance focuses on specialised financing arrangements.
Corporate finance can include decisions involving capital budgeting, debt, equity, working capital, investments, cash management and overall capital structure.
Structured finance addresses specific funding or risk-management requirements through customised structures. It can involve securitisation, asset pooling, receivables and differentiated risk allocation.
For example, deciding whether a company should raise debt or equity is a corporate-finance decision. Creating a securitisation structure around a pool of eligible receivables is an example of structured finance.
Who uses structured finance?
Structured finance is primarily relevant to businesses, financial institutions, investors, and other parties involved in complex financing transactions.
It can be relevant to:
- Financial institutions managing eligible asset pools.
- Large companies with substantial receivables or specialised funding requirements.
- Infrastructure businesses seeking project-based financing.
- Institutional investors evaluating structured securities.
- Investment and financial-market participants involved in securitisation transactions.
The complexity and transaction costs involved mean that structured finance is not automatically suitable for every business or funding requirement.
Is structured finance suitable for small businesses?
Structured finance is not automatically suitable for small businesses because it is designed for specific and often complex financing requirements.
A small business seeking funds for inventory, working capital, equipment or expansion may first assess conventional business financing. A standard business loan can be more straightforward where the funding requirement does not require asset pooling, securitisation or customised risk allocation.
For example, a manufacturer requiring Rs. 20 lakh for machinery and working capital would need to compare the cost, eligibility criteria, repayment structure and documentation of conventional business financing with any specialised funding arrangement available to it.
How can a business finance its operating or expansion requirements?
Once you have identified the setup, operating or expansion costs involved, arranging suitable business funding can help you plan these expenses within your available cash flow.
For businesses that need conventional funding rather than a complex structured-finance transaction, a Bajaj Finance Business Loan can be considered for eligible business requirements. It offers a loan range of Rs. 2 lakh to Rs. 80 lakh and repayment tenures of 12 months to 96 months.
What are the eligibility criteria and documents for Bajaj Finance Business Loan?
Current eligibility criteria includes:
- Indian nationality.
- Self-employed work status.
- Business vintage of at least 3 years.
- CIBIL score of 650 or higher.
- Age requirements of 21 years at application and up to 80 years at loan maturity, subject to the applicable co-applicant requirements.
Documents required are:
- KYC documents - Aadhaar/ passport/ voter’s ID/ driving license
- PAN card
- Proof of business ownership
- Additional financial documents
How do you apply for a Bajaj Finance Business Loan?
- Click the 'Check Loan Offer' button to open the online application form.
- Enter basic details (Name, PAN, Date of Birth, PIN Code, Business details) and click 'CONTINUE'.
- Complete banking verification and continue.
- View your offer details, select the loan type (Term Loan, Flexi Dropline Loan, or Flexi Hybrid Loan), and choose the repayment tenure.
- Review the details and submit the business loan application.


Select loan by amount
Applicable fees and charges on our business loan

Loans for business needs
Get business loan for your needs
Women Business Loan
Get Women Business Loan upto 80 Lakh
Medical Store Business Loan
Get Medical Store Business Loan upto 80 Lakh
Manufacturer Business Loan
Get Manufacturer Business Loan upto 80 Lakh
Business loan in different cities

Business loan in bangalore

Business loan in mumbai

Business loan in pune

Business loan in Jaipur

Business loan in Kerala
Business loan for different budgets

2 lakh business loan
3 lakh business loan
5 lakh business loan
10 lakh business loan

15 lakh business loan
20 lakh business loan
25 lakh business loan
30 lakh business loan
50 lakh business loan
Types of business loan
Unsecured Business Loan
Secured Business Loan
Term Loan
Cash Credit
Working Capital Loan
Machinery Loan
Line of Credit
Micro Loan
Merchant cash Loan
Frequently asked questions
Overview
What is an example of structured finance?
An asset-backed security is an example of structured finance. It can be created by pooling eligible financial assets and issuing securities backed by the cash flows generated by those assets. Investors receive payments according to the terms and priority specified in the transaction structure. Other examples include mortgage-backed securities and collateralised debt obligations.
What are the main types of structured finance?
Common types include asset-backed securities, mortgage-backed securities, collateralised debt obligations, credit-linked notes and certain structured investment vehicles. These instruments differ in their underlying assets, cash-flow arrangements, risk allocation and regulatory treatment. The suitability of an instrument depends on the transaction's objectives, asset quality, investor requirements and applicable regulations.
What are the risks of structured finance?
Key risks include credit risk, liquidity risk, interest-rate risk, operational risk, structural complexity and regulatory risk. Credit risk can arise when borrowers associated with the underlying assets default. Liquidity risk can affect an investor's ability to sell a security. Complex structures can also make it harder to assess the underlying assets, cash flows and contractual obligations.
Is structured finance the same as securitisation?
No. Securitisation is one form of structured finance, rather than a synonym for the entire category. Securitisation involves redistributing credit risk by repackaging eligible assets into tradeable securities with different risk profiles. Structured finance is broader and can include other customised financing structures that do not necessarily involve securitisation.
Is structured finance suitable for every business?
No. Structured finance is designed for specific financing requirements and can involve substantial complexity, documentation and transaction costs. A business with a straightforward requirement such as working capital, equipment purchase or expansion may instead compare conventional business financing options. The appropriate choice depends on the funding amount, repayment capacity, underlying assets, transaction costs and applicable eligibility or regulatory requirements.
How is structured finance regulated in India?
Securitisation transactions undertaken by specified regulated lenders are governed by the Reserve Bank of India (Securitisation of Standard Assets) Directions, 2021. The framework covers areas such as eligible assets, minimum holding periods, minimum retention requirements, disclosures and reporting.
Can small businesses use structured finance?
Small businesses can potentially participate in specialised financing arrangements where the transaction structure, assets and participating institutions support it, but structured finance is not automatically appropriate for every small business. Businesses should compare the structure, costs, documentation, risks and repayment obligations with conventional financing options before proceeding.
More articles

Corporation: Meaning, Examples, Impact, Advantages and Disadvantages
Read More
What Is Venture Capital? Meaning, Types, Pros, Cons & How It Works
Read More
Operations Management: Definition, Types, Process & Examples
Read More
What is Capital Budgeting
Read More
Disclaimer
Bajaj Finance Limited has the sole and absolute discretion, without assigning any reason to accept or reject any application. Terms and conditions apply*.