Personal Loan Vs Mortgage Loan: Which One Is Better

Personal Loan Vs Mortgage Loan: Which One Is Better

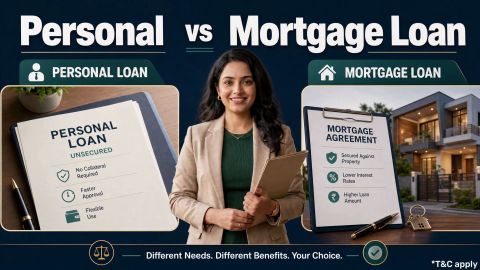
A personal loan vs mortgage loan comparison depends on your borrowing requirement, repayment capacity, total cost and willingness to pledge property as security.

Rs. 40,000 - Rs. 75 lakh

You may be eligible for a pre-approved offer

Enter mobile and OTP | Check offer | No branch visit needed


In summary


A personal loan does not require you to pledge property, while a mortgage loan is secured against eligible property. The right choice depends on how much you need, how much EMI you can afford, the total borrowing cost and whether you are comfortable using property as security. When comparing a personal loan with a mortgage loan:


  • Check the security requirement: A personal loan does not require property as security, while a mortgage loan uses eligible property to secure the borrowing.
  • Check interest rates: Mortgage loans can offer lower interest rates, although total borrowing costs depend on tenure and applicable charges.
  • Compare loan amount and tenure: Property-backed borrowing can support larger requirements and longer repayment periods, subject to eligibility and property value.
  • Consider the application process: A personal loan does not require property valuation or title verification. A mortgage loan involves property-related checks.
  • Consider the risk: A personal loan keeps your property outside the borrowing arrangement, while a mortgage involves property-related recovery risks.

If you prefer collateral-free borrowing, Bajaj Finance Personal Loan offers a convenient way to access funds. Check your pre-approved loan offer in just 2 steps.


What are the key differences between a personal loan and mortgage loan?

The key difference between a personal loan and a mortgage loan is the need for collateral. A personal loan is unsecured, meaning you do not need to pledge property, while a mortgage loan requires eligible property as security. Bajaj Finance also offers loan against property, allowing you to borrow for personal or business needs while continuing to own and use the property during loan tenure.


Here is how the two Bajaj Finance offerings compare:


Comparison factorBajaj Finance Personal LoanBajaj Finance Loan Against Property
Borrowing structureUnsecuredSecured
SecurityNo property pledgedEligible property pledged
Loan amountRs. 40,000 to Rs. 75 lakhUp to Rs. 15.50 crore*
Interest rate10% to 30.5% p.a.7.5% to 14.25% p.a.
Repayment tenure12 months to 108 monthsUp to 15 years*
Loan assessmentIncome, credit profile and existing obligationsIncome, credit profile, existing obligations and property
Property valuationNot requiredRequired
Property documentationNot required for collateral Required
Processing requirementsFinancial and identity verificationFinancial, property, legal and valuation checks
Disbursal timelineWithin 24 hours of approval*Within 72 hours of approval*

Last updated: 17th November, 2026


*Terms and conditions apply


The timelines refer to disbursal after approval and completion of applicable requirements. They are not guaranteed end-to-end application processing times. 


The two loans therefore differ not only in interest rates and loan amounts, but also in the security you provide, and the checks involved. A personal loan may involve a simpler application because there is no property valuation or title verification. A loan against property can support larger borrowing needs, but the property is part of the loan arrangement.


The choice therefore depends on how much you need, the repayment structure you prefer and whether you are comfortable pledging property.

Show More Show Less

Which loan may suit different borrowing needs?

Your borrowing requirement can help narrow down the choice. A personal loan may suit a range of eligible needs when you prefer not to pledge property. A mortgage loan may be worth considering when you need a larger amount, want a longer repayment period and have eligible property to offer as security.


Consider these common borrowing situations:


Your situationOption to considerWhy it may suit you
You need funds for urgent medical expensesPersonal loanNo property-related verification is required
You need Rs. 5 lakh for home repairsPersonal loanCollateral-free borrowing may suit the requirement
You need funds for wedding or travel expensesPersonal loanYou can borrow for eligible personal needs without pledging property
You need Rs. 40 lakh for business expansionMortgage loanA larger borrowing amount and longer tenure may be useful
You want to spread a substantial expense across more yearsMortgage loanLonger tenure can reduce the monthly EMI
You own property and need Rs. 25 lakhCompare bothThe suitable option depends on available offers, repayment capacity and borrowing cost

Last updated: 17th November, 2026


The table gives a starting point, not a final recommendation. For example, owning property does not mean you need to pledge it. Similarly, a larger borrowing requirement does not automatically make a mortgage loan the better choice if the repayment commitment does not fit your finances.


If you need a smaller or moderate amount and want to keep your property outside the borrowing arrangement, you can check your pre-approved personal loan offer in just 2 steps.

Show More Show Less

How do EMI and total interest compare?

Your EMI depends on the loan amount, interest rate and repayment tenure. A lower EMI can ease monthly repayments, but a longer tenure may increase total interest.


Consider Rahul, a 38-year-old salaried professional from Mumbai. He earns Rs. 1.2 lakh per month and needs Rs. 10 lakh for home renovation. He already pays Rs. 20,000 towards existing monthly EMIs.

Rahul compares a personal loan at 12% p.a. with a mortgage loan at 8% p.a.


Illustrative loan optionMonthly EMITotal interest
Personal loan at 12% p.a. for 5 yearsRs. 22,244Rs. 3.35 lakh
Mortgage loan at 8% p.a. for 5 yearsRs. 20,276Rs. 2.17 lakh
Mortgage loan at 8% p.a. for 10 yearsRs. 12,133Rs. 4.56 lakh

Last updated: 17th November, 2026


Figures are illustrative, assume constant interest rates and exclude applicable charges and taxes.


What does this mean for Rahul?


The five-year mortgage loan has a lower EMI and total interest than the five-year personal loan. However, Rahul would need to pledge eligible property and complete the required property, legal and valuation checks.


The 10-year mortgage option reduces Rahul's EMI to Rs. 12,133. However, the longer repayment period increases the total interest to Rs. 4.56 lakh.

Rahul's existing EMI of Rs. 20,000 also matters. Adding the five-year personal loan would take his total monthly EMI commitment to Rs. 42,244, which is about 35% of his monthly income.


This shows why comparing interest rates alone is not enough. Rahul needs to consider the EMI, total interest, existing commitments and whether he is willing to pledge property.


If he does not want to pledge property and can comfortably manage the higher EMI, a personal loan may suit his requirement. 


Pro-tip: Use the personal loan EMI calculator to estimate your monthly repayments before applying. Once you understand your EMI and total borrowing cost, consider which loan suits your financial needs. If you prefer borrowing without pledging property, Bajaj Finance Personal Loan may be worth exploring.

Show More Show Less

What factors should you check before choosing a loan?

The right choice depends on more than the interest rate. Compare the loan amount, EMI, total borrowing cost, security requirement and repayment period before accepting an offer.


1. How much do you need?


Your loan requirement can help narrow down the choice. A personal loan may suit eligible borrowing needs when you prefer not to pledge property. A mortgage loan may be worth considering when you need a larger amount and have eligible property to offer as security.


Do not borrow more than you need simply because a higher loan amount is available. A larger loan also means a larger repayment commitment.


2. How much EMI can you comfortably pay?


Your existing EMIs and regular expenses reduce the amount available for a new loan. Calculate the new EMI along with your current commitments instead of looking at the new EMI in isolation.


A lower EMI can provide more room in your monthly budget, but check whether a longer tenure would increase the total interest you pay.


3. Are you comfortable pledging property?


A personal loan does not require property as security. A mortgage loan uses eligible property as collateral.


If you choose secured borrowing, understand that the property remains part of the loan arrangement and may be subject to enforcement if you fail to meet your repayment obligations.


4. What is the total borrowing cost?


Check the interest, processing fee, applicable taxes, prepayment or foreclosure charges and other applicable costs.


5. What repayment period fits your budget?


A longer tenure spreads repayment across more months. This can lower the EMI but may increase the total interest paid.


Choose a repayment period that gives you enough room in your monthly budget without extending the loan unnecessarily.


6. Could your financial situation change?


Consider whether your income, household expenses or other financial commitments could change during the repayment period. An EMI that fits your budget today may become difficult to manage if 

your expenses increase or your income falls.


If you expect your financial commitments to change, leave enough room in your monthly budget rather than choosing an EMI that uses most of your available surplus.


7. Could you want to repay the loan earlier?


If you choose a longer tenure to keep the EMI manageable, check the applicable prepayment or foreclosure terms. You may want the option to reduce your outstanding loan later if your income increases or you have surplus funds.


Review the applicable charges and conditions before accepting the loan, as these can affect the total cost of borrowing.

Show More Show Less

When may a Bajaj Finance Personal Loan be worth considering?

A Bajaj Finance Personal Loan may be worth considering if you need funds without pledging property and the available EMI fits your monthly budget.


Bajaj Finance Personal Loan offers flexible repayment options, a convenient online application process and disbursal within 24 hours* of approval, subject to applicable conditions.


Here are the key features:


FeatureBajaj Finance Personal Loan
Loan amountRs. 40,000 to Rs. 75 lakh
Interest rate10% to 30.5% p.a.
Repayment tenure12 months to 108 months
CollateralNot required
ApplicationOnline
DisbursalWithin 24 hours* of approval, subject to applicable conditions

Last updated: 17th November, 2026


*Terms and conditions apply.


Bajaj Finance Personal Loan can be used for eligible personal needs such as medical expenses, education, travel, weddings, and home renovation. The loan amount and terms available to you depend on applicable eligibility, and verification.


The application does not require property valuation or title verification because the loan is unsecured. You can also choose from available repayment tenures and assess an EMI that fits your monthly budget. Review the applicable personal loan interest rates and charges before accepting an offer.


If a personal loan suits your needs, check your pre-approved personal loan offer and explore the borrowing options available to you.

Show More Show Less

Key offerings: 3 loan types

Personal loan interest rate and applicable charges

Type of fee

Applicable charges

Rate of interest per annum

10% to 30.5% p.a.

Processing fees

Up to 4.13% of the loan amount (inclusive of applicable taxes).

Flexi Facility Charge

Term Loan – Not applicable

Flexi Loans –Up To Rs 1,999 To Up To Rs 18,999/- (Inclusive Of Applicable Taxes)

Will be deducted upfront from loan amount.

Bounce charges

Rs. 700 to Rs. 1,200/- per bounce

“Bounce charges” shall mean charges for (i) dishonor of any payment instrument; or (ii) non-payment of instalment (s) on their respective due dates due to dishonor of payment mandate or non-registration of the payment mandate or any other reason.

Part-prepayment charges

Full Pre-payment:

  • Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount as on the date of full pre-payment

  • Flexi Term (Dropline) Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

  • Flexi Hybrid Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

Part Pre-payment

  • Up to 4.72% (Inclusive of applicable taxes) of the principal amount of Loan prepaid on the date of such part Pre-Payment.

  • Not Applicable for Flexi Term (Dropline) Loan and Flexi Hybrid Term Loan.

Penal charge

Delay in payment of instalment(s) shall attract Penal Charge at the rate of up to 36% per annum per instalment from the respective due date until the date of receipt of the full instalment(s) amount.

Stamp duty (as per respective state)

Payable as per state laws and deducted upfront from loan amount.

Annual maintenance charges

Term Loan: Not applicable

Flexi Term (Dropline) Loan:

Up to 0.295% (Inclusive of applicable taxes) of the Dropline limit (as per the repayment schedule) on the date of levy of such charges.


Flexi Hybrid Term Loan:

Up to 0.472% (Inclusive Of Applicable Taxes) Of The Dropline Limit During Initial Tenure. Up to 0.295% (Inclusive Of Applicable Taxes) Of Dropline Limit During Subsequent Tenure

Credit guarantee scheme feeUp to 1.18% p.a. (pro-rated daily till 31st March) (inclusive of all applicable taxes) of the loan amount
Credit guarantee scheme renewal feeUp to 1.18% p.a. (inclusive of all applicable taxes) on the outstanding loan amount as on April 01 of the subsequent Financial Year.
*Renewal Fee to be collected only for 3 subsequent financial years.
 
**If the Remaining Tenure is less than 12 months, the CG Fee in subsequent years shall be charged prorated.

Frequently asked questions

Cost And Repayment

Eligibility And Property

Application And Risk

Is a mortgage loan cheaper than a personal loan?

A mortgage loan may offer a lower interest rate because eligible property is pledged as security. However, the total borrowing cost depends on the loan amount, repayment tenure, processing fees and other applicable charges. A longer tenure may reduce your monthly EMI but increase the total interest paid. Compare the complete repayment amount and applicable charges before choosing either loan.

No. A longer repayment tenure generally reduces your monthly EMI but can increase the total interest paid. For example, repaying a loan over ten years instead of five years spreads the amount across more instalments. This lowers the monthly commitment but keeps the loan outstanding for longer. Consider both monthly affordability and total repayment before deciding.

No. A mortgage-backed facility such as loan against property requires eligible property to be offered as security. The lender assesses the property's ownership, value and documentation alongside your financial profile. Without suitable property to pledge, you would need to consider an unsecured borrowing option.

Yes. Owning property does not mean you must pledge it to borrow funds. A personal loan does not require collateral, and eligibility depends on factors such as income, credit history and existing financial commitments. If you prefer to keep your property outside the borrowing arrangement, a personal loan may suit your needs, provided the EMI is affordable.

A personal loan generally involves fewer verification steps because property valuation and title checks are not required. Bajaj Finance Personal Loan offers disbursal within 24 hours* of approval, while Bajaj Finance Loan Against Property offers disbursal within 72 hours* of approval. Both timelines depend on completing the required verification and documentation. Actual processing times may vary.

Serious repayment failure can affect your credit history and expose the property offered as security to enforcement action under the applicable agreement and law. You continue to own and use the property while meeting the repayment obligations. The possibility of property enforcement is therefore a key consideration before choosing secured borrowing.

Show More Show Less

Disclaimer

Bajaj Finance Limited has the sole and absolute discretion, without assigning any reason to accept or reject any application. Terms and conditions apply*.


For customer support, call Personal Loan IVR: 7757 000 000