







An OTP will be sent to this number for verification

You may have a pre-approved offer
Enter required home loan amount
In summary
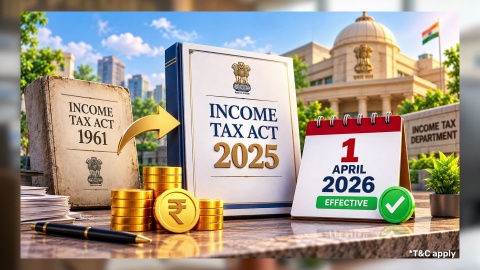
Income Tax Act 2025 - Key Features, Slabs, Rates, Deductions, and Implementation Dates 2026
Last updated: Sept 2026
A bill and an Act are not the same thing. Confusing the two leads to real confusion about what currently applies. The bill was the proposal. The Act is the law it became.
- Stage 1: Introduction, the bill formally presented in Parliament
- Stage 2: Committee review, detailed examination and stakeholder input before floor debate
- Stage 3: Passage, approval by both houses of Parliament
- Stage 4: Presidential assent, the final step making the bill legally binding as an Act
Effective date: the Income Tax Act, 2025 took effect from 1 April 2026, distinct from its earlier passage date
Reference "the Act," not the new income tax bill by its earlier name, once legislation has actually passed and received assent, since the bill itself no longer exists as a separate document once this happens.
Why do people still call it "the bill" now?
This is a common, understandable habit rather than a genuine error, since casual reference to legislation by its pre-passage name often persists well after actual enactment. The specific distinction matters mainly for precision, not because the underlying reference is meaningfully wrong once you understand what's meant.
3 practical reasons this terminology confusion persists in everyday conversation. The realistic reasons "bill" terminology persists are:
- Media and public discussion often continues using the more familiar earlier name even after formal passage
- The bill's original public discussion and debate period is what many people remember most vividly, not the technical assent date
Secondary sources and informal guidance sometimes lag behind in updating their own terminology after passage
Understanding that "the new income tax bill" and "the Income Tax Act, 2025" now refer to the same underlying law helps you avoid confusion when encountering both terms used interchangeably.
Show more
Show less
What actually happened at each stage of the bill's passage?
| Stage | What occurred |
|---|---|
| Introduction | The bill was formally presented in Parliament for consideration |
| Committee review | Detailed examination, including stakeholder and expert input |
| Passage | Approval by both houses of Parliament following floor debate |
| Presidential assent | Final formal step converting the passed bill into an enforceable Act |
The gap between passage and the Act's actual effective date (1 April 2026) reflects a deliberate implementation runway, giving taxpayers, employers, and tax professionals time to prepare for the new structure before it actually applied.
Show more
Show less
How do I know if guidance is bill-era or current?
Four checks confirm whether guidance you've encountered is current.
- Check the guidance's publication date relative to 1 April 2026, the Act's effective date.
- Look for terminology cues, such as "Tax Year" (current Act) versus "Assessment Year" (prior framework), as a rough dating signal.
- Cross-check specific provisions against the official Income Tax Department's current published Act text.
Where genuine doubt exists, consult a tax professional to confirm which framework applies to your specific situation and year.
Older guidance isn't necessarily wrong for the period it covers, but applying pre-2025 guidance to a current-year situation without checking for updates risks missing a genuine structural change.
Show more
Show less
A worked example: distinguishing bill-era and Act-era guidance
Consider Manoj, a 37-year-old consultant with a household income of Rs. 1.3 lakh a month and a CIBIL Score of 749, who found online guidance referencing "the pending income tax bill" while researching his current filing.
| Step | What Manoj did |
|---|---|
| Found the reference | An article discussing "the pending bill's provisions" |
| Checked the publication date | The article predated the bill's actual passage and assent |
| Verified current status | Confirmed the bill had since become the Income Tax Act, 2025, now in force |
| Used current guidance | Referenced the Act's actual current provisions instead of the outdated bill-stage discussion |
Because Manoj checked the publication date against the Act's known effective date, he avoided relying on outdated, pre-passage discussion for a decision that needed current information.
Show more
Show less
Home loan for professionals
Financing your home under the current Act's framework with Bajaj Finance
| Loan feature | Detail |
|---|---|
| Interest rate | From 7.25% p.a.*, subject to credit assessment |
| Loan amount | Up to Rs. 15 crore* |
| Tenure | Up to 32 years |
Correctly applying the current Income Tax Act's provisions, rather than outdated pre-passage guidance, supports accurate income documentation for a home loan application. Approval timelines can extend where tax documentation needs clarification, and minimum income thresholds can differ by city. Check your home loan eligibility with your filings aligned to current law.
Show more
Show less
Frequently Asked Questions
Understanding the legislative process
Practical application
Did the new income tax bill change the actual tax rates, or just the law's structure?
The legislative passage itself was primarily a structural and simplification exercise, reorganising and renumbering provisions for clarity. Actual rate changes happen through the separate annual Finance Act process, which operates independently of this specific structural overhaul, regardless of which particular assessment year it actually happens to occur and apply within.
How long did the bill actually take to become law from introduction to assent?
The specific timeline involved multiple stages, including committee review and parliamentary debate, spanning a meaningful period before final passage and assent. Refer to official parliamentary records for the precise dates if you need the exact, complete timeline for your own specific reference, research, or later academic purposes going forward from here.
Does the transition from bill to Act affect returns filed for years before 2025?
No, returns and assessments for earlier years remain governed by the framework applicable at that specific time, following the previous Act's structure and terminology. The new Act's provisions apply prospectively from its own effective date, not retroactively applied to already-completed prior filings and finalised assessments from any earlier tax years at all.
Where can I find the official, current text of the Income Tax Act, 2025?
The official Income Tax Department website maintains the current, authoritative text of the Act, along with related notifications and circulars. This remains far more reliable than any secondary summary or older cached version that might not correctly reflect subsequent amendments at all, even today, given how frequently guidance can change.
Home Loan in Different Cities

Home Loan in Mumbai

Home Loan in Ahmedabad

Home Loan in Bangalore

Home Loan in Chennai

Home Loan in Delhi

Home Loan in Hyderabad

Home Loan in Cochin

Home Loan in Noida

Home Loan in Pune
Home Loan for different budget
Check your pre-approved offer now
Our Calculators
What do our customers say about us
customers
Play Store rating
reviews
Amit Shiva
Reviewed on
Smooth and transparent home loan process. The interest rates were competitive, and documentation was minimal. The team guided me clearly at every step, making my first home purchase stress-free. Highly recommended for quick approvals.
Sandeep Kulkarni
Reviewed on
The loan disbursal was fast, and the customer support team was extremely patient with all my queries. Flexible EMIs helped me manage my monthly expenses easily. A great experience for salaried homebuyers.
Ritika Agarwal
Reviewed on
I had a great experience while transferring my existing home loan. The process was quick, and I saved significantly with the lower interest rate. Customer service was helpful throughout. Highly recommended for balance transfers.
Manoj Verghese
Reviewed on
Clear guidance, quick approval, and flexible repayment options made buying my new house easier than expected. The team handled everything professionally. Very satisfied and would definitely recommend their home loans
Find your nearest branch

More Articles
Watch our videos
Documents required to get a Bajaj Finserv Home Loan
Tips to increase your Home Loan eligibility
Things you need to know about pre-approved home loan
Things you need to know before applying for a Home Loan
How does Repo Rate affect your Home Loan
Download App
Now request money from your friends and family and make instant payments.
- Choose from personal, business, gold loans and more
- Pay utility bills, use UPI, get FASTag and more
- Buy over 1 million products on No Cost EMI
- Buy stocks, mutual funds and invest in FD
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (NBFC) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.