








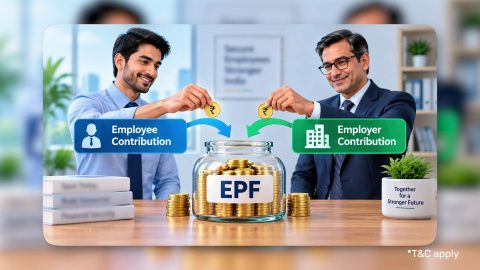
PF Contribution Breakdown
-
In summary
- The employee contribution is 12% of the applicable PF wage and is credited to the EPF account.
- The employer's statutory contribution is 12%, divided between EPF and EPS.
- 3.67% of the employer's contribution goes towards EPF, while 8.33% goes towards EPS, subject to the applicable wage ceiling.
- The employer also contributes towards EDLI and EPF administrative charges.
- PF contributions are generally calculated using Basic Pay, Dearness Allowance and Retaining Allowance, where applicable.
- Employees can make additional contributions through Voluntary Provident Fund (VPF), subject to applicable rules.
- Tax treatment depends on the type and amount of contribution and the applicable income-tax provisions.
-
Features of breakup of EPF contribution
The standard PF contribution structure includes employee deductions, employer contributions, pension allocation, insurance contributions, and administrative charges.
Contribution component Paid by Standard allocation Employee EPF contribution Employee 12% of basic salary and DA Employer’s total EPF and EPS contribution Employer 12% of basic salary and DA Employer’s EPS allocation Employer 8.33%, subject to Rs. 15,000 wage ceiling Maximum monthly EPS contribution Employer Rs. 1,250 Employer’s EPF allocation Employer Remaining employer contribution EDLI contribution Employer 0.50%, subject to the applicable ceiling EPF administrative charge Employer 0.50%, subject to prescribed minimums EDLI administrative charge Employer Nil currently The commonly quoted 3.67% employer EPF allocation applies when contributions are calculated on the Rs. 15,000 statutory wage ceiling. Where contributions are made on higher wages, EPS ordinarily remains capped at Rs. 1,250, while the remaining employer contribution enters EPF.
What is the PF contribution breakup?

Avoid these mistakes while booking FD
-
PF contributions are divided between the employee and employer. The employee's contribution goes towards the EPF account, while the employer's contribution is allocated between EPF and EPS.
The source describes the statutory contribution structure as follows:
Contribution Rate Allocation Employee contribution 12% EPF Employer contribution 12% 3.67% EPF + 8.33% EPS, subject to applicable ceiling Employer EDLI contribution 0.50% EDLI Employer administrative charge 0.50% EPF administration This means the employer's total statutory outgo can be higher than the 12% credited towards the employee's EPF and EPS because of the additional EDLI and administrative contributions.
What salary is used to calculate PF contributions?
-
PF contributions are calculated on the applicable statutory PF wages. The source identifies the following components:
- Basic Pay
- Dearness Allowance (DA)
- Retaining Allowance, where applicable
The source excludes components such as HRA, overtime allowances, statutory bonuses, performance commissions and travel concessions from the stated PF wage calculation base.
How is the employee's 12% PF contribution divided?
The employee contributes 12% of the applicable PF wage towards EPF.
For example, if the applicable monthly PF wage is Rs. 30,000:
Employee contribution = Rs. 30,000 × 12% = Rs. 3,600
The source treats the employee's entire statutory contribution as going to EPF Account No. 1.
How is the employer's 12% PF contribution divided?
The employer's statutory 12% contribution is divided between EPF and EPS.
Under the structure described in the source:
- 3.67% goes towards EPF.
- 8.33% goes towards EPS, subject to the applicable Rs. 15,000 wage ceiling.
- The resulting EPS contribution is capped at Rs. 1,250 per month under the stated statutory calculation.
Where the applicable employer contribution exceeds the EPS allocation, the remaining amount is credited towards EPF.
What are EPS and EPF?
EPF, or Employees' Provident Fund, is the retirement savings component of the PF system. Contributions credited to the EPF account form part of the member's provident fund balance.
EPS, or Employees' Pension Scheme, is the pension component funded from the employer's contribution. It supports pension-related benefits subject to the applicable EPS eligibility and service conditions.
Therefore, the entire employer contribution does not appear as an EPF balance because a portion is allocated towards EPS.
What is the EPS contribution limit?
The source states that the mandatory EPS contribution is calculated at 8.33% of the applicable wage, subject to a statutory wage ceiling of Rs. 15,000 per month.
Therefore:
Rs. 15,000 × 8.33% = approximately Rs. 1,250 per month
This is why the standard EPS allocation is shown as Rs. 1,250 per month in the contribution breakup.
Check out different FD Rates
What is EDLI in PF?
EDLI, or Employees' Deposit Linked Insurance Scheme, provides an insurance benefit linked to EPF membership.
The source states that the employer contributes 0.5% towards EDLI, subject to a monthly contribution ceiling of Rs. 75.
The EDLI contribution is separate from the employee's EPF contribution and does not reduce the 12% deducted from the employee's salary.
What are EPF administrative charges?
The employer also contributes towards EPF administrative expenses.
The source specifies an administrative contribution of 0.5% of the applicable PF wage, with a minimum of Rs. 500 per month under the stated structure.
These charges are an employer liability and are separate from the employee's 12% PF deduction.
How does the PF contribution breakup work at different salary levels?
The following illustrations show how the contribution structure changes as the applicable Basic Pay plus DA increases.
| Monthly Basic + DA | Employee EPF at 12% | Employer EPF | Employer EPS | Employer EDLI | Employer admin charge |
|---|---|---|---|---|---|
| Rs. 15,000 | Rs. 1,800 | Rs. 550 | Rs. 1,250 | Rs. 75 | Rs. 75* |
| Rs. 30,000 | Rs. 3,600 | Rs. 2,350 | Rs. 1,250 | Rs. 75 | Rs. 150 |
| Rs. 50,000 | Rs. 6,000 | Rs. 4,750 | Rs. 1,250 | Rs. 75 | Rs. 250 |
| Rs. 1,00,000 | Rs. 12,000 | Rs. 10,750 | Rs. 1,250 | Rs. 75 | Rs. 500 |
The source notes a Rs. 500 minimum administrative charge, while the salary illustration displays Rs. 75 for the Rs. 15,000 example. The applicable EPFO contribution rules should be checked when calculating an actual payroll contribution.
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
How is PF contribution calculated on a Rs. 30,000 salary?
Assuming Rs. 30,000 represents the applicable Basic Pay plus DA:
Employee contribution:
Rs. 30,000 × 12% = Rs. 3,600
Employer EPF contribution:
Rs. 30,000 × 3.67% = Rs. 1,101
The employer's overall allocation also includes the EPS component, with the contribution subject to the applicable EPS wage ceiling, along with EDLI and administrative charges.
The actual payroll breakup can therefore differ from simply adding 12% employee contribution and 12% employer contribution.
Can an employee contribute more than 12% to EPF?
Yes. An employee can make an additional voluntary contribution through the Voluntary Provident Fund (VPF).
The source states that an employee can contribute up to 100% of Basic Pay and DA through VPF, subject to the applicable rules. However, the tax treatment of interest on employee contributions above the prescribed annual threshold needs to be considered.
What are the tax implications of PF contributions?
PF tax treatment depends on the type of contribution, the applicable tax regime and the amount contributed.
The source identifies two important areas:
Employee contribution and Section 80C
Under the Old Tax Regime, the employee's eligible PF contribution can qualify for deduction under Section 80C, subject to the overall limit of Rs. 1.5 lakh per financial year.
Taxation of interest on higher employee contributions
The source states that where annual employee contributions to EPF and VPF exceed Rs. 2.5 lakh, interest attributable to the contribution above the prescribed threshold is taxable.
A separate threshold of Rs. 5 lakh is identified where there is no employer contribution, such as in the case of certain government provident fund arrangements.
What is the Rs. 7.5 lakh employer contribution threshold?
The source also identifies a separate tax rule covering aggregate employer contributions towards:
- EPF
- National Pension System (NPS)
- Approved superannuation funds
Where the aggregate employer contribution exceeds Rs. 7.5 lakh in a financial year, the excess can be treated as a taxable perquisite under the provisions cited in the source. The tax treatment of income arising from such excess contribution is also subject to the applicable provisions.
What happens to the employer's contribution above the EPS limit?
The employer's contribution is divided between EPF and EPS according to the applicable rules.
Where the EPS allocation is restricted by the applicable wage ceiling, the balance of the employer's statutory contribution is allocated towards EPF. This means that the employer's EPF component can increase when the applicable PF wage is higher than the statutory EPS wage ceiling.
Can an employee opt out of EPF?
The source states that an employee may be able to opt out of EPF at the beginning of their career if their starting Basic Pay plus DA exceeds Rs. 15,000 per month and they have never previously been an EPFO member, subject to the applicable conditions and Form 11 declaration.
Once an employee becomes an active EPFO member, the source states that participation is generally mandatory.
Locate to your nearest FD branch

What is the difference between employee and employer PF contributions?
| Parameter | Employee contribution | Employer contribution |
|---|---|---|
| Standard contribution | 12% | 12% |
| EPF allocation | 12% | 3.67% plus applicable balance |
| EPS allocation | Nil | 8.33%, subject to applicable ceiling |
| EDLI | Nil | 0.5%, subject to applicable ceiling |
| Administrative charge | Nil | 0.5%, subject to applicable minimum |
| Deducted from employee salary | Yes | No |
The employee's contribution is deducted from salary, while the employer bears the employer-side contribution and applicable additional statutory charges.
Related Articles

Frequently Asked Questions
Overview
How much does an employee contribute to PF?
The standard employee contribution is 12% of the applicable PF wage, comprising Basic Pay, DA and Retaining Allowance where applicable. The source states that the employee's full statutory contribution is credited to EPF.
How much does the employer contribute to PF?
The standard employer contribution is 12%, divided between EPF and EPS according to the applicable rules. The employer also bears separate contributions towards EDLI and administrative charges.
Why does only part of the employer's contribution appear in EPF?
Part of the employer's contribution is allocated to EPS rather than EPF. Under the structure described in the source, 8.33% is allocated to EPS subject to the applicable Rs. 15,000 wage ceiling, while 3.67% is allocated to EPF.
Why is EPS capped at Rs. 1,250 per month?
The source uses a Rs. 15,000 statutory wage ceiling for mandatory EPS contributions. Applying 8.33% to Rs. 15,000 gives approximately Rs. 1,250 per month.
What is EDLI in PF?
EDLI stands for Employees' Deposit Linked Insurance Scheme. It is funded by the employer and provides an insurance benefit to eligible EPF members under the applicable scheme rules. The source states an employer contribution of 0.5%, subject to a Rs. 75 monthly ceiling.
Can I contribute more than 12% to PF?
Yes. Additional contributions can be made through VPF, subject to the applicable rules. The source states that VPF contributions can be made up to 100% of Basic Pay and DA.
Is interest on PF contributions above Rs. 2.5 lakh taxable?
The source states that interest attributable to employee contributions above Rs. 2.5 lakh in a financial year is taxable. A separate Rs. 5 lakh threshold is identified for cases where there is no employer contribution.
What is the current PF contribution rate?
The employee contributes 12% of their basic salary to the EPF account. From the employer’s side, 3.67% goes to EPF and 8.33% to the Employee Pension Scheme (EPS), with the EPS contribution capped at Rs. 1,250 per month (based on a salary limit of Rs. 15,000).
What does the 12% EPF rule mean?
Under the EPF scheme, 12% of an employee’s basic salary plus dearness allowance (DA) is deducted as a contribution. This rule applies mandatorily to employees earning up to Rs. 15,000 per month (basic + DA).
Should I choose Rs. 1,800 or 12% for PF contribution?
The mandatory employer contribution is 12% of Rs. 15,000, which amounts to Rs. 1,800 per month. However, employers can choose to contribute more voluntarily if they wish.
What is the 12% PF contribution?
Under EPF rules, both the employee and employer generally contribute 12% of the employee’s basic salary and dearness allowance towards the Provident Fund account.
How are PF contributions treated during maternity leave?
Both employer and employee PF contributions generally continue during paid maternity leave, as maternity benefits are treated as part of employee wages under EPF regulations.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.