








Fixed Deposit Sweep In
-
In Summary
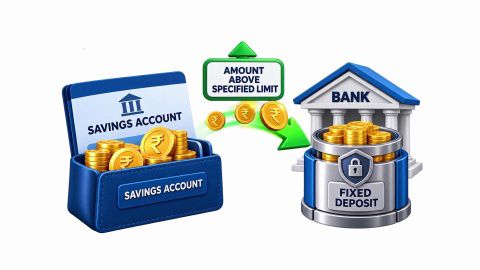
An auto sweep facility connects an eligible savings account with a fixed deposit to help manage surplus funds. It allows money above a predefined balance to earn FD interest while keeping funds accessible for eligible transactions.
- Meaning: Surplus funds are automatically transferred from a savings account into a linked FD.
- How it works: Sweep-out moves surplus money into the FD; sweep-in moves money back when the account balance is insufficient.
- Main benefit: It can help surplus funds earn a different rate of interest from the savings account, without requiring manual transfers each time.
- Example: If the sweep threshold is Rs. 30,000 and the account balance reaches Rs. 70,000, Rs. 40,000 may be transferred to the linked FD, subject to the bank’s rules.
- What to check: Review the minimum balance, transfer multiples, FD tenure, interest calculation, withdrawal rules, penalties and tax treatment before activation.
Auto sweep facilities differ across banks. The actual interest earned and access to funds depend on the linked deposit’s terms and the bank’s process.
What is an auto sweep facility?
-
An auto sweep facility is a banking feature that links a savings account to a fixed deposit. When the savings account balance exceeds a predefined threshold, the surplus amount is automatically transferred into an FD. This is commonly called a sweep-out.
If the savings account balance later falls below the required level, the bank may transfer the amount needed from the linked FD back into the savings account. This is known as a sweep-in or reverse sweep.
The facility combines the transaction convenience of a savings account with the interest structure of a fixed deposit. However, it does not necessarily offer the same access conditions as an ordinary savings balance. The amount transferred back, the order in which deposits are used and the interest applied to withdrawn amounts depend on the bank’s rules.
How does an auto sweep facility work?
-
An auto sweep facility generally follows three steps.
- Set a threshold balance: Choose or accept the minimum amount that should remain in the savings account, according to the bank’s available options.
- Move surplus funds into an FD: When the account balance crosses the threshold, the excess amount is transferred to a linked fixed deposit in accordance with the bank’s rules.
- Move funds back when needed: If the savings account balance becomes insufficient for a payment or withdrawal, the bank may break or partially withdraw the required amount from the linked FD and transfer it back.
The bank may use specified transfer multiples, deposit tenures and rules for selecting which FD to use first. Some facilities also impose minimum or maximum amounts. Check these conditions before enabling the feature.
Example of an auto sweep facility
Suppose a savings account has a balance of Rs. 70,000 and the account holder sets a threshold of Rs. 30,000.
Particulars Amount Savings account balance Rs. 70,000 Threshold to remain in the account Rs. 30,000 Potential amount swept into the linked FD Rs. 40,000 Later shortfall in the savings account Rs. 10,000 Amount potentially swept back to the account Rs. 10,000 In this example, Rs. 40,000 is transferred to the FD when the threshold is crossed. If the account later needs another Rs. 10,000, the bank may transfer that amount back from the linked FD.
This is an illustrative example. The actual sweep amount and process may vary depending on the bank’s threshold, transfer multiples and deposit rules.
What are the benefits of an auto sweep facility?
An auto sweep facility can help account holders manage surplus money without repeatedly transferring it manually. Its usefulness depends on the interest rate, withdrawal terms and how often funds are needed.
Potential to earn more interest
Surplus money transferred to an FD may earn a higher interest rate than it would in a savings account. The difference depends on the bank’s applicable savings and FD rates, the deposit tenure and the amount swept.
The higher rate is not guaranteed to result in a better overall outcome in every case. Frequent withdrawals, premature-withdrawal rules and tax on interest can affect the effective return.
Convenient access to funds
When the savings account balance becomes insufficient, a linked FD may provide funds through the sweep-in process. This can reduce the need to manually arrange a separate withdrawal, subject to the bank’s operating rules.
Automatic management of surplus funds
Once the facility is activated, eligible transfers take place according to the bank’s configured rules. This can be useful for people whose account balances fluctuate because of salary credits, regular bills or other incoming and outgoing payments.
Helps balance liquidity and savings
A threshold lets an account holder retain a chosen amount in the savings account while transferring eligible surplus money into an FD. The threshold should reflect expected expenses and payment obligations so that sufficient money remains available for routine transactions.
Less need to manage multiple transfers manually
An auto sweep facility can reduce the need to create and manage individual deposits manually whenever the account has excess funds. The exact number and structure of linked deposits depend on the bank.
What are the disadvantages of an auto sweep facility?
An auto sweep facility can be useful, but it is important to understand its limitations before activating it.
Premature withdrawal may affect interest
When money is transferred back from an FD before maturity, the bank may calculate interest using the applicable premature-withdrawal rules. Depending on the product, the interest rate may be revised or a penalty may apply.
Do not assume that every auto sweep FD allows penalty-free withdrawals. Check the bank’s specific terms.
Minimum balance requirements may apply
The bank may require a minimum balance in the savings account or a minimum amount for each FD created through the facility. If the account balance falls below a required level, the bank may also apply its usual account-related charges where applicable.
Returns may be lower than expected
Interest depends on the FD’s applicable rate and tenure, the amount and period for which funds remain in the deposit, and any withdrawal or penalty rules. If funds are frequently swept back, the actual interest earned may be lower than expected.
The facility may have limited flexibility
Some banks allow only specified FD tenures, transfer multiples or account types. The bank may also decide which linked deposit is used first when funds are required.
Interest is taxable
Interest earned on the FD portion is generally taxable according to the applicable income tax rules. Tax deducted at source (TDS) may also apply where the relevant conditions are met. The account holder should consider tax when comparing the effective return with that of a savings account.
How can you activate an auto sweep facility?
The process varies by bank and account type. Some banks allow customers to activate the facility through internet banking or a mobile app, while others may require a branch visit or a request through customer service.
A typical process is as follows:
- Check eligibility: Confirm that the savings account is eligible for the facility and whether a linked FD is required.
- Open the bank’s digital banking service: Log in to internet banking or the mobile banking app, if online activation is available.
- Find the relevant option: Look under account services, deposits or fixed deposit settings for an option such as “Auto Sweep”, “Sweep Facility” or a similar name.
- Set the threshold: Select the minimum balance to be retained in the savings account, if the bank allows you to choose it.
- Review the deposit settings: Check the FD tenure, minimum sweep amount, transfer multiples, maturity instructions and withdrawal rules.
- Confirm the request: Review the details and complete the bank’s required authentication or application process.
- Check activation: Follow the bank’s instructions to confirm when the facility becomes active.
These are general steps, not a universal process. Activation time and available options depend on the bank, so check the institution’s official instructions before proceeding.
What should you check before choosing an auto sweep facility?
Compare the facility’s conditions with your cash-flow needs before activating it.
- Threshold balance: Make sure the amount left in the savings account can cover routine expenses and scheduled payments.
- FD interest rate: Check the rate applicable to the deposit created through the facility rather than assuming it matches every regular FD rate.
- Deposit tenure: Understand how long each swept amount is deposited for and what happens at maturity.
- Sweep-out rules: Check when surplus funds are transferred and whether the bank uses minimum amounts or specified multiples.
- Sweep-in rules: Find out how the bank determines the amount to transfer back and which linked FD is used first.
- Premature-withdrawal conditions: Check whether the withdrawn portion earns a reduced rate or attracts a penalty.
- Fees and account charges: Review the applicable savings account and service-charge schedule. Do not assume that every bank offers the facility free of charge.
- Tax treatment: Interest earned on the linked FD is generally taxable under the applicable income tax rules.
- Deposit protection: Confirm whether the linked deposit is held with a bank covered by deposit insurance and understand the limits of that protection.
For bank deposits covered by the Deposit Insurance and Credit Guarantee Corporation (DICGC), the insurance limit is up to Rs. 5 lakh per depositor per bank, including principal and interest, for deposits held in the same right and capacity. Eligible savings and fixed deposits with the same bank are aggregated for this limit. See the RBI’s deposit insurance guidance.
What is the difference between auto sweep, sweep-in and sweep-out?
These terms describe related parts of the facility, but they are not always used consistently by every bank.
| Term | Meaning |
|---|---|
| Auto sweep | The overall facility that automatically moves money between an eligible bank account and a linked FD. |
| Sweep-out | The transfer of surplus funds from the savings account into the FD. |
| Sweep-in | The transfer of funds from the FD back into the savings account when money is needed. |
| Regular fixed deposit | A deposit opened for a specified amount and tenure, generally without automatic transfers linked to a savings account unless a suitable facility is available. |
Some banks use “auto sweep”, “sweep-in” or other product names to describe the full arrangement. Check the bank’s definition and terms rather than relying on the name alone.
Check out different FD Rates
How is an auto sweep facility different from a regular fixed deposit?
A regular FD is opened for a specified amount and tenure. An auto sweep facility, by contrast, links a savings account to an FD arrangement so that eligible surplus funds can be deposited automatically and funds can be transferred back when needed.
| Basis | Auto sweep facility | Regular fixed deposit |
|---|---|---|
| How funds are deposited | Eligible surplus funds may be transferred automatically | A specified amount is deposited when the FD is opened |
| Access to funds | Funds may be transferred back through sweep-in, subject to terms | Premature withdrawal is governed by the FD’s terms |
| Deposit amount | Can vary as surplus funds are swept into the linked deposit | Usually based on the amount selected when the deposit is opened |
| Interest | Depends on the linked FD’s applicable terms and the time funds remain deposited | Depends on the FD rate, tenure and applicable terms |
| Administration | Requires an eligible linked account and facility | Can be maintained as a standalone deposit |
An auto sweep facility may suit people with fluctuating account balances and recurring payment needs. A regular FD may be more appropriate for money that can remain deposited for a chosen period. The choice depends on liquidity needs, interest rates and the relevant terms.
Can an auto sweep facility be linked to any fixed deposit?
No. A sweep facility is generally available only for eligible combinations of a savings or current account and a fixed deposit under the same bank’s rules. The bank may require a new FD to be created through the facility or allow eligible existing deposits to be linked.
A fixed deposit from a different financial institution cannot automatically be assumed to be eligible. For example, a bank’s sweep facility should not be assumed to link to a separate deposit held with a non-banking financial company (NBFC). Check the product terms with the institution holding the account.
If the aim is to earn interest on funds that can remain invested for a specified tenure, a standalone FD is another option to evaluate. Compare the interest rate, tenure, liquidity, tax treatment and issuer terms before choosing.
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
To conclude...
An auto sweep facility automatically moves surplus funds from an eligible savings account into a linked fixed deposit and may transfer money back when the account needs funds. It can help manage fluctuating balances and potentially earn FD interest on money that would otherwise remain in a savings account. However, the facility’s threshold, interest rate, deposit tenure, transfer process and premature-withdrawal rules vary by bank. Before activating it, check the conditions carefully and retain enough money in the savings account for routine expenses. The most suitable option depends on how often funds are needed, the returns available and the terms of the linked deposit.
Locate to your nearest FD branch

Related Articles

Frequently Asked Questions
Overview
Is an auto sweep facility the same as a fixed deposit?
No. A fixed deposit is a deposit held for a specified tenure. An auto sweep facility links an eligible bank account to an FD arrangement so surplus funds can be transferred automatically and money can be moved back when required, subject to the bank’s rules.
Does an auto sweep facility guarantee higher returns?
No. Funds transferred into an FD earn interest according to the applicable deposit terms, which may differ from the savings account rate. Actual returns depend on the rate, tenure, withdrawals, any applicable penalties and tax.
Can I withdraw money whenever I need it?
A sweep-in facility may transfer funds from the linked FD when the savings account balance is insufficient. However, the process, availability and treatment of the withdrawn amount depend on the bank’s rules. Check the terms before relying on it for urgent payments.
Are there charges for using an auto sweep facility?
Charges vary by bank and account type. Some facilities may not have a separate activation fee, but account-related charges or premature-withdrawal conditions may still apply. Review the bank’s current schedule of charges and deposit terms.
Is interest earned through an auto sweep facility taxable?
Interest earned on the FD portion is generally taxable under the applicable income tax rules. TDS may apply when the relevant legal conditions are met. The actual tax treatment depends on the taxpayer’s circumstances and the rules in force.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.