








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
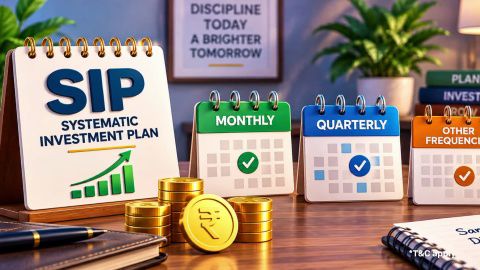
SIP Investing - How to Start, Manage & Optimise Your SIP
In summary
An SIP lets you invest regularly in a mutual fund instead of investing a large amount at one time.
- SIP is a method of investing, not a mutual fund type.
- You can invest a fixed amount at regular intervals.
- Rupee-cost averaging spreads purchases across different NAVs.
- Compounding can support long-term wealth accumulation.
- SIP does not remove market risk or guarantee returns.
- The Bajaj Broking website offers 4,000+ mutual fund schemes.
The minimum SIP on the Bajaj Broking website is Rs. 100 per month, subject to applicable scheme terms. KYC is mandatory before investing. SIP suitability depends on your financial goal, investment horizon, and the risk level of the mutual fund you select.
What is an SIP?
SIP stands for Systematic Investment Plan. It is a way of investing a fixed amount in a mutual fund at regular intervals, usually every month. You decide the amount and frequency, and each instalment buys units of the scheme you chose.
For example, if you invest Rs. 1,000 every month, the number of units purchased depends on the scheme's NAV on the applicable investment date.
SIP is not a separate mutual fund category. It is simply a method of investing. The value of your investment depends on the performance of the selected mutual fund scheme. Returns are not guaranteed.
The Bajaj Broking website offers 4,000+ mutual fund schemes, with a minimum SIP amount of Rs. 100 per month, subject to applicable scheme terms. SIP and lumpsum investment options are available for most schemes.
How does an SIP work?
SIP stands for Systematic Investment Plan. It is a way of investing a fixed amount in a mutual fund at regular intervals, usually every month. You decide the amount and frequency, and each instalment buys units of the scheme you chose.
NAV, or Net Asset Value, represents the value of one unit of a mutual fund scheme. Because NAV changes, the same SIP amount can purchase different numbers of units at different times.
For example, an SIP of Rs. 10,000 buys 125 units when the NAV is Rs. 80. If the NAV is Rs. 100, the same amount buys 100 units.
This regular investing process spreads purchases across different market levels. It can reduce the need to decide when to invest a large amount, but it does not eliminate the possibility of losses.
Why do investors use SIPs?
SIPs can make regular investing easier to manage, particularly when you receive income regularly and want to invest towards a financial goal.
How does compounding help an SIP?
Compounding means that returns earned on an investment can generate further returns when they remain invested. Over a longer period, this can increase the effect of growth on the accumulated investment.
However, mutual fund returns are market-linked, so compounding does not guarantee a particular final value.
Example: If you invest Rs. 5,000 every month for 10 years and the fund grows at an assumed 12% a year, you invest Rs. 6,00,000 and it could grow to about Rs. 11,61,695. Returns are not guaranteed; this is an illustration.
What is rupee-cost averaging?
Rupee-cost averaging refers to investing a fixed amount regularly despite changes in the investment price.
When the NAV is lower, the same amount can buy more units. When it is higher, it buys fewer units. Over multiple instalments, purchases are therefore spread across different NAV levels.
This approach can reduce the need to time the market, but it cannot prevent losses or guarantee profits.
| Month | SIP amount | NAV | Units bought |
| Month 1 | Rs. 5,000 | Rs. 50 | 100 |
| Month 2 | Rs. 5,000 | Rs. 40 | 125 |
| Month 3 | Rs. 5,000 | Rs. 62.50 | 80 |
| Total | Rs. 15,000 | - | 305 |
Your average cost is about Rs. 49.18 a unit (Rs. 15,000 ÷ 305), lower than the average NAV of about Rs. 50.83.
What are the benefits of investing through SIP?
SIPs offer practical benefits related to regular investing and managing contributions over time.
- Regular investing: Fixed contributions can help create an investing habit.
- Accessible starting point: You can start with a relatively small amount, subject to the scheme's minimum.
- Rupee-cost averaging: Investments are made across different NAV levels.
- Potential compounding: Staying invested can allow returns to generate further returns.
- Convenience: Applicable auto-debit arrangements can simplify regular contributions.
- Choice of schemes: SIPs can be used with different mutual fund categories, depending on scheme availability.
An SIP itself does not make an investment risk-free. The underlying mutual fund determines the investment's market exposure. You can also learn about market volatility to understand how changing prices can affect investments.
No lock-in in most schemes: You can redeem units of most open-ended schemes on any business day; ELSS (tax-saving) funds are the main exception, with a 3-year lock-in for each instalment.
When can an SIP be useful?
An SIP may be useful when you want to invest regularly towards a defined financial goal rather than invest a large amount at one time.
Consider:
- Financial goal: Identify what you are investing for and the amount you may need.
- Investment horizon: Choose a period that matches your goal and the scheme.
- Available funds: Select an amount that does not affect essential expenses.
- Risk level: Consider how much fluctuation you can accept.
- Regularity: Make sure the contribution is sustainable within your budget.
Starting earlier gives an investment more time to remain invested, but it does not guarantee a particular return.
What types of SIPs are available?
Different SIP structures can provide different ways to manage regular investments. Availability depends on the mutual fund scheme and platform.
- Regular SIP: Invests a fixed amount at regular intervals.
Top-up or step-up SIP: Increases the SIP amount at predetermined intervals.
For example, Rs. 10,000 a month for 20 years at an assumed 12% could grow to about Rs. 99.9 lakh; raising it by 10% every year could take it to about Rs. 1.99 crore. Try the step-up SIP calculator.
- Flexible SIP: Allows changes to the contribution according to applicable terms.
- Multiple SIP: Uses separate SIPs for more than one mutual fund scheme.
- Perpetual SIP: An SIP with no fixed end date. Since 1 October 2023, new SIP mandates need an end date of up to 30 years, so new SIPs can no longer be truly perpetual; ones set up before then continue.
- Trigger SIP: Uses a specified trigger or condition for an investment.
Check the applicable scheme and platform conditions before selecting a particular SIP structure.
How should you choose a mutual fund for an SIP?
An SIP only determines how you invest. You still need to select a mutual fund scheme that suits your financial circumstances and objective.
Consider the fund category, investment strategy, risk level, investment horizon, past performance, expense ratio, and applicable exit load. Past performance does not guarantee future returns.
You can read more about choosing mutual funds before evaluating schemes.
The Bajaj Broking website offers equity, debt, hybrid, ELSS, thematic, and NFO categories. When assessing risk, also check the SEBI Riskometer, which uses six levels: Low, Low to Moderate, Moderate, Moderately High, High, and Very High. As a rough guide, equity funds suit goals 5 years or more away, hybrid funds 3 to 5 years, and debt or liquid funds less than 3 years.
How can you start an SIP?
The basic process involves selecting the scheme, deciding the contribution, completing KYC, and setting up the applicable payment instructions.
- Define your financial goal and investment horizon.
- Select a mutual fund based on your requirements and risk level.
- Decide an SIP amount that fits your budget.
- Select the available investment frequency and duration.
- Complete the required KYC formalities.
- Set up the applicable payment or auto-debit instruction.
- Track the investment and review it against your financial goal.
KYC compliance is required for mutual fund investments, including SIP registrations, under applicable SEBI requirements.
Documents you need: PAN card, Aadhaar (for KYC), and your bank account details for the auto-debit.
How can an SIP calculator help?
An SIP calculator estimates the possible future value of regular investments based on inputs such as the monthly investment, assumed return, and investment period.
You can use the SIP calculator from Bajaj Finance to compare different contribution amounts and investment periods. The result is an estimate, not a guaranteed outcome, because mutual fund returns are market-linked.
If you want to compare a one-time investment with regular contributions, the lumpsum calculator can help illustrate different assumptions.
What should you consider before starting an SIP?
Before starting, assess the investment beyond the monthly contribution.
- Goal: Know what the investment is intended to achieve.
- Risk: Review the scheme's Riskometer and underlying investments.
- Horizon: Match the investment period with your financial objective.
- Performance: Review historical performance without treating it as a return guarantee.
- Costs: Understand the expense ratio and other applicable charges.
- Tax: Gains are taxed when you redeem, based on the fund type and how long each instalment was held.
- Affordability: Choose an amount you can sustain without affecting essential expenses.
You can also review the expense ratio when comparing similar mutual fund schemes.
Can SIP investments lose money?
Yes. SIP investments can lose value because the underlying mutual fund is market-linked. Regular contributions do not protect the investment from market declines.
The SEBI Riskometer can help you understand the risk level assigned to a mutual fund scheme. However, the Riskometer should be considered alongside the scheme's portfolio, investment strategy, investment horizon, and your own risk tolerance.
Rupee-cost averaging can spread purchases across different NAVs, but it cannot guarantee a profit or prevent a fall in the value of your investment.
Is SIP better than lumpsum investing?
SIP and lumpsum investing are different methods of investing in mutual funds.
With an SIP, you invest a fixed amount at regular intervals. With a lumpsum investment, you invest a larger amount at one time.
Neither method is automatically suitable for every investor. The appropriate approach depends on your financial goal, available funds, investment horizon, and ability to tolerate market fluctuations.
| Point | SIP | Lumpsum |
| How you invest | A fixed amount every month | One larger amount at once |
| Market timing | Not needed; you buy at many prices | The whole amount goes in at one price |
| Suits | People with a regular income | People with a large amount ready to invest |
| Minimum | From [Rs. 100] a month in some schemes | Usually higher, as set by the scheme |
| Growth | Builds up over time | The full amount grows from day one |
What if you miss, pause, or stop an SIP?
Here is what happens if you miss, pause, or stop an SIP:
- Missed instalment: No units are bought for that month, and the SIP usually continues the next month. Your bank may charge a fee for the failed auto-debit. If several instalments fail in a row (often 3), the fund house may cancel the SIP.
- Pause: Many schemes let you pause for a few months; ask for it before your SIP date to avoid a failed debit.
- Stop: Stopping an SIP does not sell your units; the money already invested stays invested until you redeem it.
How are SIP returns taxed?
Each SIP instalment counts as a separate investment with its own holding period, and the oldest units are sold first when you redeem.
Equity funds: Gains on units held for more than 12 months are taxed at 12.5% on gains above Rs. 1.25 lakh in a financial year. Gains on units held for 12 months or less are taxed at 20%.
Debt funds bought on or after 1 April 2023: Gains are taxed at your income tax slab rate.
ELSS: SIPs in ELSS funds can be claimed as a deduction of up to Rs. 1.5 lakh a year, only under the old tax regime, and each instalment is locked in for 3 years.
These rules apply for FY 2026-27.
Conclusion
An SIP is a method of investing a fixed amount in a mutual fund at regular intervals. It can help establish investment discipline, spread purchases across different NAV levels, and provide an opportunity for compounding over time.
However, SIP does not guarantee returns or eliminate market risk. Your financial goal, investment horizon, chosen mutual fund, costs, taxation, and risk level should all be considered before investing.
Last reviewed: September 2026
Mutual funds are subject to market risk. Please read the scheme-related documents carefully before investing.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
SIP basics
Managing an SIP
SIP suitability
What happens if the NAV changes after I start an SIP?
When the NAV changes, the number of units purchased by each SIP instalment also changes. A fixed Rs. 1,000 contribution buys more units when the NAV is lower and fewer when it is higher. This is the basic mechanism behind rupee-cost averaging, although it does not guarantee profits or protect against investment losses.
Can I change my SIP amount after starting it?
Yes, in most schemes. You can increase, reduce, pause or stop an SIP, subject to the scheme's minimum amount and rules. On the Bajaj Finserv platform, go to [path] to make changes; changes usually apply from the next SIP date if made [X] working days before it. A step-up facility can raise your SIP automatically every year.
Is an SIP suitable for every financial goal?
An SIP is a method of investing, so its suitability depends on the mutual fund selected and the goal being pursued. The investment horizon, required liquidity, risk tolerance, and expected use of the money should be considered. A short-term requirement may need a different investment approach from a long-term wealth-building objective.
What is the full form of SIP?
SIP stands for Systematic Investment Plan. It is a way of investing a fixed amount in a mutual fund at regular intervals, usually every month.
What is the minimum amount to start an SIP?
Some schemes let you start with as little as Rs. 100 a month, while many ask for Rs. 500. Each scheme sets its own minimum, which you can see on the scheme page.
Do SIPs give tax benefits?
Only SIPs in ELSS (tax-saving) funds give a deduction, of up to Rs. 1.5 lakh a year under the old tax regime, with a 3-year lock-in for each instalment. Gains from all other SIPs are taxed when you redeem.
Is SIP safe?
An SIP is a safe way to invest regularly, but it does not make the fund safe. Your returns depend on the mutual fund you choose and can be negative, especially over short periods. Check the scheme's Riskometer and invest for a period that suits the fund type.
Can I have more than one SIP?
Yes. You can run several SIPs in different funds, or more than one SIP in the same fund, for different goals.
Do I need a demat account to start an SIP?
No. Mutual fund units can be held without a demat account; they are shown in your account statement from the fund house.
Which date should I choose for my SIP?
Choose a date a few days after your salary or income reaches your account, so the auto-debit does not fail. Over the long term, the SIP date makes little difference to returns.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.