








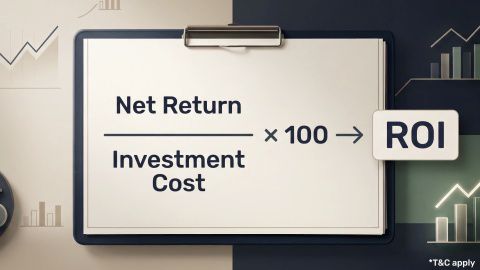
Return on Investment (ROI)
-
In Summary
A fixed deposit (FD) is a savings option that lets you invest a lump sum for a specified tenure and earn interest at an agreed rate. Depending on the deposit, you can receive interest at regular intervals or accumulate it until maturity. Your returns depend on the interest rate, tenure, payout option and applicable terms.
Before choosing an FD, consider these key factors:
- Compare interest rates: Check the rates available for your preferred tenure and payout option.
- Assess the issuer: Review its credit rating and understand whether deposit insurance applies.
- Check withdrawal conditions: Understand the rules and potential penalties for premature withdrawal.
- Consider tax and inflation: Account for tax on interest and whether your returns may keep pace with rising prices.
- Align the FD with your goals: Choose a tenure and payout option that suit your financial needs.
A fixed interest rate can make returns more predictable, but it does not make every FD risk-free or guarantee that your money will outpace inflation.
How does a fixed deposit help you earn predictable returns?
-
A fixed deposit is a financial product in which you place a lump sum with a bank or an eligible deposit-taking financial institution for a specified period. The deposit earns interest according to the rate and terms agreed when you open it.
For example, if you place money in an FD with a fixed interest rate, the applicable rate generally remains unchanged for that deposit’s tenure, even if the issuer changes rates for new deposits later. This makes it easier to estimate your interest earnings and plan for a future expense.
Your actual return depends on several factors:
- Deposit amount: The amount you invest.
- Interest rate: The rate applicable to your chosen tenure and depositor category.
- Tenure: How long you keep the deposit.
- Interest payout option: Whether interest is paid periodically or accumulated until maturity.
- Tax treatment: The tax payable on your interest income, based on applicable tax rules.
An FD may be useful when you want greater certainty about the interest rate than market-linked investments generally provide. However, the level of risk also depends on whether the deposit is with a bank or a non-banking financial company (NBFC), among other factors.
What are the FD interest rates and tenure options?
-
FD interest rates differ across issuers and may also vary by tenure, deposit amount, depositor category and payout frequency. Compare the rate applicable to your specific deposit rather than relying only on the highest advertised rate.
As published for Bajaj Finance Fixed Deposits, the following annualised rates for interest payable at maturity were effective from 7 October 2026 for eligible deposits of Rs. 15,000 to Rs. 3 crore.
Deposit tenure Customers below 60 years Senior citizens 12–17 months 6.80% p.a. 7.20% p.a. 18–30 months 7.00% p.a. 7.40% p.a. 31–60 months 7.75% p.a. 8.15% p.a. These are published rates for the specified deposit and payout category, not a guarantee that the same rates will apply to every FD. Rates and product terms can change. Check the current rate card and applicable terms before investing.
The rate you receive may differ if you select monthly, quarterly, half-yearly or annual interest payouts instead of receiving the accumulated amount at maturity.
How should you compare FD interest rates?
A higher headline rate does not necessarily mean that a deposit is the right choice for you. Compare the following before making a decision:
- The applicable rate: Confirm the rate for your tenure and age category.
- The payout method: Check whether the quoted rate applies to cumulative or non-cumulative deposits.
- The tenure: Ensure that the maturity date aligns with when you may need the money.
- The issuer: Understand the institution’s financial position, credit rating and applicable regulatory requirements.
- The terms: Review premature withdrawal rules, renewal conditions and other applicable charges or restrictions.
- Tax: Consider the effect of tax on your interest earnings.
You can use the issuer’s FD calculator to estimate the maturity amount or periodic interest payment for the amount, tenure and payout option you select.
What are the main benefits of a fixed deposit?
An FD may suit savers who value a predetermined interest rate and a defined investment period. Its main benefits include the following:
1. Predictable interest earnings
The interest rate agreed for an FD generally remains fixed for the deposit’s tenure. This helps you estimate your interest income or maturity amount, subject to the product’s terms and applicable conditions.
2. Choice of tenure
FDs offer different tenure options. You can compare available terms to find one that aligns with a planned expense, such as education fees, a major purchase or another financial commitment.
3. Flexible interest payouts
Depending on the product, you may choose to receive interest periodically or allow it to accumulate until maturity. Periodic payouts may suit people who need regular income, while cumulative deposits may suit those saving towards a future lump-sum expense.
4. Options for different depositor categories
Some FD providers offer different rates or terms for senior citizens and other eligible customer categories. Always check the conditions that apply to your category before booking a deposit.
5. Easier financial planning
Since the rate and tenure are known at the time of booking, an FD can help you plan around a specific date or expected payment. However, you should also consider access to emergency funds and the possibility that your needs may change before maturity.
How can you choose an FD that suits your financial goals?
The right FD depends on when you need the money, how you want to receive interest and how much risk you are willing to take.
Consider these steps before investing:
- Identify your goal. Decide whether you are saving for a short-term expense, building a reserve or setting aside money for a future requirement.
- Choose a suitable tenure. Avoid locking away money for longer than you can reasonably afford if you may need it early.
- Compare rates for the same tenure. Review equivalent payout options rather than comparing a cumulative rate with a monthly payout rate.
- Assess the issuer. Check whether the institution is authorised to accept deposits, where applicable, and review its credit rating and financial disclosures.
- Understand liquidity. Read the premature withdrawal terms and check whether a loan against the deposit is available and what it would cost.
- Account for tax and inflation. The interest you receive after tax may have less purchasing power if prices rise faster than your effective return.
- Keep emergency savings accessible. Avoid putting all your available savings into deposits that may be difficult or costly to access early.
These checks can help you choose an FD based on your circumstances rather than focusing on the highest displayed rate alone.
What is the difference between a bank FD and an NBFC FD?
Banks and eligible non-banking financial companies (NBFCs) may both offer fixed deposits, but their regulatory treatment and deposit protection differ.
| Factor | Bank FD | NBFC FD |
|---|---|---|
| Interest rate | Depends on the bank, tenure and deposit terms | Depends on the NBFC, tenure and deposit terms |
| Deposit insurance | Eligible deposits with insured banks are covered by DICGC, subject to its rules and limits | NBFC deposits are not covered by DICGC deposit insurance |
| Risk assessment | Check the bank’s status, terms and applicable protections | Check the NBFC’s authorisation to accept public deposits, credit rating, financial disclosures and terms |
| Interest payout | Depends on the bank’s available options | Depends on the NBFC’s available options |
| Early access | Subject to the bank’s premature withdrawal conditions | Subject to the NBFC’s premature withdrawal conditions |
DICGC insurance covers eligible deposits with insured banks up to Rs. 5 lakh per depositor per bank, including principal and interest, subject to the same-right-and-same-capacity rules. This insurance does not cover deposits mobilised by NBFCs.
An NBFC’s credit rating can help you assess its ability to meet its deposit obligations, but it is not a guarantee of repayment. RBI registration also does not mean that the Reserve Bank guarantees the repayment of an NBFC’s deposits.
Are fixed deposits risk-free?
No investment should be treated as entirely risk-free. An FD can provide a predetermined interest rate, but the risks depend on the issuer and the terms of the deposit.
For example, eligible deposits with insured banks receive DICGC protection within the applicable limit. Company deposits accepted by NBFCs do not receive this protection, so depositors need to assess the issuer and understand the associated risk.
Before investing, check the following:
- Whether the institution is authorised to accept the type of deposit it is offering.
- The institution’s credit rating and the meaning of that rating.
- The terms governing interest payments and repayment of principal.
- Whether deposit insurance applies.
- The rules and financial consequences of premature withdrawal.
- Whether the expected return is appropriate for the risk involved.
Be cautious of offers that promise unusually high returns with no risk. For investments in securities markets, the National Stock Exchange cautions against promises of assured or fixed returns. Understand the product and verify the provider before committing your money.
How does inflation affect your FD returns?
Inflation refers to an increase in the general price level over time. It reduces the amount of goods and services that the same sum of money can buy.
Even if an FD earns the interest agreed at the time of investment, its purchasing power may not increase by the same amount. The return remaining after tax may be lower still.
For example, suppose an investment earns a nominal return of 7% over a year while inflation is 5%. A simplified estimate of the return after inflation is:
Real return = (1 + nominal return) / (1 + inflation rate) − 1
Using these illustrative figures:
Real return = (1.07 / 1.05) − 1 ≈ 1.90%
This is an illustrative calculation before tax and assumes the stated annual rates. Actual purchasing-power outcomes depend on the return earned, inflation and tax treatment.
When comparing FDs, consider both the amount you expect to receive and what that money may be able to buy when the deposit matures.
Check out different FD Rates
How are FD interest earnings taxed?
FD interest is generally taxable under the applicable income-tax rules. The tax you pay depends on your circumstances and the rules in force for the relevant financial year.
Tax deducted at source (TDS), where applicable, is a tax deduction made by the institution when interest is credited or paid under the relevant rules. TDS is not necessarily the final tax liability on your interest income.
Before investing, consider:
- The interest you expect to earn during the financial year.
- Whether TDS applies to your deposit and circumstances.
- Your applicable income-tax slab and tax regime.
- The tax forms and reporting requirements currently in force.
Do not assume that a TDS deduction means no further tax is payable, or that no TDS means the interest is tax-free. Check current Income Tax Department guidance or consult a qualified tax professional if you need advice for your circumstances.
What should you know about premature FD withdrawal?
Premature withdrawal means closing a fixed deposit before its scheduled maturity date. Whether this is permitted, and how much interest you receive, depends on the product’s terms and applicable rules.
An early withdrawal may result in reduced interest or other restrictions. Some deposits may not allow withdrawal during an initial period, except in specified circumstances.
Before opening an FD, check:
- When premature withdrawal is permitted.
- How interest is recalculated if you close the deposit early.
- Whether any penalty or other reduction applies.
- Whether a loan against the deposit is available and what its interest rate and fees are.
A loan against an FD is borrowing, not an additional investment return. Compare the borrowing cost and repayment obligations before choosing this option.
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
A fixed deposit can help you plan for future expenses by providing an agreed interest rate for a defined period. The right choice depends on the rate available for your tenure, the interest payout option, the issuer’s creditworthiness, your need for access to funds and the tax treatment of your interest.
Before investing, compare like-for-like FD options and review the applicable terms. Check whether deposit insurance applies, understand the limits of credit ratings and consider how inflation may affect the purchasing power of your returns. These steps can help you assess whether an FD fits your financial goals and risk tolerance.
Locate to your nearest FD branch

Related Articles
Frequently Asked Questions
Overview
Can a fixed deposit provide predictable returns?
Yes. An FD generally offers an interest rate agreed at the time of booking for the chosen tenure. This makes the interest easier to estimate than returns from market-linked investments. However, the issuer, product terms, payout option and tax treatment still matter. Predictable interest does not mean that every FD is risk-free or that its return will necessarily exceed inflation.
What is the minimum amount required to open a Bajaj Finance FD?
The published Bajaj Finance Fixed Deposit product page lists a minimum deposit of Rs. 15,000 for the applicable product. Eligibility and terms can vary by depositor category and product conditions. Check the current official FD page before investing to confirm the minimum amount and any other requirements that apply to you.
What is the maximum tenure available for a Bajaj Finance FD?
The published Bajaj Finance Fixed Deposit product offers tenures from 12 months to 60 months, subject to the applicable product terms. The interest rate depends on the selected tenure, depositor category and payout option. Review the current rate card before booking because rates and product conditions may change.
Do senior citizens receive higher FD interest rates?
Some FD providers offer higher interest rates to eligible senior citizens. The difference depends on the provider, tenure and payout option. Check the current rate table and eligibility conditions rather than assuming that every FD offers the same additional rate. Bajaj Finance offers a senior citizen FD at 8.15% p.a.
Are NBFC fixed deposits covered by DICGC insurance?
No. DICGC deposit insurance does not cover deposits mobilised by NBFCs. Eligible deposits with insured banks are covered up to Rs. 5 lakh per depositor per bank, including principal and interest, subject to DICGC rules. Before placing money in an NBFC FD, assess the institution, its credit rating, its authorisation to accept deposits and the terms of the deposit.
Is FD interest taxable?
FD interest is generally taxable under applicable income-tax rules. TDS may be deducted where the relevant conditions are met, but TDS is not necessarily the final tax payable. Your final liability depends on your circumstances and the rules in force. Check current Income Tax Department guidance when planning your investment.
Is a loan facility available against the FD account at Bajaj Finance?
Yes, eligible investors can access a loan against Bajaj Finance Fixed Deposit without necessarily closing the deposit prematurely. The facility can provide funding up to 75% of eligible FD value, subject to applicable terms and conditions.
Who all are eligible to open a Bajaj Finance Fixed Deposit Account?
Resident Indian individuals meeting applicable KYC and product requirements can open a Bajaj Finance Fixed Deposit. Senior citizens can also invest and may qualify for additional interest benefits based on their age and applicable terms.
Does Bajaj Finance provide an auto-renewal facility for fixed deposits?
Yes, an auto-renewal facility is available for Bajaj Finance Fixed Deposit, subject to the selected instructions and applicable conditions. Investors should review renewal rates before maturity because prevailing renewal rates can differ from their existing contracted FD rates.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.