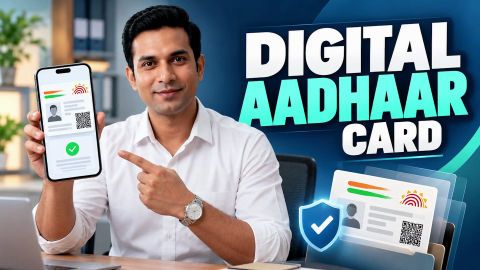
The app keeps a record of authentications and updates linked to your Aadhaar. Check it every month or 2. An entry you do not recognise, such as an authentication from a service you have not used, is a sign of possible misuse. Report it to UIDAI on its helpline, 1947, and lock your biometrics at once.
Deepak's KYC
Deepak, 28, leads a call centre team in Jaipur on a Rs. 34,000 salary, with a CIBIL score of 729. Before applying for a loan, he moved from mAadhaar to the new Aadhaar app, checked his authentication history and confirmed his mobile number was current, so e-KYC would go through. He borrowed Rs. 88,000 for his mother's hearing aids and a new refrigerator at an illustrative 16% per annum, choosing between a 12-month and an 18-month equated monthly instalment (EMI).
EMI = P × R × (1 + R)^N ÷ [(1 + R)^N − 1]. Here P = Rs. 88,000, R = 16 ÷ 1,200 and N = months.
| Tenure | Monthly EMI (Rs.) | Total interest (Rs.) | EMI as share of salary (%) |
|---|
| 12 months (1 year) | 7,984 | 7,812 | 23.5 |
| 18 months (1.5 years) | 5,531 | 11,565 | 16.3 |
Last updated: 27th October, 2026
Over 12 months, the EMI would claim close to 24% of his pay, so he spread the cost. Over 18 months, it falls by Rs. 2,453, with Rs. 3,753 more interest. His details in the Aadhaar app matched his loan documents, so verification went through the first time. Rs. 3,634 is the most processing could cost. Deepak chose 18 months.
What can delay approval: a CIBIL score below 650 or existing EMIs that take up a large share of your income. Names or addresses that do not match across documents, and more than one loan application in the same month, can also slow it down.
Aadhaar details up to date? With a Bajaj Finance Personal Loan, you can borrow Rs. 40,000 to Rs. 75 lakh, subject to eligibility. Check your loan offer with your phone number and a one-time password (OTP) → apply online → receive funds within 24 hours* of approval.