Flexi Hybrid Loan: Lower EMI Now, Higher EMI Later

Flexi Hybrid Loan: Lower EMI Now, Higher EMI Later

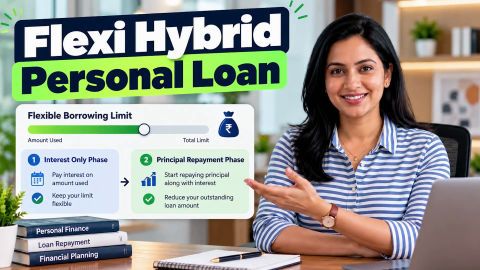
A Flexi Hybrid Loan can offer lower EMIs during an initial interest-only period, followed by higher EMIs that cover both principal and interest.

Rs. 40,000 - Rs. 75 lakh

You may be eligible for a pre-approved offer

Enter mobile and OTP | Check offer | No branch visit needed


In summary

A Flexi Hybrid Loan changes when you repay the principal. The lower initial payment can ease short-term cash flow, but it does not necessarily reduce the total borrowing cost.


  • Initial phase: Interest-only EMIs may apply for up to 36 months, subject to the applicable loan terms.
  • Subsequent phase: EMIs increase when principal repayment begins.
  • Total interest: Deferring principal repayment can increase the interest paid over the loan tenure.
  • Part-prepayment: No part-prepayment charge involved for Bajaj Finance Flexi Hybrid Loans.

The right choice depends on whether you can afford the later EMI and whether the repayment structure suits your cash flow. You can check your loan offer from Bajaj Finance and review the actual terms available to you. Approval and disbursal remain subject to eligibility, verification and applicable terms.

What is a Flexi Hybrid Loan, and how does it work?

A Flexi Hybrid Loan is a personal loan variant that separates repayment into an initial interest-only phase and a subsequent principal-and-interest phase, subject to the applicable terms. This differs from a standard Term Loan, where scheduled EMIs generally cover principal and interest throughout the repayment tenure.


Three terms explain how the repayment structure works:


  • Principal: The amount borrowed that remains to be repaid.
  • Interest-only EMI: A monthly payment covering interest on the amount used, without scheduled principal repayment during that phase.
  • Step-up: The increase in the monthly EMI when principal repayment begins.

The initial phase can last up to 36 months. However, actual duration depends on the loan terms. The subsequent phase begins when the initial phase ends, and the EMI then covers both principal and interest.


Interest-only payments do not mean the principal is being repaid gradually. Unless you make a qualifying part-prepayment, the principal used during the initial phase remains outstanding for the subsequent repayment period.


The structure can therefore reduce the initial monthly payment while shifting more of the principal repayment into the remaining tenure. To assess its value, compare the payment in each phase and the total interest with the cost of a Term Loan.

Show More Show Less

How does the EMI change, and what does the loan cost?

The initial EMI covers interest on the amount used. Once principal repayment begins, the EMI increases to cover both principal and interest over the remaining repayment tenure.


The following illustration assumes a Rs. 4 lakh loan, an interest rate of 14% per annum and a total tenure of 72 months. It assumes the full amount is used, with interest-only payments for the first 36 months and principal-and-interest payments for the next 36 months. These are illustrative calculations, not a personalized Bajaj Finance offer.


Repayment phaseWhat the EMI coversIllustrative monthly EMI (Rs.)Principal repaid during phase
Initial tenure, first 36 monthsInterest on the amount used4,667Nil
Subsequent tenure, next 36 monthsPrincipal and interest13,671Rs. 4 lakh, assuming no earlier principal repayment

Illustrative calculations. Last reviewed: 23 October 2026.


The monthly payment increases by approximately Rs. 9,004 when principal repayment begins. The initial EMI is lower because it does not include scheduled principal repayment. The later EMI must repay the outstanding principal over the remaining tenure.

Show More Show Less

How does it compare with a Term Loan?

A Term Loan spreads principal repayment across the loan tenure, with each scheduled EMI covering principal and interest. A Flexi Hybrid Loan defers scheduled principal repayment during its initial interest-only phase, which can increase total interest.


The table compares both structures using the same principal, interest rate and overall tenure. The part-prepayment scenario assumes Rs. 1 lakh is paid from the borrower's own funds before the subsequent phase begins. All figures exclude processing fees, annual maintenance charges and other applicable costs.


Loan structureEMI, years 1 to 3 (Rs.)EMI, years 4 to 6 (Rs.)Total interest (Rs.)
Term Loan, 72 months8,2428,2421,93,445
Flexi Hybrid Loan, without part-prepayment4,66713,6712,60,158
Flexi Hybrid Loan, with Rs. 1 lakh part-prepayment before the step-up4,66710,2532,37,118

Illustrative calculations. Last reviewed: 23 October 2026.


Under these assumptions, the Flexi Hybrid Loan without part-prepayment incurs approximately Rs. 66,713 more interest than the Term Loan. A Rs. 1 lakh part-prepayment reduces the illustrated Flexi Hybrid Loan interest by approximately Rs. 23,040 compared with the no-prepayment scenario. Its total interest remains higher than that of the Term Loan.


Part-prepayment reduces the outstanding principal used to calculate subsequent EMIs. Its effect on the later EMI and total interest depends on the amount prepaid, when the payment is made and the applicable repayment terms.

The lower initial EMI should be weighed against the later repayment and total interest. Before deciding whether this structure suits your budget, check your personal loan eligibility with Bajaj Finance and review the terms available to you.

Show More Show Less

When does a lower initial EMI make sense?

A lower initial EMI can suit you when your current cash flow is constrained but you can reasonably afford the higher EMI later. For example, a significant existing expense might end before principal repayment begins, or you might already have funds set aside for a part-prepayment.


The structure is less suitable when your income is uncertain, your budget leaves little room for savings or you would struggle to meet the later EMI. An expected bonus or salary increase should not be the only reason you choose a repayment structure with a higher future payment.


Use these checks before choosing:


Your situationWhat to consider
You need lower scheduled payments during the initial periodCheck whether the later EMI fits your expected budget.
You expect an existing EMI to endConfirm that the timing aligns with the start of principal repayment.
You plan to make a part-prepaymentBase the plan on funds you can reasonably set aside.
Your income is unlikely to increaseCompare the later EMI with the level EMI of a Term Loan.
You want the lowest overall borrowing costCompare total interest and all applicable charges, not just the initial EMI.

The deciding question is whether you can manage the subsequent EMI without relying on uncertain future income. A lower first payment is useful only when the full repayment plan remains affordable


Can you afford the step-up?

Karthik, 39, is a salaried software delivery manager in Mysuru. He earns Rs. 1,10,000 a month, has a CIBIL score of 775 and needs Rs. 4 lakh for school admission and home repairs. His car loan is due to end in two years.


Assume a 72-month tenure, an interest rate of 14% per annum and a 36-month interest-only phase. These figures are illustrative, not a Bajaj Finance offer.


Repayment scenarioMonthly EMI (Rs.)Share of monthly salary
Initial interest-only phase4,6674.2%
Subsequent phase, without prepayment13,67112.4%
Subsequent phase, after Rs. 1 lakh part-prepayment10,2539.3%

A Rs. 1 lakh part-prepayment could reduce Karthik’s later EMI by approximately Rs. 3,418 a month under these assumptions. However, he should confirm that the payment is affordable alongside his other expenses and compare the total interest and charges with a Term Loan.


Approval note: A CIBIL score alone does not establish eligibility. Existing EMIs, credit profile, document consistency and verification can also affect the outcome.

Show More Show Less

How can you apply for a Flexi Hybrid Loan with Bajaj Finance?

After comparing the repayment structures and checking whether the later EMI fits your budget, review the eligibility criteria, documents and charges for the specific offer available to you. Bajaj Finance Personal Loan has the following established criteria and application process. Confirm the current requirements and terms for the Flexi Hybrid Loan before applying.


Do you meet the eligibility criteria?


CriterionRequirement
NationalityIndian
Age21 years to 80 years.
Employed withPublic, private, or MNC.
CIBIL Score650 or higher.
Customer profileSelf-employed or Salaried


*You should be 80 years or younger at the end of the loan tenure.


Last reviewed: 23 October 2026.


Meeting these criteria does not guarantee approval. The application remains subject to verification, credit assessment and applicable terms. The supplied product information describes the Personal Loan as unsecured, with no collateral or guarantor required; confirm that this applies to the specific offer and variant. 


Which documents may you need?

The documents requested depend on your profile and application. The supplied product information lists the following documents, but not every applicant will need every item.


  • KYC documents: Aadhaar/ passport/ voter's ID/ driving license/ Letter of National Population Register/ NREGA job card
  • PAN card
  • Employee ID card
  • Salary slips of the last 3 months
  • Bank account statements of the previous 3 months
  • Piped gas bill
  • Pension order
  • Letter of Allotment of Accommodation Issued by Employer
  • Property / Municipal tax receipt
  • Utility bill
  • Phone bill
  • Real-time image / photograph


Confirm the final checklist during your application. Do not assume that every listed item is mandatory or that this list covers every document that could be requested.


Which are the applicable interest rate and charges for a Flexi Hybrid Loan?


The total cost includes interest and any applicable processing, facility, annual maintenance and full-prepayment charges. The table below retains the supplied figures and distinguishes the charges associated with the Flexi Hybrid Loan from charges that apply to the Term Loan.


ChargeSupplied amount or basis
Interest rate10% to 30.5% per annum, subject to applicable terms and customer eligibility
Processing feeUp to 4.13% of the loan amount, inclusive of applicable taxes
Bounce chargesRs. 700 to Rs. 1,200 per bounce
Penal chargeUp to 36% per annum on the overdue instalment
Part-prepayment, Flexi Hybrid LoanNo part-prepayment charge, according to the published charges information
Full prepayment, Flexi Hybrid LoanUp to  4.72% of the Dropline limit as per the repayment schedule on the date of full prepayment, inclusive of applicable taxes; verify the applicable terms
Flexi facility chargeRs. 11, inclusive of applicable taxes; confirm the amount applicable to the specific offer
Annual maintenance, Flexi Hybrid LoanUp to 0.472% (Inclusive Of Applicable Taxes) Of The Dropline Limit During Initial Tenure. 
Up to 0.295% (Inclusive Of Applicable Taxes) Of Dropline Limit during Subsequent Tenure

Last reviewed: 23 October 2026.


Read the Key Fact Statement (KFS), including the Annual Percentage Rate (APR), charges and repayment schedule, before accepting an offer. Include applicable fees and annual maintenance charges when comparing the total cost of a Flexi Hybrid Loan with a Term Loan.


How to apply for a Bajaj Finance Flexi Hybrid Loan?

You can apply for a Bajaj Finance Personal Loan by following these five steps, from submitting your details to completing verification and reviewing the available offer.
 

  1. Check your loan offer: Enter the required loan amount and repayment period, then select “CHECK LOAN OFFER”.
  2. Enter your details: Provide the requested personal, financial and employment information.
  3. Review the offer: Check the available loan amount, tenure, interest rate and EMI for both repayment phases.
  4. Complete verification: Submit the required KYC documents and verify your bank details.
  5. Complete the next steps: Follow the instructions provided by the loan specialist or application team.


Before accepting the offer, compare the total interest, processing fee, annual maintenance charges and other applicable costs.


Once you have reviewed these details, you can check your loan offer from Bajaj Finance. Approval and disbursal are subject to eligibility, verification and applicable terms

Show More Show Less

Key offerings: 3 loan types

Personal loan interest rate and applicable charges

Type of fee

Applicable charges

Rate of interest per annum

10% to 30.5% p.a.

Processing fees

Up to 4.13% of the loan amount (inclusive of applicable taxes).

Flexi Facility Charge

Term Loan – Not applicable

Flexi Loans –Up To Rs 1,999 To Up To Rs 18,999/- (Inclusive Of Applicable Taxes)

Will be deducted upfront from loan amount.

Bounce charges

Rs. 700 to Rs. 1,200/- per bounce

“Bounce charges” shall mean charges for (i) dishonor of any payment instrument; or (ii) non-payment of instalment (s) on their respective due dates due to dishonor of payment mandate or non-registration of the payment mandate or any other reason.

Part-prepayment charges

Full Pre-payment:

  • Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount as on the date of full pre-payment

  • Flexi Term (Dropline) Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

  • Flexi Hybrid Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

Part Pre-payment

  • Up to 4.72% (Inclusive of applicable taxes) of the principal amount of Loan prepaid on the date of such part Pre-Payment.

  • Not Applicable for Flexi Term (Dropline) Loan and Flexi Hybrid Term Loan.

Penal charge

Delay in payment of instalment(s) shall attract Penal Charge at the rate of up to 36% per annum per instalment from the respective due date until the date of receipt of the full instalment(s) amount.

Stamp duty (as per respective state)

Payable as per state laws and deducted upfront from loan amount.

Annual maintenance charges

Term Loan: Not applicable

Flexi Term (Dropline) Loan:

Up to 0.295% (Inclusive of applicable taxes) of the Dropline limit (as per the repayment schedule) on the date of levy of such charges.


Flexi Hybrid Term Loan:

Up to 0.472% (Inclusive Of Applicable Taxes) Of The Dropline Limit During Initial Tenure. Up to 0.295% (Inclusive Of Applicable Taxes) Of Dropline Limit During Subsequent Tenure

Credit guarantee scheme feeUp to 1.18% p.a. (pro-rated daily till 31st March) (inclusive of all applicable taxes) of the loan amount
Credit guarantee scheme renewal feeUp to 1.18% p.a. (inclusive of all applicable taxes) on the outstanding loan amount as on April 01 of the subsequent Financial Year.
*Renewal Fee to be collected only for 3 subsequent financial years.
 
**If the Remaining Tenure is less than 12 months, the CG Fee in subsequent years shall be charged prorated.

Frequently asked questions

Repayment phases

Cost and affordability

When does the interest-only phase end?

The initial interest-only period can extend to 36 months, depending on the loan tenure and applicable terms. After that period, the EMI includes principal and interest, so check your repayment schedule for the exact step-up date and amount.

The published description of Bajaj Finance's Flexi loan variants states that interest is charged on the amount used, subject to the applicable terms. The amount used, repayment schedule and annual maintenance charges affect the total cost, so review the loan agreement and fee details rather than relying on the initial EMI alone.

A Flexi Hybrid Loan can cost more in total interest than a Term Loan because principal repayment is deferred during the initial interest-only phase. The difference depends on the loan amount, interest rate, tenure, repayment schedule and any part-prepayments. Compare the total interest and applicable charges for both options before choosing.

Check whether your budget can accommodate the subsequent EMI before accepting the loan. A part-prepayment can reduce the outstanding balance and subsequent EMI, but the result depends on the timing and amount of the prepayment and the applicable loan terms.

Show More Show Less

Disclaimer

Bajaj Finance Limited has the sole and absolute discretion, without assigning any reason to accept or reject any application. Terms and conditions apply*.


For customer support, call Personal Loan IVR: 7757 000 000