







Clear your overdue EMI
Clear your overdue EMI today – stop penalties & fix your credit
*Overdue charges include penalty interest and bounce fees as applicable. T&C apply.
In Summary
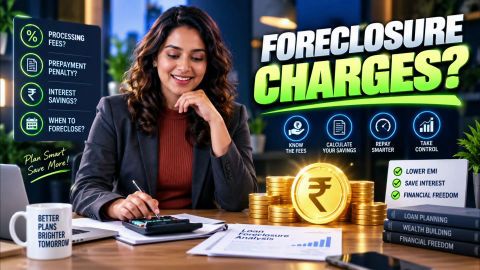
Check loan foreclosure charges and calculate your savings
CA loan prepayment can help you repay your loan early, but understanding the applicable charges and repayment terms is important. Review your loan agreement, confirm the amount payable, and assess how prepayment may affect your EMI, tenure and interest costs.
- Check your loan agreement for applicable prepayment or foreclosure charges and conditions.
- Calculate charges using the rate and calculation method specified in your loan terms.
- Review your outstanding principal, accrued interest and any other dues before making payment.
- Contact Bajaj Finance through an official channel if you need a breakdown of charges or a prepayment statement.
- Compare potential interest savings with applicable charges and confirm your updated loan status after payment.
What are CA loan prepayment charges?
CA loan prepayment charges depend on the terms of your loan agreement and the applicable lender policy. Before making a prepayment, review the charges applicable to your account and confirm the total amount payable.
The costs associated with CA loan prepayment may include:
- Prepayment charges: Applicable fees, if any, as specified in your loan agreement.
- Outstanding principal: The remaining loan amount to be repaid.
- Accrued interest: Interest payable up to the relevant payment date, as applicable.
- Other dues: Any pending instalments or applicable charges reflected in your account.
Check your loan agreement or request a prepayment statement through an official customer service channel to confirm the applicable charges and total amount due. Reviewing these details beforehand helps you understand the prepayment cost and plan your repayment accordingly.
How are CA loan prepayment charges calculated?
CA loan prepayment charges, if applicable, are calculated using the charge rate and calculation basis specified in the loan agreement. If the charges are based on a percentage of the amount being prepaid, the calculation is:
Prepayment charges = Prepayment amount × Applicable charge rate ÷ 100
For example, if the applicable charge rate is 2% and the eligible prepayment amount is Rs. 1,00,000, the charges would be Rs. 2,000, before any applicable taxes or other amounts.
The actual calculation may differ depending on your loan terms, including the amount on which the charge is applied. Check your loan agreement or contact Bajaj Finance through an official channel to confirm the applicable rate, calculation basis and final amount payable.
What factors affect CA loan prepayment charges?
Several factors can influence the prepayment charges applicable to a CA loan. These charges depend on the loan agreement and the lender’s terms, so they may vary across loan products. Understanding these factors helps you estimate the cost of repaying your loan early and check the amount payable before making a decision.
- Outstanding loan amount: The remaining loan balance may affect the charge calculation, depending on the terms specified in the agreement.
- Type of prepayment: The applicable charges may differ between part-prepayment, which repays a portion of the outstanding principal, and full foreclosure, which settles the loan before the end of its tenure.
- Applicable charge rate: If charges are calculated as a percentage, the rate specified in the loan agreement determines the amount payable.
- Calculation method: The charges may be calculated on the amount being prepaid or another basis specified in the agreement.
- Loan agreement conditions: The agreement may define when prepayment charges apply and specify any relevant conditions or restrictions.
Before proceeding, review your loan agreement and repayment details to understand how the charges are calculated. Confirm the applicable rate, calculation basis and total amount payable with your lender. This helps you assess the cost of early repayment and make an informed decision based on your financial requirements.
How to check applicable prepayment charges on your CA loan?
You can check the applicable prepayment charges on your CA loan by reviewing your loan agreement, repayment details and the outstanding balance shown in your account. The charges may depend on whether you plan to repay part of the outstanding principal or foreclose the loan before the end of its tenure. Checking these details in advance helps you understand the cost of early repayment and the total amount payable.
Follow these steps:
- Sign in to your account: Visit the official Bajaj Finance website or open the Bajaj Finance App and sign in using your registered mobile number and OTP.
- Select your CA loan: Go to the My Relations or Loans section, where available, and select the relevant loan account.
- Review your loan details: Check the outstanding balance, repayment details and any available information about prepayment or foreclosure charges.
- Check your loan agreement: Review the agreement for the applicable charge rate, calculation basis and conditions related to early repayment.
- Raise a service request if needed: If the charges are not clearly displayed, go to Help and Support and raise a request, where the option is available. Ask for confirmation of the applicable charges and the total amount payable for part-prepayment or foreclosure.
- Confirm the amount before payment: Review the amount confirmed by the lender before proceeding with the transaction.
The applicable prepayment charges should be confirmed against your loan agreement and account details before you make an early repayment. If any information is unclear or unavailable online, contact Bajaj Finance through an official service channel and request a breakdown of the charges.
How does prepayment affect your CA loan EMI and tenure?
Part-prepayment reduces the outstanding principal when you apply the payment toward it, but the effect on your EMI and tenure depends on the applicable loan terms and repayment arrangement. Full prepayment involves settling the amount required to close the loan early.
Consider the following differences:
| Aspect | Part-prepayment | Full prepayment |
| Outstanding loan | Reduces the principal, subject to payment adjustment | Settles the amount required for early closure |
| Future EMIs | Continue according to the applicable repayment schedule | Regular EMIs generally end after the loan is closed and the closure is confirmed |
| Loan tenure | May change if the repayment schedule is revised | The loan is intended to close before the scheduled end date |
| Charges | Applicable part-prepayment charges may apply | Applicable foreclosure charges may apply |
| Account status | The loan remains active | Closure should be confirmed after the payment is processed |
Prepayment may reduce the interest payable over the remaining tenure, depending on the loan terms, timing, and revised repayment schedule. However, savings may not outweigh applicable charges in every situation. Review the financial impact before deciding whether to make a part-payment or close the loan early.
Loan support made easy — Read on
Frequently Asked Questions
CA Loan Prepayment Charges
CA Loan Prepayment Process
What documents should I keep after making a CA loan prepayment?
Keep the payment receipt, transaction confirmation and updated loan statement after making a prepayment. These records help you verify that the payment was received and correctly reflected in your loan account.
What happens if my CA loan prepayment is not reflected in my account?
If your prepayment does not appear in your loan account, check the transaction status and bank statement first. If the amount was debited but remains unreflected, raise a service request with the payment date and transaction reference.
How do I confirm that my CA loan foreclosure is complete?
Review your loan account status after the final payment has been processed. Request an updated statement and the applicable loan closure document through an official service channel to confirm that the outstanding amount has been settled and the account is closed.
What should I do if the prepayment amount differs from my calculation?
Compare your calculation with the lender's prepayment statement and loan agreement. Check the charge rate, calculation basis, accrued interest and other applicable dues. If the difference remains unexplained, request a detailed breakdown before making the payment.
Does making a CA loan prepayment change my repayment schedule automatically?
A part-prepayment does not necessarily change your EMI or loan tenure automatically. The effect depends on your loan terms and the repayment arrangement. Check the revised repayment schedule, if applicable, to understand your remaining instalments.
Should I request a prepayment statement before closing my CA loan?
Requesting a prepayment or foreclosure statement helps you understand the amount required to settle the loan on the relevant date. Review its validity, applicable charges and outstanding dues before paying, as the final amount may change with time.
More Articles

Disclaimer
While care is taken to update the information, products, and services included in or available on our website and related platforms/websites, there may be inadvertent inaccuracies or typographical errors or delays in updating the information. The material contained in this site, and on associated web pages, is for reference and general information purpose and the details mentioned in the respective product/service document shall prevail in case of any inconsistency. Subscribers and users should seek professional advice before acting on the basis of the information contained herein. Please take an informed decision with respect to any product or service after going through the relevant product/service document and applicable terms and conditions. In case any inconsistencies observed, please click on reach us.
*Terms and conditions apply.