







An OTP will be sent to this number for verification

You may have a pre-approved offer
Enter required home loan amount
In summary
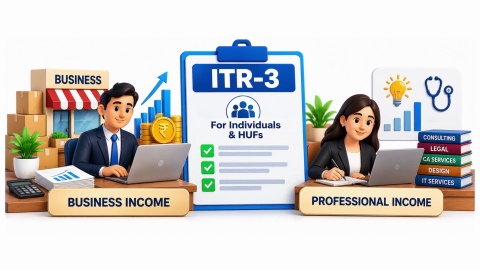
What is ITR 3 Form
Last updated: Sept 2026
ITR-2 covers capital gains and multiple properties, but stops short of business income. ITR-3 form picks up exactly where ITR-2 leaves off, adding business and professional income into the mix.
- Who must file it: individuals and HUFs with business or professional income, in any amount
- What it also covers: capital gains, multiple house properties, and foreign income, all within the same form
- Books of account: required where turnover or income crosses specific thresholds under Section 44AA
- Tax audit: required for specific turnover thresholds under Section 44AB, filed alongside the return
Presumptive taxation alternative: businesses below certain turnover thresholds can use the simpler ITR-4 instead, if eligible
Confirm you have genuine business or professional income, not just multiple income sources, before settling on ITR-3 form specifically as your filing choice.
How is ITR-3 actually different from ITR-2 and ITR-4?
This is the genuine point of confusion for many filers with business income, since the boundaries between these 3 forms aren't always obvious at first glance. Business income is the specific factor that separates ITR-3 from ITR-2, while the scale and nature of that business separates ITR-3 from the simpler ITR-4.
Understanding the specific dividing line between these forms prevents choosing the wrong one. The realistic distinctions between the 3 forms are:
- ITR-2 accommodates capital gains and multiple properties, but not business or professional income at all
- ITR-3 accommodates business or professional income alongside capital gains and multiple properties, with detailed books of account
ITR-4 offers a simpler presumptive taxation route for smaller businesses below specific turnover thresholds, trading detail for simplicity
A business owner whose turnover exceeds ITR-4's presumptive taxation threshold, or who wants to claim actual expenses rather than a presumed profit percentage, needs the ITR-3 form specifically rather than the simpler alternative.
Show more
Show less
What schedules does ITR-3 actually require?
| Schedule | What it covers |
|---|---|
| Profit and Loss (Schedule P&L) | Detailed business or professional income and expenses |
| Balance Sheet | Assets and liabilities as of the financial year end |
| Capital Gains (Schedule CG) | Any capital asset sales during the year |
| House Property (Schedule HP) | Income from 1 or more properties |
| Depreciation (Schedule DPM/DOA) | Asset-wise depreciation for business assets |
The Profit and Loss and Balance Sheet schedules specifically require maintained books of account, which is the single biggest practical difference from the simpler forms most individual taxpayers are used to.
Show more
Show less
How do I prepare for and file ITR-3?
Five steps prepare a business owner's ITR-3 form submission before actual filing.
- Confirm your books of account are complete and current, since Schedule P&L and Balance Sheet depend directly on them.
- Determine whether a tax audit applies to you under Section 44AB, based on your specific turnover.
- Complete the audit, where applicable, before beginning your ITR-3 filing itself.
- Gather capital gains statements and property income records alongside your business financials.
File through the e-filing portal, completing each applicable schedule with your prepared financial data.
Attempting to file ITR-3 before your books of account are actually finalised is a common source of delay, since the return's core schedules depend directly on figures that shouldn't change after filing.
Show more
Show less
A worked example: filing with business and capital gains income together
Consider Pooja, a 41-year-old consultant with a household income of Rs. 1.9 lakh a month and a CIBIL Score of 758, running a small consulting practice alongside occasional share investments.
| Income component | Schedule used | Amount |
|---|---|---|
| Consulting practice net profit | Schedule P&L | Rs. 14,50,000 |
| Capital gains from shares | Schedule CG | Rs. 2,10,000 |
| Total assessable income | Combined | Rs. 16,60,000 |
Because Pooja's consulting income alone ruled out both ITR-1 and ITR-2, and her turnover exceeded the presumptive taxation threshold for ITR-4, ITR-3 was the only form that accommodated her complete income picture.
Show more
Show less
Home loan for professionals
Financing a home alongside business income documentation with Bajaj Finance
| Loan feature | Detail |
|---|---|
| Interest rate | From 7.50% p.a.*, subject to credit assessment |
| Loan amount | Up to Rs. 15 crore* |
| Tenure | Up to 32 years |
For self-employed applicants, a correctly filed ITR-3 with complete schedules gives a lender a clear picture of actual business income for eligibility assessment. Approval timelines can extend where business financials need cross-verification, and minimum income thresholds can differ by city. Check your home loan eligibility with your ITR-3 filing complete and consistent.
Show more
Show less
Frequently Asked Questions
Understanding eligibility
Practical preparation
Can I use ITR-3 even if my business had a loss during the year?
Yes, ITR-3 accommodates both business profit and business loss, and a loss year still requires filing if you're otherwise obligated to file, since a documented business loss can potentially be carried forward to offset future years' profits under the applicable set-off provisions in the Act, subject to specific timing rules.
Does a freelancer with only professional fees, no separate business, still need ITR-3?
Yes, professional income is treated the same as business income for this purpose, so a freelancer with professional fee income who doesn't qualify for or chooses not to use presumptive taxation under ITR-4 needs ITR-3, regardless of how informally the work is structured, described, or invoiced to clients each month.
Do I need a chartered accountant to file ITR-3, or can I do it myself?
Not strictly required for straightforward cases with organised books of account, but recommended given the form's complexity, particularly where a tax audit applies or multiple income schedules interact together. Many taxpayers with genuine business income find professional help worthwhile given the form's detailed requirements and the cost of getting a schedule wrong.
What happens if my books of account aren't ready by the filing deadline?
Filing with incomplete or estimated figures risks errors requiring later correction, so request a filing extension if genuinely available, or prioritise finalising your books before the deadline rather than filing prematurely with unreliable numbers that may need revision or correction shortly after your actual submission is made.
Home Loan in Different Cities

Home Loan in Mumbai

Home Loan in Ahmedabad

Home Loan in Bangalore

Home Loan in Chennai

Home Loan in Delhi

Home Loan in Hyderabad

Home Loan in Cochin

Home Loan in Noida

Home Loan in Pune
Home Loan for different budget
Check your pre-approved offer now
Our Calculators
What do our customers say about us
customers
Play Store rating
reviews
Amit Shiva
Reviewed on
Smooth and transparent home loan process. The interest rates were competitive, and documentation was minimal. The team guided me clearly at every step, making my first home purchase stress-free. Highly recommended for quick approvals.
Sandeep Kulkarni
Reviewed on
The loan disbursal was fast, and the customer support team was extremely patient with all my queries. Flexible EMIs helped me manage my monthly expenses easily. A great experience for salaried homebuyers.
Ritika Agarwal
Reviewed on
I had a great experience while transferring my existing home loan. The process was quick, and I saved significantly with the lower interest rate. Customer service was helpful throughout. Highly recommended for balance transfers.
Manoj Verghese
Reviewed on
Clear guidance, quick approval, and flexible repayment options made buying my new house easier than expected. The team handled everything professionally. Very satisfied and would definitely recommend their home loans
Find your nearest branch

More Articles
Watch our videos
Documents required to get a Bajaj Finserv Home Loan
Tips to increase your Home Loan eligibility
Things you need to know about pre-approved home loan
Things you need to know before applying for a Home Loan
How does Repo Rate affect your Home Loan
Download App
Now request money from your friends and family and make instant payments.
- Choose from personal, business, gold loans and more
- Pay utility bills, use UPI, get FASTag and more
- Buy over 1 million products on No Cost EMI
- Buy stocks, mutual funds and invest in FD
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (NBFC) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.