








₹ 2 lakh – ₹ 80 lakh
Check your pre-approved offer and other benefits
Enter mobile and OTP | Check offer | Know your exact loan terms
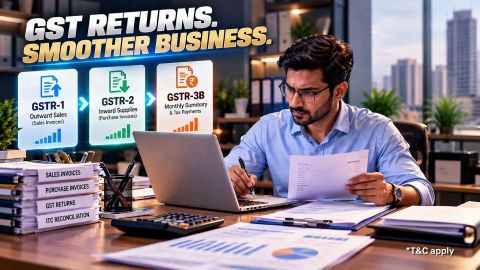
GST Returns Explained
-
In summary
GSTR-3 was planned as a monthly return consolidating GST information, but it was suspended before implementation. For current compliance, check which returns apply to your registration.
- GSTR-3 was intended to consolidate outward-supply details from GSTR-1 and inward-supply information envisaged in GSTR-2.
- GSTR-3 was suspended before implementation and is not available to file on the GST portal.
- GSTR-3B is a self-declared summary return. Monthly filers generally use the 20th of the following month, while QRMP taxpayers follow quarterly due dates.
- GSTR-3 was designed around matched, auto-populated information; GSTR-3B requires taxpayers to report summary figures.
- Fees and interest may apply to overdue GSTR-3B, depending on the return, tax liability, and applicable rules.
Use current GST guidance to confirm your filing obligations and due dates. GSTR-3 is historical context, not a return you need to submit.
What is GSTR-3 and why was it never implemented?
-
GSTR-3 was designed as a monthly consolidated return combining GSTR-1, which reports outward supplies, with GSTR-2, which was intended to report inward supplies. The proposed return would have reconciled these records and calculated the taxpayer’s final tax liability. However, GSTR-2 was suspended, so the linked matching process required for the original GSTR-3 framework did not become operational.
The process depended on invoice matching and reliable auto-population between supplier and recipient records. It was intended to reduce repeated data entry and flag mismatches before tax was finalised. The system proved difficult to implement at scale, so GSTR-3 was suspended before taxpayers could file it.
GSTR-3B is the summary return used for current reporting and payment of tax liabilities. Review GST returns and the current filing requirements before submitting a return.
Why was GSTR-3 suspended before it could be used?
-
GSTR-3 was suspended because the invoice-matching and reconciliation process required by the original framework was difficult to implement reliably. Taxpayers still needed a practical way to report liabilities while the wider GST return system evolved. This allowed filing to continue through a simpler summary mechanism while the planned matching framework remained unavailable.
- The original GSTR-1 → GSTR-2 → GSTR-3 framework depended on matching supplier and recipient invoice details.
- The proposed GSTR-2 reconciliation created operational and technical challenges.
- GSTR-3B was introduced as a simpler, self-declared summary return.
- GSTR-2 and GSTR-3 were never operationalised as originally planned.
- GSTR-3B remains part of current GST compliance; it is not a temporary substitute awaiting GSTR-3.
What was GSTR-3 designed to do?
GSTR-3 was intended to bring sales, purchases, tax liability, and eligible input tax credit (ITC) into one monthly return. Its proposed functions included:
- Combining outward-supply information from GSTR-1 with inward-supply information envisaged in GSTR-2.
- Summarising tax liability and the net amount payable for the period.
- Reconciling ITC against purchase information and identifying discrepancies.
- Allowing taxpayers to review system-generated figures before payment.
Today, GSTR-3B is used for summary reporting. Review GST laws and the applicable GST rate. The original GSTR-3 would have consolidated data and calculated the final liability, but taxpayers should not treat that proposed workflow as a current filing process. If you are reviewing cash flow alongside tax obligations, check your business loan eligibility before applying.


When was GSTR-3 due — and what should you file now?
GSTR-3 was envisaged as a monthly return due by the 20th of the following month, but it was suspended and cannot be filed. Today, monthly GSTR-3B filers generally use the 20th of the next month.
Eligible taxpayers under the Quarterly Return Monthly Payment (QRMP) scheme file GSTR-3B quarterly, generally by the 22nd or 24th of the month after the quarter, depending on their state or Union territory. Check current GST rules and portal notices before filing, as dates can change through notifications.
What were the prerequisites for filing GSTR-3?
GSTR-3 is suspended and cannot be filed. These points describe its original design intent; use current GSTR-3B requirements for actual compliance.
- A GST calculator can help estimate the tax on taxable sales or purchases. Enter the taxable value and applicable GST rate, then check the result against invoices and accounting records. A calculator cannot confirm filing obligations or replace return-level checks. If you are registering a business, review the documents required for GST registration and follow current GSTR-3B instructions. Keep invoices and working papers available to explain differences during reconciliation. Record the assumptions used, and confirm the final figures against the applicable return instructions before filing.
- The process depended on consistent outward- and inward-supply information in GSTR-1 and the proposed GSTR-2.
- Outward- and inward-supply records would have needed reconciliation.
- The taxpayer would have reviewed the liability and arranged payment.
For current filing, use GSTR-3B instructions. Learn how input tax credit works under GST.
How was GSTR-3 meant to be filed on the GST portal?
GSTR-3 cannot be filed today. The following steps summarise the proposed historical workflow and are not current filing instructions. The steps are included to explain how the original return was expected to use reconciled data and tax-payment details; they should not be followed as a live portal process.
- Sign in to the GST portal with the taxpayer’s credentials.
- Open the Returns Dashboard and choose the relevant tax period.
- Review information intended to flow from GSTR-1 and GSTR-2.
- Check sales, purchases, tax liability, and ITC against records.
- Reconcile mismatches between invoice and accounting data.
- Review the calculated liability, including any interest or late fee.
- Arrange payment through the relevant electronic ledgers.
- Submit the return and retain the acknowledgement.
What is the difference between GSTR-3 and GSTR-3B?
GSTR-3 was designed as an auto-populated return based on matched GSTR-1 and GSTR-2 information. GSTR-3B is a self-declared summary return used to report tax liability and pay tax. GSTR-3 never became operational, so taxpayers should follow the GSTR-3B requirements that apply to them. Check the applicable filing frequency and due date for your registration.
| Basis | GSTR-3 (suspended) | GSTR-3B (filed today) |
| Status | Suspended; never operationalised | Active return used for current compliance |
| Nature | Intended to be auto-populated from GSTR-1 and GSTR-2 | Self-declared summary by the taxpayer |
| Invoice matching | Required under the proposed reconciliation design | Not based on the proposed GSTR-2 invoice-matching process |
| Detail level | Consolidated, system-generated figures | Summary figures reported by the taxpayer |
| Filing frequency | Was intended to be monthly | Monthly, or quarterly under QRMP |
| Purpose | Proposed final monthly assessment using matched data | Summary declaration and tax payment |
| What to file today | Not applicable; GSTR-3 cannot be filed | File GSTR-3B according to the applicable due date |
Remember: Use the applicable GSTR-3B due date; GSTR-3 is not available to file.
How did GSTR-3 relate to GSTR-1 and GSTR-2?
Under the original framework, GSTR-3 was intended to consolidate outward-supply information from GSTR-1 and inward-supply details envisaged in GSTR-2. Matching these records would have supported calculation of net tax liability and eligible ITC. GSTR-3B is used for current summary reporting; it did not operationalise the proposed GSTR-2 matching process. The returns therefore had different roles in the planned and current frameworks.
| Return | What it covered | Status |
| GSTR-1 | Details of outward supplies (sales) | Filed under current GST rules, as applicable |
| GSTR-2 | Details of inward supplies (purchases) in the original design | Suspended; GSTR-2A and GSTR-2B are separate auto-drafted statements |
| GSTR-3 | Proposed auto-consolidated summary of GSTR-1 and GSTR-2, including net tax | Suspended; never operationalised |
| GSTR-3B | Self-declared summary return and tax payment | Used for current compliance |
GSTR-3B is used for current summary reporting; it did not operationalise the proposed GSTR-2 matching process.
What was the original format of GSTR-3?
The proposed GSTR-3 format had two broad parts, but the return was never implemented. It was intended to combine system-populated supply information with tax payment and refund details. The format below describes the original design only; it is not a form available for filing.
Part A – Auto-populated information
Part A was intended to draw information from GSTR-1 and the proposed GSTR-2, including:
- Tax-period turnover.
- Outward supplies from GSTR-1.
- Proposed GSTR-2 inward supplies.
- Monthly GST liability.
- Eligible input tax credit.
- Tax, interest, fees, and other dues.
Part B – Tax payment and refund details
Part B was intended to capture payment details, including:
- Amounts paid through electronic ledgers.
- Refunds from the cash ledger.
- Ledger debits settling GST liabilities.
Descriptions of table heads vary; this proposed structure was never a live return.
How can a GST calculator help with GST compliance today?
A GST calculator can help estimate the tax on taxable sales or purchases. Enter the taxable value and applicable GST rate, then check the result against invoices and accounting records.
A calculator cannot confirm filing obligations or replace return-level checks. If you are registering a business, review the documents required for GST registration and follow current GSTR-3B instructions.
Is GSTR-3 still active for GST filing?
No. GSTR-3 was suspended before implementation and is not available on the GST portal. Its proposed workflow depended on matching information from GSTR-1 and GSTR-2, but that framework was not implemented as planned. Applicable taxpayers use GSTR-3B for current summary reporting and tax payment.
Check the current portal instructions for your taxpayer category, filing frequency, and due dates rather than treating older references to GSTR-3 as a filing requirement. If uncertain, confirm the applicable return with a GST professional. Check notifications for any later changes.
What are the penalties if GSTR-3B is not filed?
Late fees and interest may apply if you file GSTR-3B late or leave tax unpaid. The amount depends on the return type, tax liability, relevant tax period, and applicable notifications.
The table below gives indicative treatments only; late-fee caps and concessions can vary, so verify the rules that apply to your filing period. Interest is generally calculated on applicable unpaid tax, while late fees relate to delayed return filing. Check official notifications before relying on any amount.
| Penalty type | Indicative treatment | Maximum or qualification |
| Late fee – return with tax liability | Often Rs. 50 per day in total under CGST and SGST, subject to applicable rules and notifications | Caps and concessions may apply; verify the relevant return period |
| Late fee – nil return | Often Rs. 20 per day in total, subject to applicable rules and notifications | Reduced caps may apply; verify the relevant return period |
| Interest on outstanding tax | Generally 18% per annum on the applicable unpaid tax amount | Calculated according to the law and circumstances; not a fixed capped fee |
Non-filing may also restrict filing of GSTR-1 for a later period under applicable rules. File on time where possible, and seek advice if a return is overdue or tax remains unpaid.
Check your pre-approved business loan offer
How a GST-registered business owner understands GSTR-3 today
Ravi, a textile trader in Surat, sees “GSTR-3” in an old compliance guide and worries he has missed a return. His accountant explains that GSTR-3 was suspended before implementation. Ravi checks his GSTR-1 records and confirms the GSTR-3B filing and payment requirements that apply to his business.
How can you manage cash-flow gaps with a business loan?
Keeping up with GST payments while meeting expenses such as inventory purchases, supplier payments, employee salaries, and day-to-day operations can put pressure on your working capital. Reviewing your tax liabilities and cash flow can help you identify whether additional funding would support your business requirements.
A Bajaj Finance Business Loan offers eligible business owners access to collateral-free funding ranging from Rs. 2 lakh to Rs. 80 lakh, subject to eligibility and applicable terms. You can choose from three loan variants: Term Loan, Flexi Dropline Loan, and Flexi Hybrid Loan, depending on your funding requirements and repayment preferences. The available tenure ranges from 12 to 96 months, allowing you to plan repayments around your business cash flow.
Before applying, assess your funding needs, repayment capacity, interest rate, applicable fees, and loan terms to determine whether borrowing suits your business plans. You can check your pre-approved business loan offer to explore the offer available to you. Pre-approved offers are subject to verification and applicable terms.


Select loan by amount
Applicable fees and charges on our business loan

Loans for business needs
Get business loan for your needs
Women Business Loan
Get Women Business Loan upto 80 Lakh
Medical Store Business Loan
Get Medical Store Business Loan upto 80 Lakh
Manufacturer Business Loan
Get Manufacturer Business Loan upto 80 Lakh
Business loan in different cities

Business loan in bangalore

Business loan in mumbai

Business loan in pune

Business loan in Jaipur

Business loan in Kerala
Business loan for different budgets

2 lakh business loan
3 lakh business loan
5 lakh business loan
10 lakh business loan

15 lakh business loan
20 lakh business loan
25 lakh business loan
30 lakh business loan
50 lakh business loan
Types of business loan
Unsecured Business Loan
Secured Business Loan
Term Loan
Cash Credit
Working Capital Loan
Machinery Loan
Line of Credit
Micro Loan
Merchant cash Loan
Frequently asked questions
Overview
Is GSTR-3 a monthly or quarterly return?
GSTR-3 was designed as a monthly return, but it was suspended before implementation and cannot be filed. GSTR-3B is the summary return used for current compliance; it is filed monthly by most taxpayers, while eligible taxpayers under QRMP file quarterly according to the due dates that apply to their state or Union territory.
Is there a turnover limit for filing GSTR-3?
GSTR-3 is suspended, so no taxpayer files it today. Under the original design, it was intended to cover regular taxpayers rather than operate as a separate turnover-based return. For GSTR-3B, eligible taxpayers with aggregate annual turnover of up to Rs. 5 crore may opt for the QRMP scheme, subject to its conditions and current rules.
Who was required to file GSTR-3 under GST?
GSTR-3 is not currently filed by anyone because it was suspended before implementation. Under the original design, it was intended for regular taxpayers covered by that return framework. The proposed requirement did not mean that every GST registrant had identical obligations; categories such as composition taxpayers, input service distributors, and non-resident taxable persons have separate return rules.
What is the key difference between GSTR-3 and GSTR-3B?
GSTR-3 was intended to be auto-populated using information from GSTR-1 and GSTR-2, while GSTR-3B is a self-declared summary return that is currently used. Taxpayers should not try to file GSTR-3 and should follow the GSTR-3B process applicable to them.
Can GSTR-3 be filed on the GST portal today?
No. GSTR-3 does not appear as an available return for filing on the GST portal because it was suspended before being operationalised. Check the returns applicable to your registration and file GSTR-3B where required; confirm the current due date and instructions on the official portal.
Do regular taxpayers need to worry about GSTR-3 today?
No, not for current filing. GSTR-3 remains relevant as part of the history of the GST return framework, but it is suspended and cannot be filed. For present-day compliance, review GSTR-3B and the other returns that apply to your business, and check current instructions before each filing period.
Can I file GSTR-3 without filing GSTR-1 first?
No. GSTR-3 cannot be filed because it was suspended; under the original design, GSTR-1 was a prerequisite input for the proposed consolidated return. GSTR-3B is filed separately under the current framework, while GSTR-1 is a separate return that must be filed when applicable. Check the rules and filing status for both returns.
What happens if GSTR-3B is not filed on time?
Late fees and interest may apply when GSTR-3B is filed late or tax remains unpaid. Interest on applicable outstanding tax is generally 18% per annum, while late fees depend on the return type, applicable caps, and notifications. Non-filing can also restrict submission of a subsequent GSTR-1. Check the current portal calculation for your period.
Can GSTR-3 be revised after filing?
GSTR-3 cannot be filed today because it was suspended before implementation, so revision of a filed GSTR-3 is not applicable. Under the original proposed framework, corrections would have depended on the applicable return and correction rules. For current reporting errors, follow the correction provisions that apply to GSTR-1, GSTR-3B, or the relevant statement.
Do I need to file GSTR-3 even if there were no transactions?
No. GSTR-3 is suspended and cannot be filed, whether or not you had transactions. Under the original design, a nil return was contemplated. For GSTR-3B, check whether you are required to submit a nil return for the period even when there are no transactions.
More articles
Business financing: A handy guide to business loans
Read More
Top Online Business Ideas in 2026 to Start Your Business
Read More

MSME Loan Scheme in 2025 - Types, Interest Rate, Eligibility, and How to Apply Online
Read More
MSME Loan vs MUDRA Loan
Read More
Disclaimer
Bajaj Finance Limited has the sole and absolute discretion, without assigning any reason to accept or reject any application. Terms and conditions apply*.