







An OTP will be sent to this number for verification

You may have a pre-approved offer
Enter required loan against property amount
In summary
Section 61 Transfer of Property Act
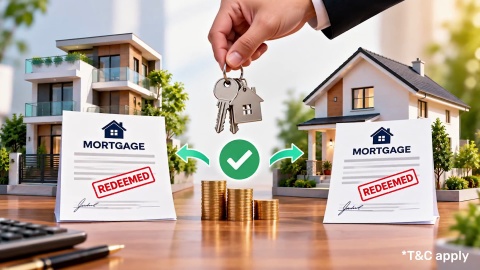
Section 61 of the Transfer of Property Act deals with redemption where you have 2 or more mortgages with the same mortgagee. It allows you to redeem one mortgage separately or redeem multiple mortgages together when the principal money of the relevant mortgages has become due, unless there is a contract to the contrary.
- Section 61 is part of the Transfer of Property Act, 1882
- The section applies when the mortgages are in favour of the same mortgagee
- You can redeem one mortgage separately or 2 or more mortgages together
- A contract to the contrary can alter this default position
- The provision can apply to mortgages involving different properties
- Section 61 should be distinguished from Section 60, which deals with the broader right of a mortgagor to redeem a mortgage
Understanding these conditions can help you read your mortgage documents correctly and determine whether separate redemption is available in your situation.
Last updated: September 2026
What does Section 61 of the Transfer of Property Act mean?
Section 61 of the Transfer of Property Act allows a mortgagor to redeem multiple mortgages separately or together when the mortgages are held by the same mortgagee. This means that if you have taken 2 or more mortgages from the same lender and the principal amount under those mortgages has become due, you may be able to repay and close one mortgage without closing the others. However, this right may not apply if your mortgage agreement contains a contract to the contrary, which means an agreement that provides different terms for redemption.
A few terms make the provision easier to understand:
| Term | Meaning |
|---|---|
| Mortgagor | The person who creates the mortgage over property to secure a debt |
| Mortgagee | The person or institution in whose favour the mortgage is created |
| Mortgage money | The amount secured by the mortgage, including applicable amounts payable under the mortgage terms |
| Redemption | Repayment of the mortgage dues and completion of the steps required to release the mortgage interest |
| Contract to the contrary | An agreement that changes the default position provided under Section 61 |
For example, suppose you create 2 separate mortgages in favour of the same mortgagee. Once the principal money under both mortgages has become due, Section 61 generally allows you to redeem either one separately or both together, subject to the terms of the applicable contract.
Show More
Show Less
When can you redeem mortgages separately?
You can generally redeem one mortgage separately when the conditions of Section 61 are satisfied and there is no contract to the contrary. The section specifically gives the mortgagor the option to redeem any one of the relevant mortgages separately.
Consider this example:
Ravi has 2 mortgages with the same mortgagee:
| Mortgage | Property | Principal money due? |
|---|---|---|
| Mortgage 1 | Property A | Yes |
| Mortgage 2 | Property B | Yes |
If there is no contract to the contrary, Ravi can seek to redeem Mortgage 1 separately instead of being required to redeem Mortgage 2 at the same time.
The important point is that Section 61 addresses the relationship between multiple mortgages held by the same mortgagee. The fact that the mortgages relate to different properties does not, by itself, prevent the statutory right from applying.
What does “contract to the contrary” mean?
A contract to the contrary means that the parties have agreed to a contractual arrangement that changes the default right available under Section 61. The phrase matters because Section 61 itself provides that the right applies in the absence of such a contract.
Before relying on separate redemption, check:
- the original mortgage deed
- subsequent mortgage documents
- supplemental agreements
- repayment or settlement terms
- clauses dealing with simultaneous redemption or consolidation
- any court order affecting the mortgage
If the wording of your documents is unclear, obtain legal advice before taking action.
How is Section 61 different from Section 60?
Section 60 and Section 61 both deal with redemption, but they address different situations.
Section 60 sets out the general right of a mortgagor to redeem after the principal money has become due, subject to the conditions stated in the section.
Section 61 deals specifically with the situation where the same mortgagor has created 2 or more mortgages in favour of the same mortgagee.
| Provision | Main subject |
|---|---|
| Section 60 | General right of the mortgagor to redeem |
| Section 61 | Right to redeem multiple mortgages separately or simultaneously |
| Section 62 | Right of a usufructuary mortgagor to recover possession in specified circumstances |
Section 60 establishes the general right to redeem, while Section 61 addresses how that right operates when multiple mortgages exist with the same mortgagee.
Show More
Show Less
What should you check before redemption?
Before requesting separate redemption under Section 61 of the Transfer of Property Act, review the documents and the status of each mortgage.
A practical checklist is:
- Identify the mortgagee. Confirm that the mortgages are in favour of the same mortgagee.
- List each mortgage. Note the mortgage date, secured property and outstanding principal.
- Check the due date. Confirm whether the principal money under the relevant mortgages has become due.
- Read the mortgage deed. Look specifically for clauses dealing with simultaneous redemption or consolidation.
- Confirm the amount payable. Obtain the applicable outstanding amount and redemption requirements from the mortgagee.
- Check the release process. Find out which mortgage documents, acknowledgements or property records will be released or updated after redemption.
- Keep evidence of discharge. Preserve the payment record and documents showing that the relevant mortgage has been discharged.
For example-
Suppose Meera has 2 mortgages with the same mortgagee. Mortgage A relates to her commercial property, while Mortgage B relates to her residential property. Both mortgage amounts have become due.
Meera wants to redeem Mortgage A but continue Mortgage B.
If there is no contract to the contrary, Section 61 can support separate redemption of Mortgage A. Meera should still check the mortgage deed and complete the mortgagee's prescribed discharge process.
Implications of Section 61 for borrowers
Section 61 can be useful when you have multiple mortgages with the same mortgagee and want to understand your options for repaying them. The provision may allow you to redeem one mortgage separately instead of settling all mortgages together, subject to the applicable terms.
- Provides flexibility in repayment: You may be able to redeem one mortgage separately or redeem multiple mortgages together.
- Allows separate redemption: You may be able to close one mortgage while continuing with another.
- Check the mortgage agreement: A contract to the contrary may change how the right to separate redemption applies.
- Check whether the amount is due: The principal money under the relevant mortgages must have become due.
- Review each mortgage separately: Check the outstanding amount, due date, property covered and redemption conditions.
- One redemption does not close all mortgages: Repaying one mortgage does not automatically discharge your other mortgages.
- Keep proof of redemption: Obtain and retain documents confirming repayment and discharge of the relevant mortgage.
Understanding these implications can help you assess your repayment options and avoid confusion when dealing with multiple mortgages. Before proceeding, review the terms of your mortgage documents and confirm the redemption process with the mortgagee.
Recent amendments and updates pertaining to Section 61
Section 61 of the Transfer of Property Act was significantly amended through the Transfer of Property (Amendment) Act, 1929. The amendment replaced the earlier wording and clarified that a mortgagor with 2 or more mortgages in favour of the same mortgagee can redeem one mortgage separately or 2 or more mortgages together, subject to the terms of the agreement.
Key update:
- The 1929 amendment broadened the provision by removing the earlier restriction linked to the same mortgaged property.
- The current provision focuses on multiple mortgages between the same mortgagor and mortgagee.
- No later central amendment has changed the core wording of Section 61.
The amended provision continues to govern the separate or simultaneous redemption of multiple mortgages, subject to any contract to the contrary.
Frequently Asked Questions
Overview
What does the right to redeem mortgages separately mean under Section 61?
If a borrower has created two or more mortgages in favour of the same lender, Section 61 may allow the borrower to redeem one mortgage without necessarily redeeming the others. This provision can apply when the principal amounts secured by the mortgages have become due, depending on the circumstances and terms of the mortgage.
Can multiple mortgages be redeemed together under Section 61?
Yes. Section 61 also allows a mortgagor to redeem multiple mortgages together. This can be relevant when more than one property or mortgage has been created in favour of the same mortgagee.
Does Section 61 apply to every multiple-mortgage arrangement?
Not necessarily. Its application depends on factors such as the terms of the mortgages, whether the principal amounts have become due, and the circumstances under which the mortgages were created. The specific mortgage documents should therefore be examined to determine the applicable redemption rights.
Why is Section 61 important for borrowers?
Section 61 is important because it addresses how a borrower can exercise the right of redemption when multiple mortgages exist with the same lender. Understanding this provision can help borrowers know whether they may redeem individual mortgages separately or need to address multiple mortgages together.
How many inches are there in one metre?
One metre is equal to 39.37 inches. This fixed conversion value is used worldwide to convert measurements between the metric and imperial systems for construction, manufacturing, education, and other practical applications.
Can I convert decimal metre values into inches?
Yes. Decimal values can be converted using the same formula. For example, 1.5 metres × 39.37 = 59.06 inches. The conversion works for whole numbers, decimals, and fractional measurements alike.
Loan Against Property for different budget
Check your pre-approved offer now
Loan Against Property for Professionals
Find your nearest branch

What do our customers say about us
customers
Play Store rating
reviews
Anita Das
04 March 2026
The loan against property process was smooth and transparent. Interest rates were competitive, and the documentation requirements were minimal. The team provided clear guidance at every step, making the entire experience hassle-free. Highly recommended for quick approvals and reliable support.
Aashish
04 March 2026
The loan disbursal was quick, and the customer support team handled all my queries with patience and clarity. Flexible EMIs made it easy to manage monthly expenses. Overall, a great experience, especially for salaried individuals seeking a loan against property.
Prakash
04 March 2026
I had a great experience transferring my existing loan against property. The process was quick and hassle-free, and I saved significantly with the lower interest rate. The customer service team was supportive throughout. Highly recommended for anyone considering a balance transfer.
Yogesh Singh
04 March 2026
Clear guidance, quick approval, and flexible repayment options made purchasing my new house much easier than expected. The team managed the entire process professionally and ensured smooth coordination at every stage. Overall, a very satisfying experience, and I would recommend their home loan services to others.
Related articles
Watch our videos
Know the tax benefits on your loan against property
What are the documents required for a Loan Against Property?
What are the types of property eligible for Loan Against Property
What is the eligibility criteria for a Loan Against Property
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (NBFC) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.