







Support available Online, on call, or at branches
Get answers instantly without waiting on call:
Enter mobile and OTP · No password needed · No branch visit needed
In Summary
Understand loan foreclosure rules, liens, and restructuring
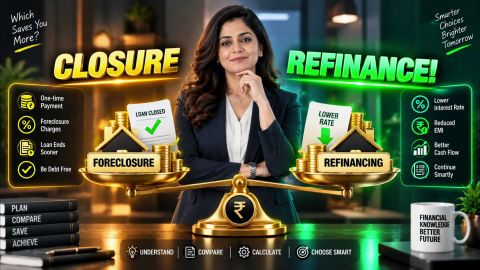
Loan foreclosure closes an existing loan through full repayment, while refinancing replaces the existing loan with a new one. Your financial position, outstanding balance, and future repayment capacity can help you decide which option suits your needs. Compare the interest rate, EMI, remaining tenure, applicable charges, outstanding balance, and total repayment cost before making a decision.
- Foreclosure involves repaying the full amount due, including any applicable charges, to close your existing loan.
- Refinancing involves taking a new loan to replace the existing one, subject to the new lender’s approval and terms.
- Compare foreclosure charges, processing fees, interest costs, and other applicable expenses to assess the total cost.
- Check whether foreclosure would leave enough savings for essential expenses and emergencies.
- Continue following your existing loan terms until the lender confirms closure or the agreed refinancing process takes effect.
- Retain payment records and obtain the relevant closure documents or new loan schedule.
A lower EMI does not necessarily mean a lower borrowing cost, and early foreclosure does not always provide the best financial outcome. Compare the total amounts payable under both options, assess your budget and review the applicable loan terms before proceeding.
What is loan foreclosure?
Loan foreclosure means repaying the full outstanding amount before the scheduled end of your loan tenure. You pay the amount your lender quotes for the intended closure date, including any applicable charges and other dues under your loan agreement. Once the lender completes the closure process, you no longer need to pay regular instalments for that loan. You may consider foreclosure if you have sufficient funds and want to end your existing repayment obligation early. However, you should assess the effect on your savings and compare the potential interest savings with the cost of closing the loan.
Check these points before foreclosing your loan:
- Request the foreclosure amount: Ask your lender for the total amount payable on your intended closure date.
- Review applicable charges: Check your loan agreement and the lender’s official fee schedule for any foreclosure charges or other dues.
- Assess your savings: Ensure that the repayment will not leave you without enough money for essential expenses and emergencies.
- Compare potential savings: Estimate the interest you may avoid paying and compare it with the applicable closure costs.
- Confirm the closure: Follow your lender’s process and retain the final payment receipt and closure documents.
Foreclosure may reduce the interest you would otherwise pay over the remaining tenure. However, applicable charges and the impact on your available savings can affect the overall benefit. Review the figures before committing your funds.
What is loan refinancing?
Loan refinancing means taking a new loan to repay or replace an existing loan. The new loan may offer a different interest rate, EMI, repayment tenure, or other terms, depending on the lender’s offer and approval. You may consider refinancing if you want to change your repayment arrangement or explore a more suitable interest rate. However, a new loan does not automatically reduce your overall borrowing cost. You must account for the new loan’s fees, the existing loan’s closure costs, and the total interest payable over the new tenure.
Review these points before refinancing:
- Interest rate: Compare the proposed rate with the rate on your existing loan, including the applicable rate type and terms.
- EMI and tenure: Check how the new instalment and repayment period will affect your budget and total interest cost.
- New loan costs: Include applicable processing fees and other charges in your comparison.
- Eligibility and approval: Confirm the new lender’s requirements and whether you qualify for the proposed loan.
- Existing loan closure: Understand how the new loan will settle the existing balance and whether any foreclosure charges apply.
- Repayment schedule: Review the new schedule to understand the instalment amount, due dates, and total repayment obligation.
Refinancing may suit you when the new terms meet your needs and the total cost compares favourably with keeping your current loan. Review the final offer and repayment schedule before accepting it.
What is the difference between loan foreclosure and refinancing?
The main difference is that foreclosure closes your existing loan through full repayment, while refinancing replaces it with a new loan. Your available funds, existing loan terms and financial goals can help you decide between these options.
| Basis | Loan foreclosure | Loan refinancing |
| Meaning | You repay the full outstanding amount to close the existing loan. | You take a new loan to repay or replace the existing loan. |
| New loan requirement | You do not need a replacement loan if you use your own funds. | You need approval for a new loan. |
| Repayment after the transaction | You stop paying instalments for the existing loan after the lender confirms closure. | You repay the new loan according to its agreed terms. |
| Interest cost | You may avoid some future interest by closing the loan early. | You may change the interest cost, depending on the new rate and tenure. |
| Applicable charges | Foreclosure charges and other outstanding dues may affect the total cost. | New loan charges and existing-loan closure charges may affect the total cost. |
| Effect on savings | Using your own funds reduces the money available for other needs. | You may preserve some savings, depending on the new loan amount and settlement arrangements. |
| Main consideration | Whether you can afford full repayment without weakening your financial reserves. | Whether the new loan offers a suitable repayment arrangement at an acceptable total cost. |
Foreclosure ends your existing loan after you repay the amount due and the lender completes closure. Refinancing creates a new repayment obligation that replaces the existing one according to the agreed settlement process. Neither option automatically provides the lowest overall cost. Compare the interest rate, remaining tenure, applicable charges, total repayment amount, and effect on your savings before choosing an option.
What costs should you compare before choosing either option?
Compare the total cost of foreclosure with the total repayment cost of refinancing. The amounts depend on your existing loan agreement, outstanding balance, intended closure date, and the terms of any new loan.
For foreclosure, check:
- The full amount due on your intended closure date.
- Any applicable foreclosure charges and other outstanding dues.
- The interest you may avoid paying over the remaining tenure.
- The effect of using your savings to repay the loan in full.
For refinancing, check:
- The interest rate and total interest payable under the new loan.
- The processing fee and any other applicable charges.
- Any foreclosure charges or dues on the existing loan.
- The new EMI and repayment tenure.
- The total amount payable over the new tenure.
Use the following comparison to organise the figures before making a decision.
| Cost factor | Foreclosure | Refinancing |
| Amount payable initially | Full amount required to close the existing loan | Amount required under the new loan arrangement to settle the existing balance, along with any costs you must pay separately |
| Foreclosure charges | Check the existing loan agreement and applicable fee schedule | Check whether the existing lender charges for early closure |
| Processing fees | Generally not applicable to a replacement loan because you are not taking one, but check any other applicable closure costs | Check the new lender’s applicable processing fees |
| Future interest | You may avoid future interest on the closed loan | Calculate the interest payable under the new loan schedule |
| Savings and cash flow | Your available savings may decrease after full repayment | Your cash flow depends on the new EMI, tenure and any upfront payment |
| Total cost | Compare the closure amount with the interest and other costs you would incur by continuing the existing loan | Add the relevant settlement costs, fees and future repayments, accounting for any upfront payments separately |
Compare the total cost, not just the EMI or interest rate. Refinancing may reduce your monthly instalment by extending the tenure, but you could pay more interest over the longer repayment period. A lower interest rate may also fail to produce savings if additional fees outweigh the benefit. Foreclosure may reduce future interest, but applicable charges and the impact on your savings can affect its overall value. Ask your lender to explain any unclear amount and verify the latest product-specific terms through official channels before deciding.
How should you decide between foreclosure and refinancing?
Choose foreclosure when you can repay the full outstanding amount without putting essential expenses or financial reserves at risk. Consider refinancing when you need a different repayment arrangement and the new loan offers terms that suit your financial circumstances.
Follow these six steps to compare your options:
- Review your current loan: Check the outstanding balance, interest rate, remaining tenure, EMI and loan agreement.
- Obtain the foreclosure amount: Ask your current lender for the amount required to close the loan on your intended date.
- Request a refinancing offer: Review the proposed interest rate, EMI, tenure, fees and total repayment amount.
- Calculate the full costs: Include applicable charges and the total interest you may pay under each option.
- Assess your budget: Consider your income, essential expenses, savings and ability to manage future repayments.
- Confirm the settlement process: Understand how the lender will close the existing loan and which documents you will receive.
For example, suppose your current EMI puts pressure on your monthly budget. Refinancing may reduce that instalment, but you should check whether the lender has extended the tenure and increased the total interest payable. Alternatively, if you have enough savings to foreclose the loan, calculate the closure amount and consider whether using those funds would leave you financially vulnerable. Do not accept a refinancing offer based only on a lower EMI or an advertised interest rate. Compare the actual figures from your existing loan and the proposed offer before committing to a new repayment arrangement.
What should you do before closing or replacing your loan?
Review your loan records and confirm the applicable process before foreclosing or refinancing. These checks can help you avoid payment discrepancies and understand your remaining obligations.
Take these steps before proceeding:
- Check your loan statement: Confirm the outstanding balance and review any overdue instalments or other dues.
- Read your loan agreement: Check the applicable foreclosure conditions and charges.
- Verify the new loan terms: If you choose refinancing, review the interest rate, tenure, fees, repayment schedule and total amount payable.
- Confirm the settlement arrangements: Ask how the new lender will settle the existing loan and whether you need to make any payment separately.
- Keep payment records: Retain receipts, transaction references and payment confirmations.
- Confirm account closure: After foreclosure or refinancing, check with the existing lender that it has completed the closure process and obtain the applicable closure documents.
- Review the new repayment schedule: After refinancing, check the new EMI amount and due dates.
Continue meeting your existing repayment obligations until the lender confirms the applicable closure or settlement. Do not assume that applying for refinancing or receiving a loan offer automatically closes your current loan. Contact your lender through official channels if you find a difference between your records and the amount quoted. Proceed only after you understand the amount payable, the settlement process, and the terms that will apply.
Read more -
Frequently Asked Questions
Loan Foreclosure vs Refinancing
Choosing Between Foreclosure & Refinancing
How does loan foreclosure affect your credit score?
Loan foreclosure does not automatically damage your credit score. The effect depends on your credit history and how the lender reports the account status to the relevant credit bureau. After the lender confirms closure, review your credit report to check whether it reflects the correct status. If you find an error, raise a dispute with the credit bureau and contact your lender if you need to correct the underlying loan information. Keep your closure confirmation and payment records until you resolve any discrepancy.
Can I refinance my loan if I'm already in default?
Refinancing a loan while in default is challenging. Lenders typically require borrowers to be current on their payments before approving refinancing. However, some lenders may offer options to help borrowers catch up on payments or consolidate debt. It's important to consult with your lender or a financial advisor before proceeding.
What happens if you cannot afford the full foreclosure amount?
If you cannot afford the full foreclosure amount, review your budget and discuss available repayment options with your lender. You could continue with the existing repayment schedule or assess whether refinancing offers a more suitable arrangement, subject to eligibility and approval. Compare the total costs before choosing either option. Avoid using all your savings without considering essential expenses and emergencies. Confirm any revised terms with your lender before relying on them, and continue meeting your existing repayment obligations until the lender agrees to a change.
How does refinancing affect your existing loan account?
When refinancing replaces your existing loan, the new loan proceeds may settle the old balance according to the agreed process. The exact arrangements depend on the lenders’ terms and the settlement method. Confirm with your existing lender that it has received the required payment and completed the closure process. Keep the settlement confirmation and check your credit report for accurate account information. Also review the new loan agreement and repayment schedule so you understand the EMI, due dates, applicable charges and total amount payable under the replacement loan.
What happens if refinancing takes longer than expected?
Your existing repayment obligations generally continue until your lender confirms the applicable closure or settlement. A pending refinancing application or approved offer does not, by itself, remove your responsibility to follow the current loan terms. Contact the lenders involved to confirm the expected settlement process and identify any outstanding requirements. Continue paying instalments according to your existing agreement unless your lender confirms a change. Keep payment records and check whether the new lender needs further information or documents to complete the transaction.
Does refinancing always reduce the total interest payable?
Refinancing does not always reduce total interest. A lower interest rate may reduce borrowing costs, but a longer repayment tenure can increase the total interest you pay. Processing fees, other applicable charges and costs associated with closing the existing loan may also reduce potential savings. Compare the remaining cost of your current loan with the full repayment cost of the new loan. Check the interest rate, tenure, EMI and total amount payable before accepting the offer, rather than relying on the monthly instalment alone.
More Articles

Disclaimer
While care is taken to update the information, products, and services included in or available on our website and related platforms/websites, there may be inadvertent inaccuracies or typographical errors or delays in updating the information. The material contained in this site, and on associated web pages, is for reference and general information purpose and the details mentioned in the respective product/service document shall prevail in case of any inconsistency. Subscribers and users should seek professional advice before acting on the basis of the information contained herein. Please take an informed decision with respect to any product or service after going through the relevant product/service document and applicable terms and conditions. In case any inconsistencies observed, please click on reach us.
*Terms and conditions apply.