








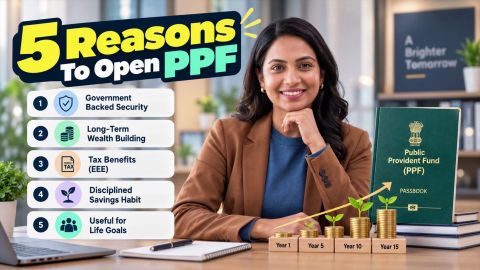
5 Reasons to Open a PPF Account
In summary
A PPF account is suitable for resident Indians who want government-backed security, tax-efficient growth, and disciplined long-term savings. Before investing, consider its deposit limits, long tenure, changing interest rate, and restricted access to funds.
- Government backing provides high investment security
- Returns avoid direct stock market volatility
- Annual investments start from Rs. 500
- Section 80C benefits require old regime
- Interest and maturity proceeds remain tax-exempt
- Fifteen-year tenure supports long-term financial goals
PPF may form the stable, long-term part of your savings plan. You can complement it with a Fixed Deposit when you need shorter tenures, predictable maturity values, or periodic interest payouts.
What is a PPF account?
EPF withdrawal online
-
TA Public Provident Fund (PPF) account is a long-term savings account offered under a Government of India small-savings scheme. Individuals can contribute to the account during a financial year and earn interest at the rate notified by the government.
The scheme is governed by the Public Provident Fund Scheme, 2019. An individual can open one account in their own name and may also open an account on behalf of a minor or a person of unsound mind for whom they are the guardian. Joint PPF accounts are not permitted.
For the October–December 2026 quarter, the PPF interest rate is 7.1% per annum, compounded annually. The government reviews small-savings interest rates periodically, so the rate may change during the account's tenure.
For October–December 2026, PPF earns 7.1% p.a., compounded annually. Since the rate may change in future quarters, your final maturity value cannot be guaranteed when you open the account. PPF can provide stability, but it does not offer broad diversification on its own. You may combine it with investments of different tenures and risk levels according to your goals. For example, Bajaj Finance Fixed Deposit offers assured returns, tenures from 12 to 60 months, and monthly, quarterly, half-yearly, annual, or maturity payout options.
Open an FD online in minutes and grow your savings with up to 8.15% p.a. returns.
Why should you open a PPF account?
A PPF account offers several features that may support long-term savings. Here are five reasons to consider opening one.
1. It is backed by the Government of India
PPF is a government-backed small-savings scheme. Its prescribed terms and conditions provide a defined framework for contributions, interest calculation, withdrawals and maturity.
This makes it an option for individuals who prefer a savings instrument that is not directly exposed to stock market movements.
However, the interest rate is notified periodically by the government. The current rate should not be treated as guaranteed for the entire 15-year period.
2. It offers tax benefits under specified conditions
PPF offers tax benefits at different stages of the investment, subject to the applicable tax provisions:
- Contribution: Eligible PPF contributions qualify for a deduction under Section 123 of the Income-tax Act, 2025, within the aggregate limit of Rs. 1.5 lakh under Schedule XV. This deduction is not available under the new tax regime.
- Interest: Interest earned on a PPF account is generally exempt from income tax under the applicable provisions.
- Maturity proceeds: The amount received on maturity is generally exempt from income tax under the applicable provisions.
The Income-tax Act, 2025 came into effect on 1 April 2026. The availability of the contribution deduction depends on the tax regime and applicable conditions. Therefore, individuals should assess the tax benefit based on their tax position rather than assuming that every PPF contribution will reduce their taxable income.
3. You can start with a relatively small contribution
A PPF account can be opened with an initial deposit of Rs. 500. The minimum annual contribution is also Rs. 500, while the maximum permitted contribution is Rs. 1.5 lakh in a financial year.
Contributions can be made as a lump sum or in instalments. This gives account holders flexibility to decide how much to deposit and when, provided they meet the annual minimum and maximum limits.
For example:
| Contribution pattern | Annual contribution |
|---|---|
| Rs. 500 once a year | Rs. 500 |
| Rs. 1,000 every month | Rs. 12,000 |
| Rs. 5,000 every month | Rs. 60,000 |
| Rs. 12,500 every month | Rs. 1,50,000 |
The maximum annual contribution limit of Rs. 1.5 lakh applies to the individual's own account and the account opened on behalf of a minor taken together.
4. It supports long-term savings through annual compounding
A PPF account has a long tenure, allowing contributions and accumulated interest to build over time. Interest is calculated according to the scheme's rules and credited annually.
The account matures after 15 complete financial years from the end of the financial year in which it was opened. For example, if an account is opened during the financial year 2026–27, the 15-year period is calculated from 31 March 2027, and the account matures after 15 complete financial years from that date.
After maturity, the account holder can extend the account in blocks of five years, with or without further contributions, subject to the scheme's conditions.
This longer savings period can be useful when planning for goals such as retirement or future education expenses.
5. It offers loan and partial withdrawal facilities
Although PPF is a long-term savings scheme, it provides limited access to funds before maturity:
- Loan facility: An account holder can apply for a loan against the PPF balance from the third financial year up to the sixth financial year, subject to the prescribed conditions.
- Partial withdrawal: Eligible partial withdrawals are permitted from the seventh financial year, subject to the scheme's limits.
- Extension after maturity: The account can be extended in blocks of five years. An account holder may also retain the matured account without making further contributions, while the balance continues to earn interest at the applicable rate.
These facilities offer some flexibility, but they do not make PPF a substitute for an emergency fund or a short-term savings account.
Waiting for your EPF withdrawal to process?
Start an FD with a minimum investment of Rs. 15,000 and earn assured returns of up to 8.15%. Open FD.
What are the eligibility criteria for opening a PPF account?
An individual can open a PPF account in their own name. A parent or legal guardian can also open an account on behalf of a minor or a person of unsound mind under their guardianship.
The following rules apply:
- Only one PPF account can be held by an individual in their own name.
- Joint PPF accounts are not permitted.
- A guardian may open an account on behalf of an eligible minor.
- The combined annual contribution to the individual's own account and accounts opened on behalf of minors cannot exceed Rs. 1.5 lakh.
The eligibility and account-opening requirements should be checked with the authorised bank or post office before applying.
If you want to invest a larger amount for a shorter period, Bajaj Finance FD starts from Rs. 15,000. You can start your FD after comparing the available tenures, interest rates, liquidity rules, and tax treatment.
Also read: PPF for NRI
How can you open a PPF account?
-
A PPF account can be opened through an authorised bank or a post office that offers the scheme. Some institutions also provide online account-opening facilities.
The general process is as follows:
- Choose an authorised institution: Select a bank or post office that offers PPF accounts.
- Complete the application: Fill in the prescribed account-opening form and provide the required personal details.
- Submit KYC documents: Provide the identity, address and other documents requested by the institution. Requirements may vary depending on the account-opening channel.
- Make the initial deposit: Deposit at least Rs. 500 to open the account.
- Receive account details: Once the application is processed, the institution provides the account details and passbook or statement, as applicable.
Eligible India Post Internet Banking users can also access online PPF services, including account opening and deposits, subject to the available facilities and requirements.
What are the limitations of a PPF account?
-
PPF has several benefits, but its features may not suit every financial requirement:
Limitation What it means Long maturity period The account matures after 15 complete financial years, which may not suit short-term goals. Restricted withdrawals Partial withdrawals are allowed only after the prescribed period and subject to limits. Annual contribution ceiling The maximum contribution is Rs. 1.5 lakh per financial year. Interest rate revisions The government can revise the interest rate periodically. The current rate is not guaranteed for the full tenure. No joint accounts A PPF account cannot be opened jointly. Individuals who may need frequent access to their savings should consider these limitations before opening an account.
A PPF account can be considered by individuals looking to build long-term savings through a government-backed scheme. Its relatively low minimum contribution, annual compounding, tax benefits under specified conditions and limited loan and withdrawal facilities are some of its key features.
However, the 15-year maturity period and restrictions on withdrawals make it important to assess liquidity requirements before investing. Understanding the contribution limits, current interest rate, tax rules and maturity conditions can help individuals decide whether PPF fits their financial goals.
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
Locate to your nearest FD branch

Related Articles


Frequently Asked Questions
Overview
What are the main reasons to open a PPF account?
The main reasons include government backing, a notified interest rate, tax benefits under specified conditions, a relatively low minimum contribution and annual compounding. PPF also offers limited loan and partial withdrawal facilities. Its long tenure makes it more suitable for long-term savings goals than for expenses that require immediate access to money.
What is the minimum amount required to open a PPF account?
A PPF account can be opened with an initial deposit of Rs. 500. An account holder must also contribute at least Rs. 500 in each financial year to keep the account active. The maximum annual contribution is Rs. 1.5 lakh, including eligible deposits made to accounts opened on behalf of minors.
What is the current PPF interest rate?
The PPF interest rate is 7.1% per annum for the October–December 2026 quarter. Interest is compounded annually. The government reviews small-savings interest rates periodically, so the rate may change during the account's tenure. Account holders should check the latest notification before making financial projections.
Is PPF a tax-free investment?
PPF offers tax benefits under specified conditions. Eligible contributions may qualify for a deduction under Section 123 of the Income-tax Act, 2025, subject to the aggregate limit and applicable tax regime. Interest earned and maturity proceeds are generally exempt under the applicable provisions. The contribution deduction is not available under the new tax regime.
How long does a PPF account remain active?
A PPF account matures after 15 complete financial years from the end of the financial year in which it was opened. After maturity, the account holder can extend it in blocks of five years, with or without further contributions, subject to the scheme's rules.
Can I withdraw money from my PPF account before maturity?
Yes. Partial withdrawals are permitted from the seventh financial year, subject to the prescribed limits and conditions. A loan facility is also available from the third financial year up to the sixth financial year. These facilities are subject to the scheme's rules and should not be treated as unrestricted access to the balance.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.