








- Life cover with built-in savings
- Guaranteed returns on maturity
- Ideal for long-term goals like education or retirement
- Flexible premium payment options
- Peace of mind with financial protection for your family
-
People’s trust in Bajaj
-
10 million+
Customers
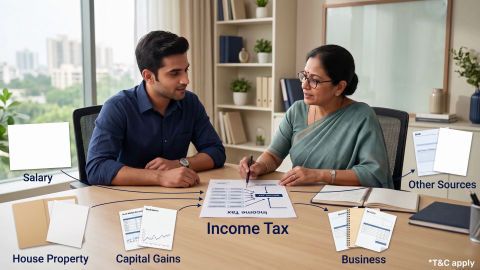
Understand your income tax
In summary
A salary above Rs. 20 lakh can lead to a significant tax bill, but careful planning can help you manage it.
- The new tax regime has a nil tax rate up to Rs. 4 lakh, followed by rates of 5% to 30%.
- The old tax regime allows more deductions and exemptions, including eligible life insurance premiums, health insurance and house rent allowance.
- Under the new regime, salaried individuals can claim a standard deduction of Rs. 75,000.
- Eligible investments under Section 123 of the Income Tax Act, 2025, can qualify for a combined deduction of up to Rs. 1.5 lakh under the old regime.
Compare both regimes using your actual salary, deductions and other income before making a choice. You can explore life insurance plans based on your budget and requirements for a consolidated financial planning, and look for potential ways to save tax as per the relevant tax conditions. Get quote to choose a suitable plan!
What changed in the income tax rules for 2026–27?
For someone earning above Rs. 20 lakh, the main points to understand are:
- New tax regime: Lower tax rates across income slabs, with fewer deductions and exemptions.
- Old tax regime: Higher tax rates in some income bands, but more deductions and exemptions.
- Standard deduction: Salaried taxpayers can claim Rs. 75,000 under the new regime.
- Investment deductions: Eligible payments towards specified savings instruments, including qualifying life insurance premiums, can qualify for deductions under Section 123 of the Income Tax Act, 2025, if the old regime is chosen and the applicable conditions are met.
The right choice depends on your taxable income after eligible deductions, not just your annual salary.
What are the income tax slabs for Tax Year 2026–27?
| Taxable income | Tax rate under the new regime |
| Up to Rs. 4 lakh | Nil |
| Rs. 4 lakh to Rs. 8 lakh | 5% |
| Rs. 8 lakh to Rs. 12 lakh | 10% |
| Rs. 12 lakh to Rs. 16 lakh | 15% |
| Rs. 16 lakh to Rs. 20 lakh | 20% |
| Rs. 20 lakh to Rs. 24 lakh | 25% |
| Above Rs. 24 lakh | 30% |
For example, if your taxable income is Rs. 20 lakh, the tax is calculated separately for each slab. The calculation is Rs. 20,000 on the income between Rs. 4 lakh and Rs. 8 lakh, Rs. 40,000 between Rs. 8 lakh and Rs. 12 lakh, Rs. 60,000 between Rs. 12 lakh and Rs. 16 lakh, and Rs. 80,000 between Rs. 16 lakh and Rs. 20 lakh. The total income tax is Rs. 2 lakh before applicable cess and other adjustments.
The new regime also provides a rebate for eligible resident individuals with taxable income within the prescribed limit. However, this rebate generally does not apply to someone whose taxable income exceeds Rs. 12 lakh.
How do you choose between the old and new tax regimes?
Consider the following differences:
| Factor | New tax regime | Old tax regime |
| Tax rates | Lower rates across the income slabs | Higher rates in some income bands |
| Standard deduction | Rs. 75,000 for eligible salaried individuals | Rs. 50,000 for eligible salaried individuals |
| Life insurance premium deduction | Not available under Section 123 | Eligible premiums may qualify under Section 123 |
| House rent allowance exemption | Not available | Available if applicable conditions are met |
| Health insurance deduction | Generally unavailable under the usual old regime provisions | Available for eligible premiums under applicable conditions |
The Income Tax Department recommends comparing tax liability under both regimes before choosing. You can use its official income tax resources to check the applicable rules and calculate your liability.
Which tax saving options are available under the new regime?
The main options to review include:
- Standard deduction: Reduce salary income by Rs. 75,000 when calculating taxable income, subject to eligibility.
- Employer NPS contribution: An eligible employer contribution may qualify for a deduction within the applicable limit.
- Eligible employment allowances: Certain allowances, including specified transport allowances for employees with disabilities, may qualify for relief under the applicable rules.
- Eligible retirement payments: Some payments, such as qualifying gratuity and leave encashment, may receive tax exemption subject to prescribed conditions.
Most personal investment deductions available under the old regime cannot be claimed under the new regime. This includes the usual deduction for eligible life insurance premiums under Section 123.
For this reason, do not invest in a product only because you expect a tax deduction. Consider its purpose, cost, lock in period and suitability for your financial goals.
Which tax saving options are available under the old regime?
The main options include:
1. Eligible savings and life insurance premiums:
Section 123 of the Income Tax Act, 2025, allows an aggregate deduction of up to Rs. 1.5 lakh per financial year for specified eligible payments and investments. These can include qualifying life insurance premiums and provident fund contributions, subject to the prescribed conditions. This deduction is not available under the new tax regime.
2. Health insurance premiums:
Eligible health insurance premiums for yourself, your spouse, dependent children and parents may qualify for deductions under the applicable provisions. Under the earlier Section 80D framework, the usual limits were Rs. 25,000 for self and family and an additional Rs. 25,000 for parents, increasing to Rs. 50,000 for a senior citizen. Confirm the corresponding provisions and limits applicable for Tax Year 2026–27 before claiming them.
3. Education loan interest:
Interest paid on an eligible education loan for higher education may qualify for a deduction for up to eight consecutive assessment years, subject to the applicable conditions. The earlier Section 80E provision did not prescribe a fixed monetary cap on the eligible interest deduction.
4. Eligible charitable donations:
Donations to eligible institutions may qualify for a deduction of 50% or 100% of the eligible amount, depending on the institution and the applicable conditions. Not every donation qualifies.
5. Retirement contributions:
Eligible contributions to approved retirement arrangements may provide tax benefits. Check the relevant limits and whether the contribution is eligible under the regime you choose. There are life insurance plans that come with retirement benefits as well. You can explore these life insurance based retirement plans to get a life cover and plan for your retirement.
6. Home loan benefits:
Under the earlier provisions, eligible home loan principal repayments could form part of the Rs. 1.5 lakh combined deduction limit, while interest on a qualifying self occupied home loan could qualify for a deduction of up to Rs. 2 lakh under Section 24(b). The treatment depends on the tax regime, property use and applicable conditions.
Always check the current provisions before claiming deductions because section references and rules changed when the Income Tax Act, 2025, took effect.
How much tax would you pay on a salary of Rs. 20 lakh?
For example, assume you earn an annual salary of Rs. 20 lakh, have no other income and claim the Rs. 75,000 standard deduction under the new regime.
| Calculation | Amount |
| Annual salary | Rs. 20,00,000 |
| Less: standard deduction | Rs. 75,000 |
| Taxable income | Rs. 19,25,000 |
| Income tax before cess | Rs. 1,85,000 |
| Health and education cess at 4% | Rs. 7,400 |
| Total tax before other adjustments | Rs. 1,92,400 |
This is an illustration based on the stated assumptions and the new tax regime slab rates for Tax Year 2026–27. Your actual tax may differ if you have other income, eligible relief or other adjustments.
Under the old regime, the result would depend on the deductions and exemptions you can claim. Use the same salary information to calculate both options before deciding.
How can you save tax on a salary above Rs. 20 lakh?
1. Compare both regimes:
Calculate your tax under the new regime first, then check whether the old regime offers enough eligible deductions and exemptions to lower your total liability.
2. Review your salary components:
Check whether your salary includes eligible house rent allowance, leave travel allowance or other components that receive different tax treatment under the old and new regimes.
3. Use eligible investment deductions:
If you choose the old regime, review qualifying payments towards specified savings instruments and life insurance premiums. The combined deduction under Section 123 is capped at Rs. 1.5 lakh per financial year, subject to eligibility.
4. Check health insurance and retirement contributions:
Review your eligible health insurance payments and retirement contributions. Do not assume that a deduction available under the old regime will also be available under the new regime.
5. Keep your records organised:
Maintain salary slips, employer tax statements, premium receipts, eligible investment records and loan interest certificates. These help you calculate taxable income correctly and support deductions or exemptions you claim.
6. Calculate before investing:
A tax saving product should fit your financial needs, not just reduce your tax bill. Compare the amount you may save in tax with the money you need to invest and any restrictions on accessing it.
Which salary components may be exempt from income tax?
| Salary component | General tax treatment |
| Basic salary | Generally taxable |
| Dearness allowance | Generally taxable |
| House rent allowance | Eligible exemption under the old regime, subject to conditions |
| Leave travel allowance | Eligible exemption for qualifying travel under the old regime |
| Official expense reimbursements | May be exempt when they meet the applicable rules and are supported by records |
| Standard deduction | Rs. 75,000 under the new regime and Rs. 50,000 under the old regime for eligible salaried individuals |
To calculate taxable salary, begin with the salary income considered taxable under the relevant rules. Subtract eligible exemptions and deductions, including the standard deduction, where applicable.
For example, if your annual salary is Rs. 20 lakh and you qualify for the Rs. 75,000 standard deduction under the new regime, your taxable salary would be Rs. 19.25 lakh before accounting for any other relevant adjustments.
Which tax regime may suit someone earning Rs. 20 lakh a year?
Consider these two situations:
- You have limited deductions: If you do not claim house rent allowance, eligible life insurance premium deductions or other old regime benefits, compare the new regime first.
- You have several eligible deductions: If you pay eligible life insurance and health insurance premiums, contribute to qualifying retirement arrangements and claim eligible home loan or house rent benefits, calculate the old regime carefully before deciding.
The final decision should be based on the total tax payable under both options. Avoid choosing a regime based on a general rule that everyone earning above Rs. 20 lakh should follow the same approach.
How can you legally reduce your taxable income?
Use this checklist before filing your return:
- Compare the tax payable under both regimes.
- Claim only eligible deductions and exemptions.
- Check whether your life insurance premiums qualify under Section 123 if you choose the old regime.
- Verify health insurance, retirement contribution, home loan and education loan records where relevant.
- Review salary statements and tax deducted at source to ensure the figures are correct.
- Keep supporting documents for every claim.
Do not treat tax deductions as guaranteed savings. A deduction reduces the income on which tax is calculated; the actual tax saving depends on your applicable tax rate and eligibility.
Conclusion
Frequently asked questions
Know more about saving tax
How much tax will be charged on a salary of Rs. 20 lakh?
Tax on a salary of Rs. 20 lakh depends on the regime you choose, your taxable income and eligible deductions. Under the new regime, an eligible salaried individual can claim a Rs. 75,000 standard deduction. Assuming no other income or adjustments, taxable income would be Rs. 19.25 lakh and the illustrative tax, including 4% cess, would be Rs. 1,92,400.
Which tax regime should I choose for Rs. 20 lakh a year?
Compare both regimes using your actual salary and eligible deductions. The new regime may suit someone with limited deductions, while the old regime may be worth considering if eligible exemptions and deductions reduce taxable income significantly. Use the official tax calculator or seek professional advice before deciding.
How can I save tax on a salary of Rs. 20 lakh?
Start by comparing both regimes, reviewing your salary components and checking eligible deductions. Under the old regime, qualifying life insurance premiums and other specified payments may contribute to a combined deduction of up to Rs. 1.5 lakh under Section 123, subject to the applicable conditions. Keep records of every claim.
What tax slab applies to a salary above Rs. 20 lakh?
Under the new regime for Tax Year 2026–27, taxable income from Rs. 20 lakh to Rs. 24 lakh is taxed at 25%, and taxable income above Rs. 24 lakh is taxed at 30%. These rates apply to the relevant portions of taxable income, not the entire salary.
Can a home loan help reduce tax on a salary above Rs. 20 lakh?
Yes, eligible home loan principal repayments and interest payments may provide tax benefits under the old regime, subject to the applicable rules and limits. The treatment depends on factors such as whether the property is self occupied or rented. Check the rules for Tax Year 2026–27 before claiming a deduction.
Are there tax benefits for high income earners?
There is no single special deduction simply because someone earns above Rs. 20 lakh. Eligible taxpayers can use deductions, exemptions and other tax provisions that apply to their circumstances. The benefit depends on the tax regime, income sources, qualifying payments and current tax rules.
Can senior executives save tax through salary planning?
Senior executives can review their salary structure, eligible allowances, retirement contributions and available deductions. The tax treatment depends on the type of payment and the chosen regime. They should compare the final tax liability under both regimes rather than assuming that every allowance or reimbursement is exempt.
Is Rs. 20 lakh a good annual salary in India?
Whether Rs. 20 lakh is sufficient depends on your location, household costs, dependants, debts and financial goals. Your take home income will be lower after tax and other deductions. Budgeting for essential expenses, emergency savings, retirement and suitable life cover can help you plan around your actual income.
How do premium rates vary between life insurance and term insurance?
Term insurance premiums are generally lower because they offer pure life cover for a fixed period without maturity benefits. In contrast, life insurance combines protection with savings or investment features, resulting in higher premiums due to long-term financial returns and cash value components.
How do maturity benefits compare between term and life insurance plans?
Term insurance doesn’t offer any maturity benefits, while life insurance policies like endowment or whole life provide a lump sum payout on maturity, acting as a savings component.



Related articles


#Above illustration is for Bajaj Life Goal Assure IV is A Unit-linked Non-Participating Individual Life Savings Insurance Plan (UIN: 116L204V01) considering Male aged 25 years | Standard Life | Policy term (PT) - 20 years | Premium Payment Term (PPT) - 20 years | Total premiums paid Rs. 7,20,000 | Monthly Premium Payment Mode | Sum Assured Rs. 3,60,000 | Incase of unfortunate death during the 8th policy year, death benefit payable at 4% and 8% will be Rs. 3,60,000. This illustration is considering investment in "Pure Stock Fund - ULIF02721/07/06PURESTKFUN116” through Investor Selectable Portfolio Strategy and Goods & Service Tax (GST) of 18%.
Assumed investment returns on 20th Policy Year
CAGR*
₹14,50,242 - 8%*
₹ 9,46,134 - 4%*
The assumed rate of returns indicated at 4% and 8% are illustrative and not guaranteed and do not indicate the upper or lower limits of returns under the policy.