








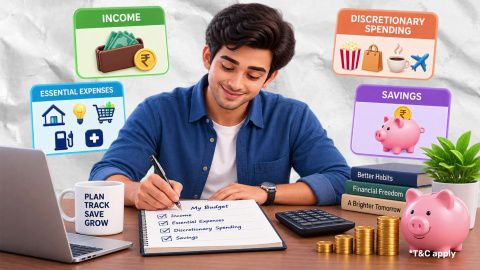
Budgeting & Wealth Building Tips - How to Manage and Grow Your Money
-
In Summary
Budgeting helps you plan how to use your income, manage expenses and set aside money for future needs. To create a practical monthly budget, calculate your take-home income, categorise your expenses and decide how much you can allocate to savings and financial goals. Track your actual spending regularly and adjust your plan when your circumstances change.
When creating a budget, focus on these steps:
- Calculate your income: Include your take-home salary and other reliable sources of income.
- Categorise expenses: List essential costs, loan EMIs, discretionary spending and irregular expenses.
- Set financial priorities: Plan for essential payments, debt repayment, emergency savings and future goals.
- Choose a budgeting method: Use the 50/30/20 rule, zero-based budgeting or envelope budgeting according to your needs.
- Review your budget: Compare planned and actual spending each month and revise allocations where necessary.
No single budgeting method suits every household. Choose an approach that reflects your income, responsibilities and financial priorities.
What is budgeting?
-
Budgeting is the process of planning how to use the money you receive during a particular period. It involves estimating income, allocating money to different expenses, setting aside savings and monitoring whether your spending follows the plan.
A personal budget generally covers:
- Income: Money received through salary, business earnings, freelance work, rent or other sources.
- Essential expenses: Costs such as housing, food, utilities, transport, healthcare and education.
- Financial commitments: Loan EMIs, insurance premiums, credit card payments and other dues.
- Discretionary expenses: Spending on dining out, entertainment, shopping and other non-essential activities.
- Savings and investments: Money set aside for emergencies, planned purchases and longer-term financial goals.
A budget does not mean eliminating every non-essential expense. Its purpose is to help you make informed choices about how to use the money available to you.
How to create a monthly budget?
-
Follow these steps to prepare a budget that reflects your financial situation:
1. Calculate your monthly income
Start by adding up the income you expect to receive during the month. If you are salaried, use your take-home salary rather than your gross salary, as deductions such as tax and employee contributions may already have been made.
Include other reasonably predictable income, such as freelance earnings, rental income or interest received. If your income varies from month to month, use a conservative estimate rather than assuming you will receive your highest possible amount.
For example, if your take-home salary is Rs. 45,000 and you receive an average of Rs. 5,000 from other reliable sources, your estimated monthly income is Rs. 50,000.
2. List and categorise your expenses
Record your expenses using bank statements, payment histories, bills, receipts or a budgeting app. If you frequently spend in cash, track those payments too.
Divide expenses into categories to make your spending easier to understand.
- Fixed expenses: Rent, recurring loan EMIs, school fees and regular insurance premiums.
- Variable essential expenses: Groceries, electricity, transport and household supplies.
- Discretionary expenses: Eating out, subscriptions, entertainment and non-essential shopping.
- Irregular expenses: Annual insurance premiums, vehicle servicing, festival spending and planned medical costs.
For irregular expenses, estimate the amount you may need over a year and set aside a monthly portion where possible. For example, an annual expense of Rs. 12,000 can be planned for by setting aside Rs. 1,000 a month.
3. Set financial goals
Decide what you want your budget to help you achieve. Goals may include building an emergency fund, repaying debt, saving for a holiday, funding education or preparing for retirement.
Make goals specific and measurable. Instead of writing “save more money”, you could set a target to save Rs. 24,000 over 12 months by setting aside Rs. 2,000 each month.
Consider the time frame, amount required and your existing financial commitments. If you have high-interest debt or little emergency savings, these may need attention before you allocate more money to discretionary purchases or long-term investments.
4. Allocate money to each category
Once you know your income, expenses and goals, decide how much to allocate to each category. Cover essential living costs and required payments first, then plan for savings, debt repayment and discretionary spending.
Avoid setting targets that leave you without enough money for regular needs. If your expenses are higher than your income, identify the categories where spending can be reduced and consider whether additional income may be possible.
5. Track actual spending
A budget is useful only if you compare it with what you actually spend. Record purchases during the month and review each category against its planned limit.
For example, if you allocate Rs. 4,000 to dining out but spend Rs. 5,000, review the reason for the difference. You may need to reduce spending in the following month or revise the budget if the original estimate was unrealistic.
6. Review and adjust your budget
Review your budget at the end of each month. Compare estimated income and expenses with actual amounts, identify recurring overspending and update your targets.
Revisit your budget when your salary changes, a loan ends, rent increases or a major expense arises. A budget should be flexible enough to reflect changing circumstances while keeping your priorities clear.
What are the different budgeting methods?
You can choose from several budgeting methods depending on how much detail you want and how predictable your income and expenses are:
1. The 50/30/20 rule
The 50/30/20 rule is a budgeting guideline that divides take-home income into three broad categories:
- 50% for needs: Essential expenses such as rent, groceries, utilities and necessary transport.
- 30% for wants: Discretionary spending such as entertainment, dining out and non-essential purchases.
- 20% for savings and debt repayment: Savings, investments and additional debt repayment, depending on your circumstances.
For a monthly take-home income of Rs. 50,000, the indicative allocation would be:
| Category | Suggested share | Amount |
|---|---|---|
| Needs | 50% | Rs. 25,000 |
| Wants | 30% | Rs. 15,000 |
| Savings and debt repayment | 20% | Rs. 10,000 |
| Total | 100% | Rs. 50,000 |
These proportions are a starting point, not mandatory limits. If rent, education costs or medical expenses take up a larger share of your income, you may need to adjust the percentages.
2. Zero-based budgeting
In zero-based budgeting, you assign a purpose to every rupee of your expected income. This includes regular expenses, savings, debt repayment and discretionary spending.
The aim is for income minus planned allocations to equal zero. It does not mean spending all your money: savings and emergency-fund contributions are also budget allocations.
This method may suit people who want detailed control over their spending. It requires more frequent tracking than broader budgeting approaches.
3. Envelope budgeting
Envelope budgeting involves assigning a fixed amount to each spending category. Traditionally, people use separate cash envelopes; digitally, the same idea can be followed with spending categories or separate accounts, where appropriate.
For example, you might allocate Rs. 5,000 for transport and Rs. 4,000 for dining out. Track spending against each amount and avoid exceeding the category limit unless you deliberately revise your plan.
This method can help people who tend to overspend in particular categories. However, the limits still need to reflect actual needs and reasonable estimates.
4. Pay-yourself-first budgeting
With this approach, you set aside a planned amount for savings or a financial goal as soon as income arrives. You then use the remaining amount to meet expenses.
This can encourage regular saving, but the amount should be realistic. Essential costs, required debt payments and an adequate cash buffer still need to be considered. If you have little emergency savings, you could begin with a manageable contribution and increase it over time.
How to prepare a monthly budget: Example
Suppose a household has a combined monthly take-home income of Rs. 60,000. The following example shows how the household could allocate its income.
| Budget category | Monthly allocation |
|---|---|
| Rent | Rs. 15,000 |
| Groceries and household essentials | Rs. 8,000 |
| Utilities and mobile bills | Rs. 2,500 |
| Transport | Rs. 3,500 |
| Loan EMI | Rs. 7,000 |
| Insurance and healthcare provision | Rs. 2,000 |
| Education and family expenses | Rs. 4,000 |
| Personal spending and entertainment | Rs. 4,000 |
| Emergency savings and financial goals | Rs. 8,000 |
| Buffer for irregular expenses | Rs. 6,000 |
| Total planned allocation | Rs. 60,000 |
In this example, the household assigns the full Rs. 60,000 to planned categories. The Rs. 6,000 buffer is intended for irregular costs that may otherwise disrupt the monthly plan; any amount not used can remain available for future needs or be directed towards a financial goal.
The figures are illustrative, not a recommended allocation for every household. Your budget may look different depending on your rent, family size, location, debt and other responsibilities.
What should you prioritise in your budget?
When your income is limited, prioritising expenses can help you meet important obligations without losing sight of longer-term goals:
Cover essential expenses first
Set aside enough for housing, food, utilities, necessary transport, healthcare and other essential household requirements. Include required loan payments and other due amounts so that you can plan for them on time.
Plan for debt repayment
List your outstanding debts, minimum payments, interest costs and due dates. Keep up with required payments and consider directing additional money towards higher-interest debt where appropriate. Avoid taking on new debt to fund non-essential spending.
Build an emergency fund
An emergency fund can help cover unexpected costs, such as urgent repairs, medical expenses or a temporary loss of income, without relying entirely on borrowing.
The amount required depends on your circumstances, including income stability, dependants and regular expenses. Build the fund gradually if saving a large amount at once is not feasible, and keep emergency money accessible when it may be needed at short notice.
Allocate money to future goals
After accounting for essential spending, required payments and an appropriate emergency reserve, plan contributions towards future goals. Match the savings or investment option to when you need the money, the access you require and the level of risk you can accept.
For example, if you have a monthly surplus that is not needed for immediate expenses or emergency access, you could compare options such as savings accounts, recurring deposits and fixed deposits (FDs). A Bajaj Finance FD may be one option to evaluate for money you can set aside for a chosen tenure. Review the applicable interest rate, tenure, payout terms, premature-withdrawal conditions, taxation and deposit-related risks before deciding. Do not commit emergency money to an option that may limit access when you need it.
What should you do if your expenses exceed your income?
If your planned expenses are higher than your income, first calculate the shortfall. Then review the budget to identify which expenses can be reduced, deferred or renegotiated.
Consider these steps:
- Check for overlooked expenses: Review small purchases, subscriptions, delivery charges and cash spending.
- Separate needs from wants: Temporarily reduce non-essential spending where feasible.
- Review recurring commitments: Check whether you can lower certain bills or adjust services without creating a larger cost.
- Plan debt payments carefully: Avoid ignoring required payments. If repayment is becoming difficult, contact the lender to understand the available options.
- Reassess your income estimate: If income varies, base essential commitments on a cautious estimate and plan for higher-income months separately.
- Revise savings targets when necessary: A smaller, sustainable contribution may be more realistic than a target that repeatedly forces you to borrow for everyday expenses.
If the shortfall continues despite these changes, the budget may indicate that the underlying issue is not simply discretionary spending. You may need to reassess major commitments, seek appropriate financial guidance or explore ways to increase income.
How can you manage and maintain your budget?
Consistency matters more than choosing a complicated system. These habits can help you maintain a budget over time:
- Use a method you can maintain: A notebook, spreadsheet or budgeting app can work if you record transactions consistently.
- Automate suitable payments and savings: Where practical, schedule regular transfers after accounting for essential bills and cash-flow needs.
- Keep irregular expenses visible: Plan for annual premiums, repairs, school costs and festivals instead of treating them as unexpected every time.
- Review spending weekly: Short reviews can help you identify overspending before the month ends.
- Avoid unrealistic limits: If you repeatedly exceed a category's budget, reassess the estimate rather than assuming you can always spend less.
- Update your plan after major changes: A change in income, family responsibilities or debt obligations may require a different allocation.
A budget is a working plan, not a one-time exercise. Reviewing it regularly helps you understand your financial position and make adjustments before small problems become persistent shortfalls.
Check out different FD Rates
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
Creating a budget starts with understanding how much money comes in, where it goes and what you need to set aside for future expenses. By categorising spending, setting realistic goals and tracking actual transactions, you can make more informed decisions about everyday purchases, debt repayment and savings.
Choose a budgeting method that suits your circumstances rather than following a fixed percentage without considering your needs. Review your plan regularly, prepare for irregular expenses and adjust it when your financial situation changes. Over time, a practical budget can help you manage cash flow and work towards your financial goals.
Locate to your nearest FD branch

Related Articles

Frequently Asked Questions
Overview
How do you create a budget for beginners?
Start by calculating your monthly take-home income. List essential expenses, loan payments, discretionary spending and irregular costs. Decide how much you can reasonably allocate to savings and financial goals, then assign amounts to each category. Track actual spending during the month and compare it with your plan. Review the budget regularly and revise estimates that do not reflect your real expenses.
What is the 50/30/20 rule in budgeting?
The 50/30/20 rule is a budgeting guideline that allocates 50% of take-home income to needs, 30% to wants and 20% to savings and debt repayment. For example, with a take-home income of Rs. 50,000, the indicative amounts are Rs. 25,000, Rs. 15,000 and Rs. 10,000 respectively. The proportions can be adjusted to suit your income, living costs and financial commitments.
How do you plan a monthly budget?
Add up your expected take-home income and list your regular and irregular expenses. Set aside money for essential bills and required debt payments, then plan for emergency savings, future goals and discretionary spending. Track your transactions throughout the month. At the end of the month, compare actual spending with the plan and adjust the next month's allocations where needed.
What is the easiest budgeting method?
The easiest method depends on how you manage money. The 50/30/20 rule provides a simple starting structure, while envelope budgeting can help control specific spending categories. Zero-based budgeting offers more detailed control but requires more tracking. Start with the approach you can follow consistently and change it if it does not reflect your actual income and expenses.
Why is budgeting important?
Budgeting helps you understand your income and spending, plan for regular bills, prepare for unexpected expenses and work towards financial goals. It can also help identify recurring overspending and make debt repayment easier to plan. A budget does not guarantee financial security, but reviewing it regularly can support more informed decisions about how to use available money.
What should you do if you cannot save every month?
First, review your income, essential expenses and required debt payments to understand why there is no surplus. Look for realistic spending reductions, check recurring commitments and reassess whether your budget estimates are accurate. If possible, begin with a small savings contribution and increase it when your circumstances allow. Avoid borrowing for ordinary expenses just to maintain an unrealistic savings target.
How to control budget?
Set realistic category limits and check your spending regularly throughout the month. When one category exceeds its limit, reduce another non-essential category accordingly.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.