








Financial Accounting
-
In Summary
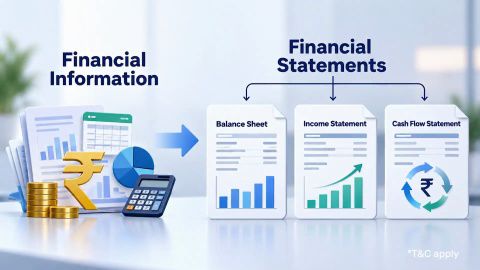
Financial accounting converts a business’s financial transactions into structured reports, including the balance sheet, statement of profit and loss, and cash flow statement. These reports help readers assess a business’s assets, liabilities, income, expenses and cash movements.
Key points to understand:
- Purpose: To communicate reliable financial information to people who need to assess a business.
- Main reports: The balance sheet, statement of profit and loss, and cash flow statement, along with relevant notes and disclosures.
- Accounting methods: Cash accounting records transactions when money is received or paid; accrual accounting records income and expenses when they are earned or incurred, subject to applicable rules.
- Key principles: Consistency, accrual accounting, going concern, prudence and adequate disclosure are important concepts in financial reporting.
- Users: Investors, lenders, suppliers, employees, regulators and business owners may use financial statements.
- Limitations: Financial statements largely reflect recorded financial events and may not capture every factor affecting a business’s future performance.
The applicable accounting standards and reporting requirements depend on the type of organisation and the rules governing it.
What is financial accounting?
-
Financial accounting is the systematic process of recording, classifying, summarising and reporting a business’s financial transactions. It helps produce financial statements that show how the business has performed over a particular period and what its financial position is at a particular date.
For example, a business may receive payments from customers, purchase raw materials, pay employee salaries, borrow money or buy equipment. Financial accounting records these transactions and organises them into categories so that the information can be used to prepare financial reports.
Financial accounting is more than bookkeeping. Bookkeeping primarily involves recording transactions, while financial accounting also includes reviewing and adjusting those records and preparing financial statements according to the applicable reporting framework.
In India, businesses must follow the accounting and financial reporting requirements applicable to their legal structure and circumstances. These may include the relevant Accounting Standards or Indian Accounting Standards (Ind AS). The Institute of Chartered Accountants of India (ICAI) provides resources on accounting standards and Ind AS.
What is an example of financial accounting?
-
Consider a small business that sells office furniture. During one month, it makes sales, purchases inventory, pays rent and receives a bank loan.
The following simplified example shows how these transactions may be recorded.
Transaction Amount Financial accounting treatment Sales made to customers Rs. 1,00,000 Recorded as revenue when recognised under the applicable accounting rules Inventory purchased Rs. 40,000 Recorded as inventory; the cost is generally recognised as an expense when the inventory is sold Rent paid for the month Rs. 10,000 Recorded as a rent expense for the relevant period Loan received from a bank Rs. 50,000 Recorded as cash or a bank balance and a corresponding loan liability These figures are illustrative. They do not represent a complete set of accounts or a calculation of the business’s final profit.
The example highlights an important distinction: receiving money does not always mean earning revenue, and paying money does not always mean incurring an expense immediately. For instance, a loan increases the business’s cash balance but is also a liability that must be repaid. Similarly, inventory purchased may remain an asset until it is sold or otherwise consumed.
Calculate your expected investment returns with the help of our FD Return and Recurring deposit calculators.
How does financial accounting work?
Financial accounting follows a sequence of steps to convert transaction records into financial statements. The exact procedures vary according to the business and its reporting requirements.
1. Identify and record transactions
The process begins by identifying financial transactions supported by relevant records, such as invoices, receipts, bank statements, payroll records and payment confirmations.
The transactions are entered into the accounting system, often through journals or accounting software.
2. Classify transactions into accounts
Each transaction is assigned to the relevant account. Common categories include:
- Assets: Resources controlled by the business, such as cash, inventory and equipment.
- Liabilities: Amounts the business owes, such as loans and unpaid supplier bills.
- Equity: The residual interest in the business after deducting liabilities from assets.
- Income: Amounts earned through sales or other activities.
- Expenses: Costs incurred to operate the business.
Correct classification helps prevent errors when preparing financial statements.
3. Post entries to the ledger
Journal entries are transferred to the relevant ledger accounts. The ledger groups transactions by account, making it easier to review balances and identify unusual entries.
4. Prepare a trial balance
A trial balance lists the balances of ledger accounts to check whether total debits equal total credits under the double-entry bookkeeping system.
However, a balanced trial balance does not prove that every transaction has been recorded correctly. Some errors may still exist even when the totals agree.
5. Make adjustments
Adjustments may be needed for items such as accrued expenses, income earned but not yet received, depreciation, provisions and prepaid costs. The adjustments depend on the transactions and the applicable accounting requirements.
6. Prepare financial statements
The adjusted records are used to prepare the relevant financial statements, including the balance sheet, statement of profit and loss, and cash flow statement, along with the required notes and disclosures.
7. Review and report the results
The statements are reviewed to assess the organisation’s financial position and performance. Depending on the business and the law, further steps may include an independent audit, statutory filing or other reporting obligations.
ICAI’s Framework for the Preparation and Presentation of Financial Statements explains the purpose of financial statements and the information they are intended to provide to users.
What are the main financial statements?
Financial accounting produces reports that show different aspects of a business’s finances. Each report answers a different question.
Balance sheet
The balance sheet, also called the statement of financial position, shows a business’s assets, liabilities and equity at a specific date.
It helps readers understand what the business owns or controls, what it owes, and the residual interest attributable to its owners.
The basic accounting equation is:
Assets = Liabilities + Equity
For example, if a business has assets worth Rs. 8 lakh and liabilities worth Rs. 3 lakh, its equity would be Rs. 5 lakh, assuming the figures are complete and measured on a consistent basis.
Statement of profit and loss
The statement of profit and loss, also called the income statement, summarises income and expenses over an accounting period. It helps show whether the business made a profit or incurred a loss.
A simplified calculation is:
Profit or loss = Income − Expenses
For example, if a business records recognised income of Rs. 5 lakh and expenses of Rs. 3.5 lakh during a period, its profit before any other applicable items or adjustments would be Rs. 1.5 lakh.
Profit does not necessarily equal cash generated during the period. Some sales may remain unpaid, while some expenses may be recorded before the related cash payment is made.
Cash flow statement
The cash flow statement reports cash and cash-equivalent movements during an accounting period. It generally classifies cash flows into three categories:
- Operating activities: Cash flows from the business’s main revenue-producing activities.
- Investing activities: Cash flows related to acquiring or disposing of long-term assets and investments.
- Financing activities: Cash flows related to borrowings, repayment of debt and transactions with owners.
This statement helps readers understand how a business generates and uses cash. A business can report a profit but still face cash-flow difficulties if customers do not pay on time or substantial cash is tied up in inventory.
Notes to the financial statements
Notes provide additional explanations, accounting policies, breakdowns and disclosures that help readers interpret the figures in the main statements. They form an important part of financial reporting and should be read alongside the statements.
What are the main methods used in financial accounting?
Cash accounting and accrual accounting are two approaches to recognising income and expenses. The method a business may use depends on the applicable reporting requirements and its circumstances.
Cash accounting
Under cash accounting, income is generally recorded when payment is received and expenses when payment is made.
For example, if a business receives Rs. 20,000 from a customer in June, it records the receipt in June under a cash-based approach, even if the work was completed in May.
This approach can make cash movements easier to follow. However, it may not show all amounts earned or owed at a particular date.
Accrual accounting
Under accrual accounting, income is generally recognised when earned and expenses when incurred, rather than simply when cash changes hands. Recognition remains subject to the relevant accounting requirements.
For example, if a business completes a service worth Rs. 20,000 in June and the customer pays in July, the income may be recognised in June under accrual accounting, provided the applicable recognition criteria are met.
Accrual accounting can provide a more complete view of a business’s performance and obligations during a reporting period. It is central to many formal financial reporting frameworks, but the exact requirements depend on the standards applicable to the entity.
What are the key principles of financial accounting?
Financial accounting uses established concepts and reporting requirements to make financial information useful and consistent. The precise requirements depend on the applicable standards; the following are important concepts commonly encountered in financial accounting.
Accrual concept
Transactions are recognised in the period to which they relate, rather than solely when cash is received or paid, where accrual accounting applies.
Consistency
Accounting policies and methods should be applied consistently where appropriate. If a policy changes, the applicable reporting requirements may require the change and its effects to be explained.
Going concern
Financial statements are generally prepared on the assumption that the business will continue operating for the foreseeable future, unless circumstances or applicable requirements indicate otherwise.
Prudence
Prudence involves exercising caution when making judgements under uncertainty. It does not permit arbitrary understatement of assets or income, or arbitrary overstatement of liabilities or expenses.
Materiality
Information is material when omitting, misstating or obscuring it could reasonably influence decisions made by users of the financial statements.
Full and relevant disclosure
Financial reports should include the information required by the applicable reporting framework so that users can understand the organisation’s financial position and performance.
Matching of expenses and related income
Where required by the applicable accounting framework, expenses are recognised in the period in which the related goods, services or economic benefits are consumed. This helps present business performance appropriately. The concept should not be treated as a standalone rule that overrides specific accounting standards.
ICAI’s financial statement framework discusses concepts including accrual basis, going concern, consistency, relevance, reliability, prudence and materiality.
What is the difference between financial accounting and management accounting?
Financial accounting and management accounting both use financial information, but they serve different purposes.
| Basis of comparison | Financial accounting | Management accounting |
|---|---|---|
| Main purpose | Reports financial performance and position | Supports internal planning, control and decision-making |
| Main users | Investors, lenders, regulators, suppliers and other stakeholders | Managers and internal decision-makers |
| Focus | Primarily recorded financial transactions and reporting periods | Operational performance, budgets, forecasts and business choices |
| Reporting format | Uses financial statements and required disclosures | Uses reports designed around management needs |
| Reporting requirements | Subject to applicable accounting standards and legal requirements | Generally tailored to internal needs, while remaining subject to any relevant legal obligations |
| Time orientation | Primarily reports historical financial information | May analyse past results and future scenarios |
For example, financial accounting may show that a business earned a profit of Rs. 10 lakh during a year. Management accounting may analyse the profitability of individual product lines, compare actual costs with budgets and estimate how a proposed price change could affect future results.
The two functions complement each other. Financial accounting provides structured financial records, while management accounting uses relevant information to support internal decisions.
Check out different FD Rates
Why is financial accounting important for a business?
Financial accounting helps businesses maintain records and communicate financial information in a structured way. Its importance extends to several areas.
- Monitoring financial performance: Financial statements help show whether a business has made a profit or loss during a period.
- Understanding financial position: Information about assets, liabilities and equity helps readers assess the business’s financial structure.
- Assessing cash flows: Cash flow reporting helps identify how cash is generated and used.
- Supporting external decisions: Investors and lenders may use financial statements when assessing a business.
- Meeting reporting obligations: Proper accounting supports the preparation of statements and other reports required under applicable laws and standards.
- Improving accountability: Documented transactions and disclosures make it easier to review how financial resources have been managed.
- Comparing performance: Consistently prepared reports can help users compare results across periods or between businesses, while accounting-policy differences should also be considered.
Financial accounting can support better decisions, but it does not guarantee profitability, funding or business success.
Who uses financial accounting information?
Different stakeholders use financial statements for different purposes.
- Business owners and shareholders: To assess performance, financial position and the use of resources.
- Potential investors: To examine financial results, obligations and other information relevant to investment decisions.
- Banks and other lenders: To assess repayment capacity and credit risk.
- Suppliers and creditors: To consider whether a business is likely to pay amounts owed.
- Employees: To understand aspects of the employer’s financial stability and ability to sustain operations.
- Government departments and regulators: To carry out applicable reporting, regulatory and taxation functions.
- Auditors: To examine financial statements and evaluate them against the relevant audit criteria.
The needs of these users differ, and financial statements cannot answer every question. Readers may need additional disclosures, market information or other evidence to form a fuller view.
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
What are the limitations of financial accounting?
Financial accounting is useful, but its reports need to be interpreted carefully.
It largely reflects past events
Financial statements mainly report transactions and conditions recognised during or at the end of a reporting period. They do not, by themselves, establish what will happen in the future.
It does not capture every non-financial factor
Employee expertise, customer satisfaction, brand reputation and management quality can affect a business but may not be fully represented as figures in its financial statements.
Estimates and accounting policies affect reported figures
Items such as depreciation, provisions and asset valuation may involve estimates and policy choices permitted under the relevant standards. Comparisons between businesses should take material differences into account.
Profit does not equal cash flow
A profitable business may have limited cash available if customers delay payment, inventory increases or substantial expenditure is required. Profit and cash flow should therefore be assessed separately.
Historical costs may differ from current market values
Some assets are recorded using historical cost, while other items may be measured using different bases where required or permitted by the applicable standards. A reported carrying amount should not automatically be treated as the asset’s current market value.
Errors and misleading presentation remain possible
Accounting procedures and audit requirements can help identify problems, but errors, omissions or misleading presentation may still occur. Readers should consider the notes, audit report where available, and other relevant information.
It is not a complete forecasting tool
Financial accounting provides an important historical foundation for analysis, but budgets, forecasts, industry conditions and other evidence may be needed to assess future performance.
How can financial accounting help when evaluating a company?
Financial statements can help readers organise their assessment of a company, but no single figure should be considered in isolation.
When reviewing a company, consider:
- Revenue and profit: Examine changes over several reporting periods and understand the reasons behind them.
- Assets and liabilities: Review the company’s resources and obligations, including borrowings.
- Cash flows: Compare cash generated from operating activities with reported profit.
- Accounting policies and notes: Look for information about significant estimates, commitments and accounting-policy changes.
- Audit report and disclosures: Read relevant qualifications, observations or other disclosures where available.
- Industry context: Consider business conditions and compare companies only after accounting for important differences in size, operations and reporting practices.
Financial statements are one part of company analysis. They should be considered alongside other relevant information, and they do not guarantee a particular investment outcome.
Financial accounting helps turn business transactions into structured information about financial performance, financial position and cash flows. Understanding the balance sheet, statement of profit and loss, cash flow statement and the principles behind them can help readers interpret a company’s financial reports more carefully. However, these reports mainly reflect recorded financial events and may not capture every factor affecting future performance. For a balanced assessment, financial statements should be read with their notes, relevant disclosures, accounting policies and the reporting requirements that apply to the organisation.
Locate to your nearest FD branch

Related Articles
Frequently Asked Questions
Overview
What is financial accounting in simple words?
Financial accounting is the process of recording business transactions and preparing financial reports. These reports show a business’s financial position, performance and cash flows, helping stakeholders understand its finances.
What are the three main financial statements?
The three main financial statements commonly discussed are the balance sheet, statement of profit and loss, and cash flow statement. The complete reporting package may also include notes and other disclosures required by the applicable accounting framework.
What is the difference between bookkeeping and financial accounting?
Bookkeeping mainly involves recording and organising financial transactions. Financial accounting uses those records, along with adjustments and reporting procedures, to prepare and present financial statements.
What are the two main methods of accounting?
Cash accounting generally recognises transactions when money is received or paid. Accrual accounting generally recognises income when earned and expenses when incurred, subject to the applicable accounting requirements.
Is financial accounting mandatory in India?
The accounting and financial reporting requirements depend on the type of entity and the laws applicable to it. Companies and other regulated entities may have specific obligations to maintain books and prepare financial statements under the relevant legal and accounting framework.
What is the difference between a balance sheet and a profit and loss statement?
A balance sheet shows assets, liabilities and equity at a particular date. A statement of profit and loss reports income and expenses over a period to show the resulting profit or loss.
Can a company make a profit but have a cash shortage?
Yes. A company may recognise revenue before receiving payment or may spend cash on inventory, equipment or debt repayments. This is why the cash flow statement should be read alongside the statement of profit and loss.
What is the difference between financial accounting and management accounting?
Financial accounting primarily prepares financial information for external reporting. Management accounting provides internal reports, analysis and forecasts to support planning, cost control and business decisions.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.