





- EPFO 3.0 is a broader digital transformation, rather than simply an ATM withdrawal facility.
- The revised partial-withdrawal framework has consolidated earlier provisions into three categories: Essential Needs, Housing Needs and Special Circumstances.
- Eligible members with at least 12 months of contributory service can withdraw up to 75% of their eligible PF balance, subject to the applicable scheme conditions.
- A 25% minimum balance is earmarked to remain in the PF account under the revised framework.
- Eligible advance claims of up to Rs.5 lakh can be auto-settled through EPFO's digital systems, generally within three working days.
- ATM and UPI withdrawal are part of the digital-access roadmap, but the exact member-facing process, availability, transaction limits and authentication requirements should be confirmed when the facility is enabled for the relevant member.
EPFO 3.0: Withdraw PF by Swiping at ATMs in 2026 (Full Guide)
What EPFO 3.0 changes, what is currently available, and how proposed ATM and UPI-based PF withdrawals may work
EPFO 3.0 is a technology-led transformation of the Employees' Provident Fund Organisation (EPFO) designed to make PF services faster, more automated and easier to access. The programme includes centralised digital processing, automated claim settlement and a proposed mechanism for accessing eligible PF funds through ATM and UPI-linked channels.
In summary
What is EPFO 3.0 and how could ATM withdrawal work?
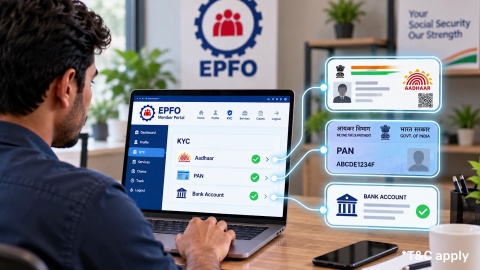
EPFO 3.0 refers to EPFO's broader digital transformation programme. The Central Board of Trustees approved a member-centric digital transformation framework in October 2025. The framework uses a modern core-banking architecture, cloud-based modules and API-driven services to improve account management, claims and member services.
The proposed ATM and UPI functionality is intended to make eligible PF withdrawals more accessible through digital or banking-style channels.
However, it is important to distinguish between the approved digital framework and the specific ATM operating process.
The following flow represents the proposed concept rather than a currently guaranteed procedure:
Eligible PF balance → EPFO validates claim → digital authentication → approved withdrawal → bank/UPI channel → funds credited or dispensed
The exact mechanism could involve an EPFO-linked card, UPI integration or another authorised payment interface. Details such as card issuance, ATM network participation, transaction charges, PIN requirements and transaction limits depend on the final operational implementation.
What has changed under the new EPF withdrawal framework?
The most significant confirmed change is not the ATM itself. It is the simplification of partial-withdrawal rules.
Earlier, EPFO had multiple withdrawal provisions covering different purposes and service requirements. The revised framework consolidates these into three broad categories:
- Essential Needs – including illness, education and marriage.
- Housing Needs – covering eligible housing-related requirements.
- Special Circumstances – covering specified situations under the revised framework.
The minimum service requirement for partial withdrawals has also been reduced to 12 months across the categories. Eligible members can withdraw up to 75% of their PF balance, subject to the applicable rules.
The revised framework also provides for a 25% minimum balance to remain in the member's account. This means the entire PF balance is not intended to become available for ordinary partial withdrawal.
What happened to marriage and education withdrawal limits?
The revised framework increased the permitted frequency for certain purposes.
- Marriage withdrawals: up to five times.
- Education withdrawals: up to ten times.
These changes form part of the consolidation of the earlier withdrawal provisions.
The framework also reduced documentation requirements for eligible partial withdrawals, supporting greater automation.
Is PF withdrawal through an ATM available in 2026?
This is the most important distinction for anyone searching for EPFO PF withdrawal ATM.
EPFO's digital transformation framework provides for faster and more accessible withdrawals, and official EPFO documents have discussed a mechanism through which members could withdraw approved amounts using an ATM card or digital channel.
However, the availability of an EPFO ATM withdrawal facility should not be assumed to be nationwide as of 30 September 2026.
Recent reports continue to describe ATM and UPI access as an upcoming or phased feature rather than an established facility available at every bank ATM.
Therefore, there is currently no basis to state that every EPFO member can simply swipe an EPFO card at any ATM and withdraw 50% of their balance.
The practical position is:
| Feature | Status in 2026 |
|---|---|
| EPFO 3.0 digital transformation | Being implemented |
| Centralised digital processing | Implemented in phases |
| Auto-settlement of eligible advance claims | Available |
| Auto-settlement limit | Up to Rs.5 lakh for eligible claims |
| 75% partial-withdrawal framework | Applicable subject to scheme conditions |
| 25% minimum balance provision | Applicable |
| ATM-based PF withdrawal | Planned/phased; nationwide availability should be verified |
| UPI-based PF withdrawal | Planned/phased; availability should be verified |
How could PF ATM withdrawal work once enabled?
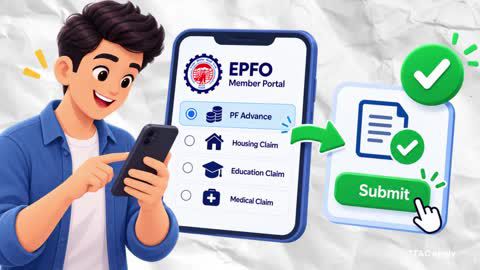
The final operating procedure should be treated as subject to EPFO's notified instructions. Based on the proposed architecture, a member-facing process could broadly involve:
Step 1: Maintain an eligible EPFO account
The member would need an active EPFO account and satisfy the applicable withdrawal conditions.
Step 2: Complete KYC and account verification
Aadhaar, PAN, bank-account and other member details should be correctly seeded and verified wherever required.
EPFO has continued to encourage members to update their KYC details to make use of its digital services.
Step 3: Use the authorised withdrawal channel
Once ATM access is enabled for the member, an authorised EPFO-linked card or designated ATM interface could be used.
Step 4: Authenticate the transaction
The final authentication method could involve a combination of PIN, OTP or another approved digital authentication mechanism. EPFO has not established a universal ATM authentication procedure that can be applied to every member at present.
Step 5: Select the eligible withdrawal
The system would determine the amount available under the member's applicable withdrawal rules.
Step 6: Receive the approved amount
Depending on the final channel, the approved amount could be dispensed through an ATM or transferred through the linked digital payment mechanism.
Important: The above is an indicative flow, not a claim that these exact ATM screens, card features or authentication steps are already available nationwide.
How much PF can be withdrawn under EPFO 3.0?
The revised withdrawal framework allows eligible members to withdraw up to 75% of their eligible PF balance for qualifying partial withdrawals, subject to the applicable conditions. A 25% minimum balance is retained under the framework.
This is different from saying that an ATM withdrawal will necessarily allow exactly 75% or exactly 50%.
Some earlier reports about the proposed ATM facility referred to a 50% ATM withdrawal limit. However, that should not be presented as the definitive nationwide ATM rule unless and until EPFO formally specifies the operating limit for that channel.
Therefore, members should distinguish between:
- Overall partial-withdrawal framework: up to 75% for eligible withdrawals.
- Minimum balance: 25% retained under the revised framework.
- ATM-specific limit: subject to the final operating rules for the ATM facility.
What is auto-claim settlement under EPFO 3.0?
Auto-settlement allows eligible claims to be processed electronically without requiring manual intervention for every claim.
EPFO increased the auto-settlement limit for eligible advance claims from Rs.1 lakh to Rs.5 lakh in June 2025. The facility covers eligible advance claims for purposes such as illness, education, marriage and housing, with processing targeted within three days.
By September 2026, EPFO was reporting that eligible claims up to Rs.5 lakh could be auto-settled through the CITES technology platform within three working days.
The MD's earlier claim that 95% of routine claims are automatically settled should therefore be removed. Official data supports a high and increasing share of auto-settlement, but not a blanket 95% figure.
For example, EPFO reported that 59% of advance claims were settled through auto mode during FY 2024-25, while around 70% had been auto-settled during the first two and a half months of FY 2025-26.
How does traditional PF withdrawal compare with the EPFO 3.0 approach?
The difference between traditional PF withdrawal and EPFO 3.0 can be stated as follows:
| Feature | Existing digital claim process | EPFO 3.0 digital framework |
|---|---|---|
| Primary channel | EPFO online services/UMANG | Centralised digital ecosystem |
| Claim processing | Online, with system checks | Greater automation and straight-through processing |
| Auto-settlement | Available for eligible advances | Expanded digital processing |
| Auto-settlement limit | Up to Rs. 5 lakh for eligible advances | Up to Rs. 5 lakh for eligible advances |
| Partial withdrawal | Subject to applicable rules | Three simplified categories |
| Minimum service for partial withdrawal | Depends on applicable provision | 12 months for the revised framework |
| Minimum balance | Depends on applicable rule | 25% retained under revised framework |
| ATM withdrawal | Not a standard nationwide facility | Planned/phased digital access |
| UPI withdrawal | Not a standard nationwide facility | Planned/phased digital access |
What are the eligibility requirements for EPF withdrawal?
Eligibility depends on the type of withdrawal.
Under the revised partial-withdrawal framework, members generally need at least 12 months of contributory service for the relevant partial withdrawals. Up to 75% of the eligible PF balance may be withdrawn, subject to the scheme provisions.
For digital processing, accurate member information is also important. EPFO has encouraged members to maintain updated KYC and use its digital authentication facilities.
However, the MD's proposed requirement that every ATM withdrawal will require 100% verified Aadhaar, PAN and bank account plus Aadhaar-linked mobile authentication should not be stated as a final ATM rule until EPFO publishes the specific operational requirements.
What are the current PF withdrawal rules after leaving a job?
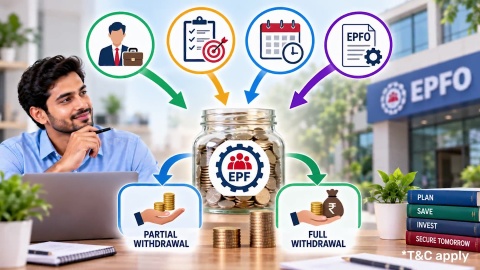
The revised framework also changes the treatment of final settlement.
The premature final-settlement period has been extended from two months to 12 months under the reform framework. This is intended to reduce premature depletion of retirement savings while still allowing members to access their funds under the applicable provisions.
This means EPFO 3.0 should not be understood as turning a PF account into an ordinary bank savings account.
PF remains a retirement-oriented social-security account, and withdrawals continue to be governed by specified conditions.
What are the tax rules for PF withdrawal?
The method used to receive PF money does not by itself change the underlying tax treatment.
A withdrawal from a recognised provident fund after completing the applicable five-year continuous-service condition is generally exempt under the relevant provisions. Certain exceptions and situations involving transfers, employer closure or other specified circumstances can affect the calculation of continuous service.
For a taxable premature withdrawal, TDS can apply where the accumulated balance is Rs.50,000 or more.
From 1 April 2026, the Income-tax Act, 2025 applies. The earlier Section 192A provision has been carried into the new framework under Section 392(7). The TDS rate remains 10% where the applicable conditions are met and PAN is available.
Form 15G or 15H may be relevant in eligible cases where the conditions for furnishing the declaration are satisfied.
Therefore:
- Five years or more of continuous eligible service: withdrawal is generally exempt, subject to applicable conditions.
- Less than five years: withdrawal may be taxable.
- Taxable withdrawal of Rs.50,000 or more: TDS can apply at 10% where the statutory conditions are met.
- TDS is not the same as final tax liability: the withdrawal still needs to be considered under the applicable income-tax provisions.
What should you consider before withdrawing PF through a faster channel?
Faster access does not change the long-term purpose of EPF.
EPF currently carries an approved interest rate of 8.25% for FY 2025-26, and the revised withdrawal framework specifically retains a 25% minimum balance.
A withdrawal can therefore reduce the amount remaining in the retirement account and the future interest earned on that amount.
Before using an accelerated withdrawal channel, members may consider:
- Whether the expense qualifies under the applicable withdrawal category
- Whether the full amount requested is actually required
- Whether the withdrawal will affect long-term retirement savings
- Whether the amount could instead be funded from another liquid source
- The tax implications where the five-year service condition is not met
The purpose of a faster withdrawal system is to improve access, not to remove the conditions attached to EPF savings.
How can a Fixed Deposit be used for surplus funds after a PF withdrawal?
If a member withdraws PF for a specific expense and subsequently has an unused amount, that surplus can be considered separately from the EPF decision.
A Fixed Deposit is one possible savings instrument for money that does not need to remain immediately available in a bank account. However, moving withdrawn PF money into an FD does not restore the withdrawn EPF contribution or its retirement-account treatment.
For example, Bajaj Finance currently offers FD rates of up to 7.40% p.a. for customers below 60 and up to 7.75% p.a. for senior citizens, depending on tenure and payout option. Its published FD tenures range from 12 to 60 months, with deposits from Rs.15,000 to Rs.3 crore.
Bajaj Finance FDs carry CRISIL AAA/STABLE and ICRA AAA(Stable) ratings. These are credit ratings and should not be interpreted as a government guarantee of repayment.
A loan against an FD may also be available subject to the provider's terms, which can offer liquidity without necessarily closing the deposit.
Conclusion
EPFO 3.0 is a wider digital transformation intended to make PF services more automated, centralised and accessible. ATM and UPI withdrawals are among the most discussed features, but they should not be presented as a universally available facility until EPFO confirms the member-facing rollout and operating rules.
The reforms that are already supported by official EPFO and government information include:
- Partial withdrawals consolidated into three broad categories.
- Minimum service requirement of 12 months for the revised partial-withdrawal framework.
- Up to 75% of eligible PF balance available for qualifying partial withdrawals.
- 25% minimum balance retained under the revised framework.
- Education withdrawals permitted up to 10 times and marriage withdrawals up to five times.
- Eligible advance claims up to Rs.5 lakh can be auto-settled through EPFO's digital systems.
- EPFO's digital infrastructure is being upgraded through the CITES/EPFO 3.0 framework.
- ATM and UPI-based access remains subject to the final operational rollout and member eligibility.
Frequently asked questions
When will you be able to withdraw your PF using an ATM card?
EPFO 3.0 includes plans for faster and more accessible PF withdrawals, including ATM and digital channels. However, as of 30 September 2026, a single nationwide ATM withdrawal facility should not be presented as universally live. Members should check official EPFO communications and their available member services for the current status.
How much of your EPF balance can you withdraw?
Under the revised partial-withdrawal framework, eligible members can withdraw up to 75% of their eligible PF balance, subject to the applicable conditions, while 25% is retained as the minimum balance.
The exact limit for any future ATM transaction should be confirmed against the final ATM operating rules.
What prerequisites are required for PF withdrawal?
The requirements depend on the withdrawal type. For the revised partial-withdrawal framework, eligible members generally need at least 12 months of contributory service. Updated KYC details can also help members access EPFO's digital services.
There is not yet a universal, officially confirmed checklist for an EPFO ATM card transaction that can be applied to every member.
Will PF ATM withdrawals have transaction fees?
There is no confirmed universal fee structure for a nationwide EPFO ATM withdrawal facility. Any applicable ATM, banking or payment-network charges would depend on the final operating model and EPFO's notified terms.
Are PF ATM or UPI withdrawals subject to TDS?
The payment channel does not by itself change the tax treatment. Where a PF withdrawal is taxable because the applicable continuous-service condition is not met, TDS can apply at 10% on an accumulated balance of Rs.50,000 or more, subject to the statutory conditions. From 1 April 2026, the corresponding provision is Section 392(7) of the Income-tax Act, 2025.
Does EPFO 3.0 allow the entire PF balance to be withdrawn?
No. The revised partial-withdrawal framework allows eligible members to withdraw up to 75% of their eligible PF balance, with 25% retained as the minimum balance. Final settlement and other special circumstances have separate rules.
More Articles
Related Videos
EPF Balance Check With and Without UAN Number
Download App
Now request money from your friends and family and make instant payments.
- 1. Apply for Loans: Choose from personal, business, gold loans and more
- 2. Transact: Pay utility bills, use UPI, get FASTag and more
- 3. Shop: Buy over 1 million products on No Cost EMI
- 4. Invest: Buy stocks, mutual funds and invest in FD