








- High coverage at a low premium
- Financial protection for your family’s future
- Tax benefits up to Rs. 46,000`` under Section 80C and 10(10D)
- Dedicated claim assistance
- Customisable plans to suit your needs
-
People’s trust in Bajaj
-
10 million+
Customers
-
3
Insurance partners
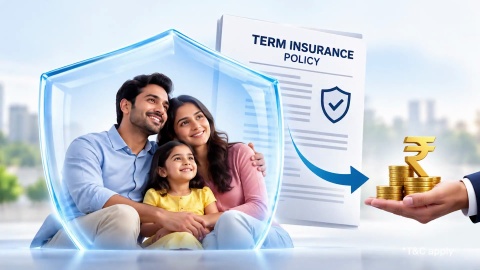
Secure Your Home Loan with Term Insurance
In summary
Term insurance can help your family manage an outstanding home loan if the insured dies during the policy term. The death cover can be used towards the loan, subject to the policy terms and cover amount.
- You can assess the sum assured against your outstanding home loan and other financial responsibilities.
- The policy term can be aligned with the remaining home loan repayment period.
- Your premium depends on factors such as age, cover amount, policy term, health and smoking status.
- Critical illness and accidental death riders can provide additional protection, subject to their terms.
- From April 1, 2026, qualifying life insurance premiums can be considered under Section 123 of the Income Tax Act, 2025, subject to applicable conditions.
Before choosing a policy, compare the cover amount, policy term, premium and applicable riders. Explore term insurance plans to assess coverage that fits your home loan and family's financial needs. Get quote for a suitable plan through Bajaj Finance Insurance Mall.
How does term insurance help you secure your home loan?
The insurance payout does not automatically close the home loan. How the claim proceeds are used depends on the policy structure, the beneficiary or assignment arrangement, the outstanding loan and the applicable policy terms.
Loan repayment support:
The death cover can help your family repay some or all of the outstanding home loan.
The amount available for repayment depends on the sum assured and the loan balance when the claim becomes payable. If the loan balance is higher than the applicable death cover, your family may still need to arrange the remaining amount.
Lower financial pressure on your family:
A home loan continues to create a financial obligation even after the borrower's death. The insurance payout can give your family funds to manage this liability without relying entirely on regular income or existing savings.
Cover aligned with your loan:
You can assess the sum assured based on your outstanding loan and remaining repayment period.
Your family's other financial needs also matter. A policy designed only around the home loan may leave less protection for household expenses, education or other liabilities.
What are the key features of term insurance for a home loan?
| Feature | Relevance to home loan protection |
|---|---|
| Sum assured | Provides the death cover available to your nominee and can be assessed against the outstanding loan |
| Policy tenure | Can be aligned with the period for which you need loan protection |
| Premium | Depends on your age, cover amount, policy term and personal profile |
| Additional riders | Critical illness and accidental death riders can provide additional protection, subject to their terms |
| Death cover | Can provide funds to help your family manage the outstanding home loan |
| Tax benefits | Eligible life insurance premiums and death cover qualify for tax deductions and exemptions under the Income Tax Act 2025, subject to the applicable conditions and tax laws. Note: Tax laws are subject to change. BFL does NOT provide Tax/Investment advisory services. Please consult your advisors. |
How should you choose term insurance for home loan protection?
Coverage amount:
Start with the outstanding home loan amount and then consider your family's other financial needs.
For example, if you have a home loan balance of Rs. 50 lakh, a Rs. 50 lakh life cover may address that loan amount but may leave little or no additional cover for household expenses and other liabilities.
The actual cover you need depends on your overall financial responsibilities.
Policy tenure:
The policy term should cover the period for which the home loan remains a significant financial obligation.
For example, if your home loan has 20 years remaining, assess whether the term insurance policy provides coverage for that period. A shorter policy term can leave a gap while the loan is still outstanding.
Claim settlement information:
Claim settlement information can be one factor in your comparison, but it should not be the only basis for choosing an insurer.
Check the latest claim-related information published by the insurer and understand what the reported ratio measures before comparing different companies.
Additional riders:
You can also opt for add-on riders like Critical Illness Benefit and Accidental Death Cover as additional rider options to enhance your coverage.
Check the specific rider's eligibility, exclusions, benefit conditions and additional premium before adding it to your policy.
Premium affordability:
Your premium should fit within your regular financial commitments throughout the premium-paying period.
When comparing premiums, consider the sum assured, policy term and profile used for the quotation. A lower premium should not be viewed separately from the amount and duration of cover provided.
Flexibility:
Review the policy terms for provisions that apply if your financial circumstances or loan structure changes.
Check the rules for changes to cover, nomination, assignment and other applicable policy provisions before purchasing.
Compare term insurance plans to review the cover amount, policy term and available rider options for your home loan requirements, and get a quote based on your financial responsibilities.
How much does a term insurance cost for securing home loan?
| Factor | How it affects the premium |
|---|---|
| Age | Premium is influenced by your age when you apply |
| Loan or cover amount | Higher life cover can increase the premium |
| Policy term | A longer period of cover can affect the premium |
| Health status | Your health information and underwriting can affect the premium |
| Smoking habits | Smoking status can affect the premium |
| Additional riders | Adding applicable riders can increase the total premium |
For example, two borrowers with the same home loan amount may receive different premiums because their ages, health profiles and smoking status differ.
Check your premium estimate using your actual age, required cover and policy term rather than relying on a general premium figure.
Conclusion
Term insurance helps your family manage the outstanding home loan if you die during the policy term. The death cover can provide funds towards the loan, subject to the cover amount, claim and policy terms.
When selecting term insurance for home loan protection, assess the outstanding loan, remaining repayment period and your family's other financial obligations. This helps you determine whether the policy should cover only the home loan or also provide additional financial support.
You should also compare the premium, policy term, sum assured and applicable riders before making a decision. Review the policy document carefully to understand the exclusions, conditions and benefits. Get a quote based on the protection your family may need.
Explore more and stay informed
Frequently asked questions
Term insurance for home loan
How does term insurance provide financial security for a home loan borrower?
Term insurance can provide your family with a death benefit when you die during the policy term. They can use this money to manage the outstanding home loan and other financial responsibilities, subject to the policy terms. The protection depends on the sum assured you choose, so a policy intended only to cover the loan may not provide enough funds for other household needs.
What are the key features of term insurance plans for home loans?
Key features include a defined policy term, a selected sum assured and a death cover payable according to the policy terms. Term insurance can provide a substantial cover amount, and the policy tenure can be aligned with your home loan repayment period. Depending on the plan, additional riders such as Critical Illness Benefit or Accidental Death Cover may also be available.
How can you compare term insurance costs for a home loan?
Compare premiums using the same cover amount and policy term wherever possible. Your age, health status, smoking habits, cover amount and selected riders can affect the quoted premium. You should also check how long you need to pay the premium and how long the life cover continues. Looking only at the lowest quoted premium may not give you a meaningful comparison.
What factors should you consider when choosing term insurance for a home loan?
Start with the outstanding home loan and remaining repayment period. Then consider your family's household expenses, other debts and long-term financial responsibilities. Review the sum assured, policy tenure, premium, exclusions and available riders. You can also review the insurer's latest claim-related information. Read the policy document to understand nomination, assignment and other provisions that can affect the claim.
How does term insurance provide financial security for a home loan borrower?
Term insurance can provide your family with a death cover when the insured dies during the policy term. They can use this money to manage the outstanding home loan and other financial responsibilities, subject to the policy terms. The protection depends on the sum assured you choose, so a policy intended only to cover the loan may not provide enough funds for other household needs.
Is term insurance mandatory for a home loan?
No, term insurance is not mandatory for getting a home loan in India. The Reserve Bank of India (RBI) and the Insurance Regulatory and Development Authority of India (IRDAI) do not require borrowers to purchase a term insurance policy as a condition for loan approval.
However, term insurance can help your family manage the outstanding home loan if the life insured dies during the policy term. You can choose cover based on the loan amount, remaining repayment period and other financial responsibilities.

Related articles
T&C Apply. #Above illustration is considering Male aged 25years | Non-Smoker | Policy Term(PT)– 30 years | Premium Payment Term (PPT)– 30 years | Sum Assured opted is Rs.1,00,00,000 | Offline Channel | Standard Life | Yearly Premium is Rs. 5,417. Total Premium Rs.1,62,518 | Medical Rates | Yearly Premium Payment Mode | Death benefit opted is lumpsum payout and monthly instalments (Lumpsum Payout Percentage: 40, Income Payout Percentage: 60). Income payout instalment opted for 40 years | Premium shown above is exclusive of Goods & Service Tax/ any other applicable tax levied, subject to changes in tax laws, and any extra premium and is for illustrative purpose only.