- High coverage at a low premium
- Financial protection for your family’s future
- Tax benefits up to Rs. 46,000`` under Section 80C and 10(10D)
- Dedicated claim assistance
- Customisable plans to suit your needs
-
People’s trust in Bajaj
-
10 million+
Customers
-
3
Insurance partners
Nomination in Life Insurance- Key Benefits, Types and How to Choose the Right Nominee
In summary
Nomination in life insurance lets you name one or more people to receive the policy money when the policyholder dies. You can generally make or change a nomination before the policy matures.
- You can nominate one or more people and specify their shares where applicable.
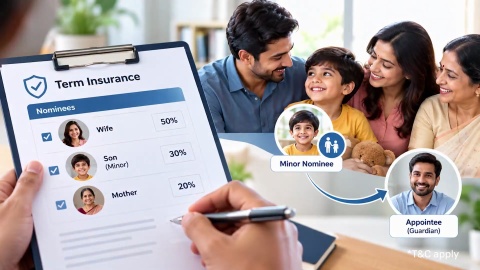
- You can nominate a minor if you appoint an adult appointee to receive the money during the minor’s minority.
- Parents, spouse and children can have beneficial entitlement under Section 39, subject to applicable conditions.
- You should review the nomination after marriage, the birth of a child, divorce or the death of a nominee.
If your financial responsibilities have changed, reviewing your life cover and nomination together can help keep your protection plan aligned with your family’s needs.
What is a nominee in life insurance?
Under Section 39 of the Insurance Act, 1938, a policyholder can nominate one or more people when taking the policy or before it matures. You can also change a nomination before maturity by following the applicable process. A nominee may be a family member such as a spouse, child or parent. Depending on the policy and applicable rules, you may also nominate another person.
A nominee should not automatically be described as the legal owner of the policy money in every situation. The legal effect of nomination can depend on the nominee's relationship to the policyholder and the applicable provisions of Section 39.
Why is nomination important in life insurance?
Key reasons to maintain a valid nomination include:
| Reason | How nomination helps |
| Claim processing | Identifies the person or people nominated to receive the policy money |
| Family support | Helps direct policy proceeds towards the people you have chosen |
| Minor nominee | Allows an appointee to receive the money for a minor nominee |
| Multiple nominees | Lets you nominate more than one person where permitted and specify their respective shares |
| Life changes | Allows you to update the nomination when your circumstances change |
For certain nominee categories, Section 39 provides beneficial entitlement to the policy money, subject to the conditions set out in the law. This includes parents, spouse and children, or any of them, where the relevant conditions apply.
If your family responsibilities have changed, you can also review whether your existing life cover remains suitable before getting a quote.
How do you choose the right nominee for life insurance?
Consider these points before making or updating a nomination:
- Relationship with the nominee: Ideally, choose someone emotionally close and financially dependent on you—like a spouse, parent, or child.
- Financial dependency: Think about who depends on your income for regular expenses, education, healthcare or other needs.
- Age and health of the nominee: If your nominee is elderly or has health issues, it might be wise to choose a younger backup (contingent nominee).
- Minor as nominee: If you’re naming a child, appoint a trustworthy guardian to manage the funds until they come of age.
- Money management ability: Ensure the nominee is responsible and capable of using the claim amount wisely for family needs.
- Changing family structure: Life changes like marriage or having children should prompt you to revisit your nominee choice.
- Legal eligibility: The nominee must be legally eligible to receive the funds. Some insurers require relationship proof.
- Multiple nominees: If you nominate more than one person, clearly record each nominee's applicable share.
- Keep nominations updated: Review your nomination in life insurance regularly, especially after major life events.
The right nominee is therefore not simply the person closest to you. The choice should reflect your current family and financial responsibilities.
What are the types of nominees in life insurance?
- Individual nominee: A person named by the policyholder to receive the policy proceeds after the life assured’s death.
- Multiple nominees: The policyholder can nominate more than one person to receive the policy proceeds.
- Minor nominee: A person below 18 years can be nominated. The policyholder can appoint an appointee to receive the money on the minor nominee’s behalf until the nominee attains adulthood.
- Beneficial nominee: Under Section 39, a policyholder may nominate their parents, spouse or children, subject to the applicable legal provisions. Such nominees have specific rights under the law.
The nomination should be recorded with the insurer. A nomination can also be changed or cancelled before the policy matures, subject to the prescribed process.
Who can be a nominee in a life insurance policy?
| Type of nominee | Who can be nominated | Key point |
|---|---|---|
| Beneficial nominee | Parents, spouse or children | May have beneficial entitlement under Section 39 |
| Minor nominee | A person below 18 years | An adult appointee can receive the proceeds on the minor’s behalf |
| Non-family nominee | Other eligible person | Rights depend on the applicable provisions of Section 39 |
| Multiple nominees | Two or more persons | Applicable shares should be specified in the nomination |
What is the difference between a nominee and a beneficiary?
| Aspect | Nominee | Beneficial entitlement |
| Meaning | Person named by the policyholder under the policy | Legal entitlement to policy money under applicable provisions |
| Appointment | Made by the policyholder | Can arise under Section 39 for specified nominee categories |
| Multiple people | One or more people may be nominated | Entitlement depends on the applicable legal provisions |
| Minor | A minor can be nominated with an adult appointee | The appointee receives the money for the minor during minority |
Under Section 39, parents, spouse and children, or any of them, can have beneficial entitlement where the relevant conditions apply. Therefore, “nominee” and “beneficiary” should not always be treated as interchangeable terms.
How can you change your nominee in life insurance?
The usual process involves these steps:
- Check your policy details: Keep your policy number and current nomination details available.
- Request a nomination change: Use the insurer’s available policy servicing channel or prescribed form.
- Provide the new nominee’s details: Enter the required personal and relationship information accurately.
- Add an appointee if required: If the new nominee is a minor, provide the details of an eligible adult appointee.
- Submit the request: Send the completed request and supporting documents, if required, through the insurer’s specified channel.
- Confirm the update: Check that the insurer has recorded the revised nomination.
Insurers may offer online or service-request options to update nomination details. The exact process and required documents can vary by insurer.
What documents are needed to update a nominee in life insurance?
| Document | What it may include | Why it may be needed |
|---|---|---|
| Nomination form or endorsement | Nomination/change request and nominee details | Records the new or revised nomination |
| Nominee identity proof | Aadhaar, PAN or other accepted ID | Verifies the nominee’s identity |
| Relationship proof | Marriage certificate, birth certificate or other applicable document | Establishes the nominee’s relationship with the policyholder, where required |
| Address proof | Aadhaar, passport, voter ID or other accepted document | Verifies the nominee’s address, where required |
| Original policy document | Policy bond or policy details | May be required for endorsement or verification |
The insurer records the change after receiving the required request and documents. Section 39 of the Insurance Act also provides for written acknowledgement when a nomination or its cancellation or change is registered.
What are a life insurance nominee’s rights and responsibilities?
The nominee should provide the insurer with the required claim documents and cooperate with the claim-settlement process. The nominee should also ensure that their personal and bank details are accurate when submitting a claim.
A nomination does not remain unchanged in every circumstance. For example, a policy assignment can affect or cancel a nomination under Section 39, subject to specified exceptions.
Conclusion
Review your nomination after major family or financial changes, such as marriage, childbirth, divorce or the death of a nominee. If you have a minor nominee, make sure an eligible adult appointee is included as required.
Whether you hold a term insurance plan or another life insurance policy, keeping your life cover and nomination details up to date can help your policy reflect your family's needs.
If your family responsibilities have changed, review your life cover as well and get a quote based on your protection needs.
Explore more and stay informed
Frequently asked questions
Nomination in life insurance
What is a nominee in life insurance?
A nominee is a person you name to receive the policy money when the life insured dies. You can generally nominate one or more people under a life insurance policy. If you nominate a minor, you can appoint an adult appointee to receive the money during the minor’s minority. The legal entitlement to the proceeds can depend on the nominee’s relationship with you and applicable provisions under Section 39.
Why is nomination important in life insurance?
Nomination records the person or people you have chosen to receive the policy money. It clarifies who should receive the proceeds and helps keep your policy records aligned with your wishes. You can also review or change the nomination when your family circumstances change, subject to the policy and applicable legal requirements.
What is a nomination with an example?
A nomination in life insurance involves specifying an individual who will receive the policy proceeds after the policyholder's death. For example, if a person purchases a life insurance policy and nominates their spouse as the nominee, the spouse will receive the insurance proceeds in the event of the policyholder's demise.
Can a sibling be a nominee in life insurance?
Yes, a sibling can be nominated as a beneficiary in a life insurance policy. Policyholders have the flexibility to nominate any individual, including siblings, children, parents, or other relatives, as the nominee to receive the insurance proceeds upon their demise.
What if I don’t mention a nominee in my life insurance policy?
If there is no valid nomination, the policy proceeds may need to be paid to the applicable legal heirs, legal representatives, or another person entitled under the applicable law and policy terms. The exact process depends on the circumstances and documents required. Keeping your nomination updated can help avoid uncertainty when the policy proceeds become payable.
How can I update or add a nominee in my policy?
You can generally add or change a nominee before the policy matures by submitting the required request to your insurer. Depending on the insurer, you may be able to use an online policy account, service request or prescribed form. The change takes effect once the insurer records it as required.
Is it possible to choose more than one nominee?
Yes, a policyholder can nominate more than one person under Section 39. When you name multiple nominees, clearly record each nominee's share. If you later want to change the people nominated or their shares, you can generally update the nomination before the policy matures by following the insurer’s process.
Can the nominee also be the life insurance beneficiary?
A nominee can have beneficial entitlement in specified circumstances. Under Section 39, parents, spouse and children, or any of them, can be beneficially entitled to the policy money subject to the applicable conditions. Therefore, whether a nominee is also beneficially entitled depends on the nominee’s relationship with the policyholder and the relevant legal provisions.
Do you have to list a beneficiary for life insurance?
No. Nomination is not mandatory for a life insurance policy. However, you can nominate one or more people to receive the policy proceeds. A valid nomination can make it easier for the insurer to identify the intended recipient and process the claim.
Can a life insurance nominee use the payout, or must they pass it to legal heirs?
A nominee who is the policyholder’s parent, spouse, or child can generally use the life insurance payout for themselves, because Section 39(7) of the Insurance Act, 1938 makes such nominees beneficially entitled to the proceeds. They do not have to pass the money to other legal heirs.
Does a nominee get interest on delayed insurance claims?
Yes, applicable regulations provide for interest when an insurer delays claim payment beyond the prescribed timeline. Under IRDAI’s framework, interest may be payable from the date of receiving the last necessary document until payment, subject to the applicable rules and circumstances.
What happens if I provide incorrect nominee information?
Incorrect or incomplete nominee details can create difficulties in identifying or verifying the intended recipient and may delay claim processing. If you notice an error, inform the insurer and request a nomination update promptly, following the insurer’s prescribed process and documentation requirements.
Can a nomination be changed or cancelled under the Married Women's Property Act?
A policy covered by Section 6 of the Married Women’s Property Act is treated differently from an ordinary life insurance nomination. Section 39 of the Insurance Act generally does not apply to such policies, so nomination changes or cancellations depend on the specific policy and legal structure.