







An OTP will be sent to this number for verification

You may have a pre-approved offer
Enter required loan against property amount
In summary
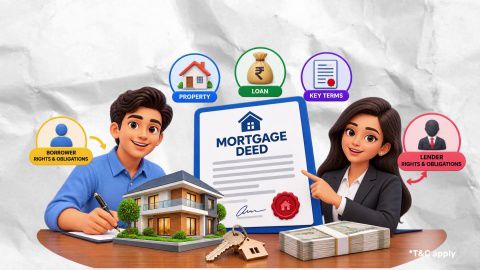
What is a Mortgage Deed - Meaning, Types & Key Elements
A mortgage deed records the terms under which property is mortgaged to secure a loan or other financial obligation. Its legal requirements depend on the type of mortgage and applicable law.
- The Transfer of Property Act, 1882 defines a mortgage as a transfer of an interest in specific immovable property to secure a financial obligation
- Common mortgage forms include simple, usufructuary, English and mortgage by deposit of title deeds
- A mortgage deed can contain details of the parties, property, loan amount, repayment terms, rights, obligations and default provisions
- State laws can determine applicable stamp duty and registration requirements
A mortgage deed does not by itself mean that the lender becomes the permanent owner of the property. The rights created depend on the type and terms of the mortgage.
What is a mortgage deed?
A mortgage deed is an instrument through which an interest in specific immovable property is created or transferred as security for a loan, debt or other financial obligation. The Transfer of Property Act, 1882 defines a mortgage and identifies the property owner as the mortgagor and the person receiving the security interest as the mortgagee. The deed can record the property details, secured amount, repayment terms, obligations of the parties and consequences of default. The exact legal effect depends on the type of mortgage used. A mortgage deed is different from a sale deed. A sale deed records a transfer of ownership, while a mortgage creates a security interest in property to secure an obligation.
What are the types of mortgage deeds?
The Transfer of Property Act, 1882 recognises different forms of mortgages. Their main differences relate to possession, the rights created in favour of the mortgagee and how the security operates.
| Mortgage type | How it works | Possession |
|---|---|---|
| Simple mortgage | The mortgagor remains personally liable to repay and agrees that the mortgagee can seek sale of the property to recover the mortgage money in case of default. | Remains with mortgagor |
| Usufructuary mortgage | The mortgagor gives possession to the mortgagee, who can receive rents or other income from the property towards the mortgage debt. | Transfers to mortgagee |
| English mortgage | The mortgagor transfers the property absolutely to the mortgagee, subject to re-transfer when the mortgage money is paid as agreed. | Depends on the terms |
| Mortgage by deposit of title deeds | The borrower delivers title documents to the creditor with the intention of creating security over the property. | Usually remains with borrower |
The Transfer of Property Act, 1882 also recognises mortgage by conditional sale and anomalous mortgage. An anomalous mortgage is a mortgage that does not fall within the other specified categories.
What does a mortgage deed contain?
A mortgage deed should clearly identify the transaction and the obligations created by it. The exact contents can vary according to the mortgage structure and applicable law.
| Key element | What it covers |
|---|---|
| Parties | Names and details of the mortgagor and mortgagee |
| Property | Address, description, boundaries, size and ownership or title details |
| Secured amount | Loan or debt secured by the mortgage |
| Repayment terms | Tenure, instalment schedule and applicable interest terms |
| Rights and obligations | Duties of the borrower and rights available to the lender |
| Covenants | Conditions relating to property upkeep, insurance or payment of applicable dues |
| Default provisions | Consequences and remedies if repayment obligations are not met |
| Possession | Conditions governing possession where relevant to the mortgage type |
| Execution and registration | Signing, witnessing, stamp duty and registration requirements applicable to the transaction |
Review the property description and title details carefully before signing. Errors in the property identification or party details can create problems when the document is relied upon later.
When do you need a mortgage deed?
You need documentation that legally creates the mortgage when you use immovable property as security for a loan or another secured obligation. The specific document and formalities depend on the mortgage structure and applicable law.
For example, a borrower taking a loan against property may mortgage eligible property to secure the borrowing. Bajaj Finance currently offers loan against property with loan amounts of up to Rs. 15.50 crore* and repayment tenure of up to 15 years*, subject to applicable eligibility and terms.
Show More
Show Less
Why is a mortgage deed important?
A mortgage deed provides a formal record of the security arrangement and helps both parties understand their contractual obligations.
It can help establish:
- The property offered as security.
- The amount or obligation secured by the mortgage.
- The repayment terms agreed between the parties.
- The rights and obligations of the mortgagor and mortgagee.
- The consequences of failing to meet the agreed obligations.
- The conditions governing possession where applicable.
- The process for redemption or release of the mortgage after repayment.
The mortgage deed therefore serves a different purpose from a document that transfers ownership outright. Its legal effect depends on the mortgage created under the transaction.
How do you execute a mortgage deed?
The execution process depends on the type of mortgage, property and applicable state requirements. A typical process involves the following steps:
- Prepare the deed
Include the parties, property description, secured amount, repayment terms, rights and obligations. - Verify property documents
Check the title documents, ownership records and property details for accuracy. - Confirm the mortgage terms
Review the secured amount, interest terms, repayment schedule and default provisions. - Complete applicable stamp formalities
Use the stamp duty requirements applicable in the relevant state. - Sign the document
The parties execute the document in the manner required for the particular mortgage. - Complete registration where required
Register the instrument with the appropriate authority when registration is required under applicable law. - Retain the executed records
Keep the registered document and related property and loan records for future reference.
For a mortgage covered by Section 59 of the Transfer of Property Act, 1882, the registered instrument must be signed by the mortgagor and attested by at least two witnesses. A mortgage by deposit of title deeds is expressly treated differently under that section.
What should you check before signing a mortgage deed?
Read the document carefully before execution and verify the following:
- Names and details of all parties.
- Property address, boundaries and description.
- Ownership and title information.
- Secured loan or debt amount.
- Interest and repayment terms.
- Default and enforcement provisions.
- Possession-related clauses.
- Insurance, tax and property-maintenance obligations, where applicable.
- Stamp duty and registration requirements.
- Conditions for redemption or release of the mortgage.
If the transaction involves a complicated title, multiple owners, inherited property or state-specific requirements, consider obtaining independent legal advice before signing.
Mortgage deed vs agreement to mortgage
A mortgage deed creates an immediate security interest or charge over the property, whereas an agreement to mortgage generally records a promise to create the security in the future. This distinction forms an important part of the mortgage deed meaning.
| Parameter | Mortgage deed | Agreement to Mortgage |
| Legal effect | Creates a charge/security interest on the property. | Records an agreement to create security later. |
| Enforceability | Rights arise under the executed mortgage arrangement. | Generally requires a further deed to create the mortgage. |
| Registration | Registration requirements depend on the mortgage and applicable law. | Registration requirements depend on its terms and applicable law. |
| When used | Typically executed when creating the mortgage security. | Often used during loan negotiation or before final security creation. |
| Lender's rights | Provides security rights subject to the mortgage terms and law. | Does not by itself create the same immediate security interest. |
For a mortgage deed in India, the applicable requirements should be checked under the Transfer of Property Act, 1882 and the Registration Act, 1908.
What happens after the mortgage is repaid?
Repayment of the secured obligation does not mean that you should ignore the formal release of the mortgage. The documents and steps required to release or acknowledge extinguishment of the mortgage depend on how the mortgage was created.
Section 60 of the Transfer of Property Act, 1882 recognises the mortgagor's right of redemption, subject to the conditions set out in the law and the mortgage arrangement. On redemption, the mortgagor can require the mortgagee to return relevant documents and, where applicable, re-transfer the property or acknowledge that the mortgagee's transferred interest has been extinguished.
How does a mortgage deed matter for a loan against property?
When you apply for a Loan Against Property, the lender may require legal documentation to establish the property's use as security for the loan. A mortgage deed can be part of this process, depending on the lender and applicable legal requirements.
It is important to distinguish a mortgage deed from documents that prove ownership or determine the property's value.
| Document | Purpose |
|---|---|
| Mortgage deed | Sets out the terms under which the property is mortgaged as security for the loan |
| Title or ownership documents | Establish the borrower's ownership or legal rights over the property |
| Property valuation report | Helps determine the property's assessed value |
| Property-tax records | Provide information about the property's tax status |
| Property records | Provide details used during property and legal verification |
A mortgage deed by itself does not establish your eligibility for a Loan Against Property. The lender may also assess the property's legal status and value, your income and repayment capacity, credit profile, and other applicable eligibility criteria.
If you are considering a secured loan, you can check your eligibility for a Bajaj Finance Loan Against Property and review the applicable documentation and loan terms.
Frequently Asked Questions
Overview
What documents are needed for a mortgage deed?
Documents commonly needed for a mortgage deed include the title deed, sale deed, property ownership proof, identity and address proofs, property tax receipts, encumbrance certificate, approved building plan and loan-related documents. The exact list varies by lender, property type and state. The Sub-Registrar may also require photographs, witnesses and additional documents before registration.
What is the difference between a lease deed and a mortgage deed?
A lease deed gives a tenant the right to possess and use property for a specified period in exchange for rent or consideration. A mortgage deed creates security over immovable property for repayment of a debt. A lease concerns temporary use or possession, while a mortgage primarily secures a financial obligation in favour of the lender.
What is a mortgage deed with possession and when does it apply?
A mortgage deed with possession is a mortgage arrangement where possession of the property is given or agreed to be given to the mortgagee. It may apply where the lender is entitled to receive rents, profits or other income from the property towards the secured debt. Applicable stamp duty and registration requirements depend on the state and mortgage structure.
How do you execute and register a mortgage deed in India?
To execute and register a mortgage deed in India, prepare the deed, verify ownership and property records, pay applicable stamp duty, have all parties sign it with required witnesses, and present it before the appropriate Sub-Registrar. Registration requirements depend on the nature of the mortgage and applicable law. The Registration Act, 1908 governs compulsory registration of specified property instruments.
How does a mortgage deed protect both the borrower and the lender?
A mortgage deed protects the lender by legally documenting the security interest and repayment obligations, while protecting the borrower by recording the loan amount, property details, repayment terms, rights and conditions for release of the mortgage. A properly registered document also provides stronger legal evidence of the agreed transaction and its terms.
Can a mortgage deed be cancelled or modified after registration?
Yes, a mortgage deed can generally be modified, released or discharged after registration when the parties have a valid legal basis and follow applicable procedures. Full repayment may result in a release or reconveyance of the mortgage. Material changes may require a supplementary or fresh registered instrument, with applicable stamp duty and registration charges.
What are the essential clauses in a mortgage deed?
Essential clauses in a mortgage deed generally cover the parties' details, property description, loan amount, interest rate, repayment schedule, mortgage type, possession terms, borrower and lender obligations, default consequences, redemption conditions, representations, dispute resolution and execution details. Clear clauses help establish the lender's security rights while documenting the borrower's obligations and conditions for release.
What is the stamp duty applicable on a mortgage deed in India?
There is no single nationwide stamp duty rate for every mortgage deed in India because stamp duty is governed by applicable state laws. The amount can depend on the mortgage type, secured amount, possession terms and property location. For example, state schedules may prescribe different rates for mortgages with or without possession. Always verify the current rate with the relevant state authority before execution.
Loan Against Property for different budget
Check your pre-approved offer now
Loan Against Property for Professionals
Find your nearest branch

What do our customers say about us
customers
Play Store rating
reviews
Anita Das
04 March 2026
The loan against property process was smooth and transparent. Interest rates were competitive, and the documentation requirements were minimal. The team provided clear guidance at every step, making the entire experience hassle-free. Highly recommended for quick approvals and reliable support.
Aashish
04 March 2026
The loan disbursal was quick, and the customer support team handled all my queries with patience and clarity. Flexible EMIs made it easy to manage monthly expenses. Overall, a great experience, especially for salaried individuals seeking a loan against property.
Prakash
04 March 2026
I had a great experience transferring my existing loan against property. The process was quick and hassle-free, and I saved significantly with the lower interest rate. The customer service team was supportive throughout. Highly recommended for anyone considering a balance transfer.
Yogesh Singh
04 March 2026
Clear guidance, quick approval, and flexible repayment options made purchasing my new house much easier than expected. The team managed the entire process professionally and ensured smooth coordination at every stage. Overall, a very satisfying experience, and I would recommend their home loan services to others.
Related articles
Watch our videos
Know the tax benefits on your loan against property
What are the documents required for a Loan Against Property?
What are the types of property eligible for Loan Against Property
What is the eligibility criteria for a Loan Against Property
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (NBFC) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.