A CIBIL score is an important number that shows how good you are at managing credit. It is a three-digit score that banks and lenders use to check your credit history and decide if you are a reliable borrower. Checking your CIBIL score regularly helps you keep track of your credit health and make better financial decisions.
What is a credit score and why does it matter?
A credit score is a three-digit measure of your creditworthiness, generally ranging from 300 to 900 and calculated by credit bureaus such as TransUnion CIBIL.
| Score Range | Description | What it means for loan approval |
|---|
| 300–600 | Poor | High risk of rejection |
| 601–700 | Average | Limited offers, higher rates |
| 701–760 | Good | Better chances of loan approval |
| 761–800 | Very Good | Better rates and offers |
| 801–900 | Excellent | Stronger chances of favourable rates and pre-approved offers |
A score of 760+ is generally preferred by many lenders, although approval decisions depend on individual lending policies. You can use the Bajaj Finance free credit check to review your profile and complete a CIBIL score check for free.
How does a credit score work?
A credit score is calculated by credit bureaus using your credit behaviour and information reported by lenders.
India has four major credit bureaus: TransUnion CIBIL, Experian, Equifax, and CRIF High Mark. Each bureau calculates your CIBIL score or other credit score using the information available in your credit report.
From July 2026, the RBI has directed banks and NBFCs to report credit information to bureaus up to 4 times a month, on the 9th, 16th, 23rd and last day of each month. This allows your score to reflect recent credit activity more frequently than before.
The factors that influence your score are covered in the next section. You can also learn how to check your credit score online.
How to check your CIBIL score using your PAN card
You can use your PAN card details to check your CIBIL score online through a trusted financial service. Your PAN helps verify your identity and retrieve your credit information.
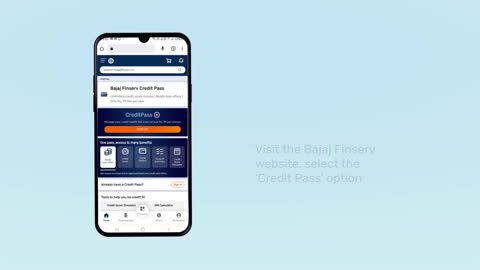
- Visit the Bajaj Finance Credit Pulse Report page or open the Bajaj Finance app.
- Enter your registered mobile number and select “Check Score”.
- Complete the OTP verification sent to your mobile number.
- Enter your PAN card number and other required details.
- Submit the details to retrieve your CIBIL score and credit report.
- Review your score and credit information.
- Download or save the report for future reference.
A Check CIBIL Score by PAN card number process can help you access your credit information through a free credit score check.
Why is your CIBIL score important?
Your credit score is among the first factors lenders check when assessing your creditworthiness. A score of 750+ can improve your chances of accessing loans and favourable credit terms.
| Benefit | What it means | Score threshold |
|---|
| Higher loan approval chances | A score of 750+ can significantly improve your chances of loan approval. | 750+ |
| Lower interest rates | Lenders may offer better rates to borrowers with stronger credit profiles. | 760+ |
| Faster processing | Pre-approved offers can reduce documentation and turnaround time. | 750+ |
| Higher credit card limits | Strong credit profiles may help you access higher spending limits. | 750+ |
| Better negotiating power | A strong score may give you more scope to negotiate applicable fees and terms. | 780+ |
These thresholds are indicative, as lenders apply their own credit policies. You can check credit score through a free CIBIL score check with Bajaj Finance.
How to check your CIBIL score for free?
Yes, you can check your credit score for free online in a few minutes through Bajaj Finance, with no impact on your score. This section explains how to check your credit score using the Credit Pulse Report.
- Visit Bajaj Finance: Open the credit score check page. This supports a free online credit score check.
- Verify your mobile: Enter your mobile number and complete OTP verification.
- Confirm your identity: Provide your PAN card details when requested for verification.
- View your report: Access your free CIBIL score and download your Credit Pulse Report.
Checking your score through this process is a soft inquiry and does not affect your CIBIL score. Keep your mobile number and PAN details ready to complete the OTP-based check.
What is a good CIBIL Score?
A CIBIL score of 760 or above is generally considered a good credit score by most lenders. Achieving and maintaining a score within this range, ideally closer to 900, significantly enhances loan and credit card approval prospects. It is crucial to monitor credit scores from multiple bureaus as they can vary. Regular credit score checks, at least monthly, are recommended.
Benefits of a good CIBIL Score
A strong credit score is a key factor in loan and credit card applications. It positively influences lender perception of creditworthiness and repayment capacity.
Benefits include:
- Increased loan approval likelihood
- Lower interest rates on loans
- Faster and easier loan and credit card approvals
- Access to pre-approved loan offers
- Higher credit card limits
- Reduced processing fees and other charges
While a significant factor, credit score is not the sole determinant. Lenders also assess income, repayment capacity, debt-to-income ratio, employment history, and profession.
How a CIBIL Score is calculated?
Credit bureaus calculate CIBIL scores based on various factors reflecting past credit behaviour. These factors are reported by banks and NBFCs with each credit application.
What are the 5 factors that affect your CIBIL score?
The five factors that affect your credit score and CIBIL score are repayment history, credit utilisation, length of credit history, hard inquiries and credit mix.
| Factor | Impact level | Weightage | How to manage it |
|---|
| Repayment history | High | ~35% | Pay EMIs and credit card bills on time. |
| Credit utilisation ratio | Moderate | ~30% | Keep usage below 30% of your credit limit. |
| Length of credit history | Moderate | ~15% | Avoid closing your oldest credit accounts. |
| Number of hard inquiries | Moderate | ~10% | Limit frequent applications for new credit. |
| Credit mix | Low | ~10% | Maintain a mix of secured and unsecured credit. |
If you are asking what the factors that impact my CIBIL score are, these five areas are key. Review your credit health report regularly for errors and keep your repayment record accurate.
What causes a low CIBIL score?
Missed payments and high credit utilisation are the two most common causes of a low CIBIL score, while other credit-report issues can also lower your credit score.
- Missed or late payments: Delayed EMIs or credit card payments can negatively affect your score.
- High credit utilisation: Consistently using most of your available credit can reduce your score.
- Credit report errors: Incorrect or outdated information can affect your reported credit profile.
- Excessive hard inquiries: Frequent credit applications can have a negative impact.
- Closing old accounts: Closing your oldest credit accounts can reduce the length of your credit history.
- Settled accounts: Settling a debt for less than the full amount can negatively affect your credit profile.
Negative information such as missed payments or loan defaults can remain on your credit report for up to 7 years; DPD (Days Past Due) entries remain for 3 years.
How to improve your CIBIL Score?
Improving your credit score takes consistent positive behaviour over time; meaningful progress typically takes 3–6 months.
- Pay on time: Pay all EMIs and credit card bills by their due dates. This is the highest-impact action.
- Keep utilisation below 30%: Use less than 30% of your total available credit limit where possible.
- Limit new applications: Avoid applying for multiple loans or credit cards within a short period.
- Check for errors: Review your credit report and raise a dispute promptly if you find incorrect entries.
- Keep old accounts open: Closing your oldest credit account can shorten your credit history.
- Maintain a credit mix: A balanced mix of secured and unsecured credit can support your profile.
Meaningful improvement typically takes 3–6 months of consistent positive behaviour, and your score cannot improve overnight. Monitor progress with a free CIBIL score check through Bajaj Finance; scores can be updated up to 4 times a month.
What is the difference between a credit score and a CIBIL score?
A credit score is a general measure of your creditworthiness, while a CIBIL score is a specific credit score provided by TransUnion CIBIL in India. Other bureaus, including Experian, Equifax and CRIF High Mark, also provide credit scores.
| Criteria | Credit score | CIBIL score |
|---|
| Definition | A numerical measure of your creditworthiness based on your credit history and behaviour. | A specific credit score provided by TransUnion CIBIL. |
| Calculation | Calculated by credit bureaus using information in your credit report. | Calculated by CIBIL using credit information reported by lenders. |
| Range | Generally ranges from 300 to 900 in India. | Ranges from 300 to 900. |
| Providers | Available from multiple credit bureaus, including CIBIL, Experian, Equifax and CRIF High Mark. | Provided by TransUnion CIBIL. |
| Use | Helps lenders assess your credit profile when you apply for credit. | Used by lenders as one factor when assessing credit applications. |
In short, every CIBIL score is a credit score, but not every credit score is a CIBIL score.
What information CIBIL Scores do not consider?
CIBIL scores primarily assess credit history. They generally do not consider factors like:
- Income: Your salary or earning potential is not directly factored in.
- Savings: The amount of money you have in savings accounts is not considered.
- Employment status: While past employment history can indirectly impact credit history, current employment status itself is not a direct factor.
- Education: Your educational background is not directly assessed in the scoring model.
- Lifestyle: Your personal habits or lifestyle choices are not considered in the scoring calculation.
Why there are different CIBIL Scores?
Multiple CIBIL scores may exist for an individual due to variations in the scoring models used by different lenders and credit bureaus. These variations can arise from:
- Different scoring models: Lenders and credit bureaus may utilize different scoring models to assess credit risk, leading to variations in scores.
- Data sources: The specific data used for scoring may differ slightly between models, impacting the final score.
- Focus on specific credit types: Some scores may focus more heavily on specific types of credit, such as mortgage loans or auto loans.
Why your CIBIL Score changed?
Several factors can cause your CIBIL score to change:
- Late payments: Missed or delayed payments on loans or credit cards significantly impact your score.
- High credit utilisation: Maintaining high credit card balances relative to your credit limits can negatively affect your score.
- New credit applications: Multiple credit inquiries within a short period can slightly lower your score.
- Account age: Closing older credit accounts can shorten your average credit age, potentially impacting your score.
- Public records: Negative public records like bankruptcies or judgments can significantly lower your score.
Monitor your credit report and score
Regularly monitoring your credit report and score is crucial:
- Identify errors: It helps you identify and dispute any inaccuracies in your credit report.
- Detect fraud: Early detection of fraudulent activity can help minimise potential damage.
- Track creditworthiness: Monitoring your score helps you understand your creditworthiness and make informed financial decisions.
- Improve your score: By identifying areas for improvement, you can take steps to enhance your creditworthiness.
How CIBIL score impacts loan and credit card eligibility?
Your CIBIL Score significantly influences your eligibility for loans and credit cards:
- Loan approval: A higher score increases your chances of loan approval and can qualify you for better interest rates.
- Credit card limits: A good score can help you obtain credit cards with higher credit limits.
- Loan amounts: A higher score may allow you to borrow larger loan amounts at favourable terms.
- Interest rates: Lenders often offer lower interest rates to borrowers with strong credit histories.
What is the difference between a credit score and a CIBIL score?
A credit score is a general measure of your creditworthiness, while a CIBIL score is a credit score provided by TransUnion CIBIL in India. Other bureaus, such as Experian, Equifax and CRIF High Mark, also provide credit scores. Scores can differ across bureaus because each may use its own scoring model and the credit information available to it.
| Criteria | Credit score | CIBIL score |
|---|
| Definition | A numerical measure of your creditworthiness based on your credit history and behaviour. | A specific credit score provided by TransUnion CIBIL. |
| Calculation | Calculated by credit bureaus using information in your credit report. | Calculated by CIBIL using the credit information it receives from lenders. |
| Range | Generally ranges from 300 to 900 in India. | Ranges from 300 to 900. |
| Providers | Available from multiple credit bureaus, including CIBIL, Experian, Equifax and CRIF High Mark. | Provided by TransUnion CIBIL. |
| Use | Helps lenders assess your credit profile when you apply for credit. | Used by lenders in India as one factor when assessing credit applications. |
In short, every CIBIL score is a credit score, but not every credit score is a CIBIL score.
Why did your CIBIL score change?
Your CIBIL score or credit score can change whenever lenders report new information about your borrowing and repayment behaviour.
- Late payments: Missed or delayed loan or credit card payments can negatively affect your score.
- High credit utilisation: Using a large share of your available credit limit can lower your score.
- New credit applications: Multiple hard inquiries within a short period can affect your score.
- Account age: Closing older credit accounts can shorten your credit history and affect your score.
- Public records: Certain negative records can have a significant impact on your credit profile.
From July 2026, lenders are required to report credit data to bureaus up to 4 times a month, meaning your score can change more frequently than before.