








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
In summary
Leverage Ratio
Leverage ratios help you understand how a company uses debt to fund its business. They compare debt with another financial measure, such as equity, assets, or earnings. A higher ratio may indicate greater dependence on borrowed money, but the meaning depends on the specific ratio and the company’s industry.
Here are the key points to remember:
- There is no single formula for every leverage ratio. Debt-to-equity, debt-to-assets, debt-to-capital, and debt-to-EBITDA are different measures.
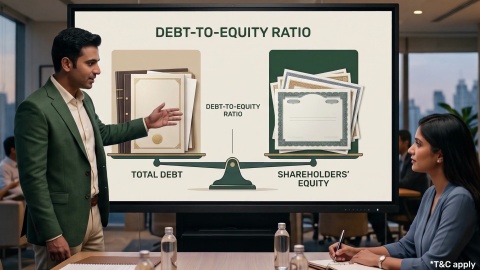
- Debt-to-equity compares total debt with shareholders’ equity.
- Debt-to-assets shows how much of a company’s assets are financed through debt.
- Debt-to-EBITDA compares debt with earnings before interest, taxes, depreciation, and amortisation.
- A leverage ratio should be compared with similar companies and the company’s own past figures.
A high ratio does not automatically mean that a company is financially weak. The industry, cash flows, interest costs, and business model also matter.
For example, a debt-to-equity ratio of 0.75x means the company has Rs. 0.75 of debt for every Rs. 1 of shareholders’ equity. The ratio alone does not tell you whether the level of debt is suitable for that company.
What is a leverage ratio?
A leverage ratio is a financial measure that helps you understand how much debt a company uses in relation to another financial measure.
A company can fund its business using its own money, borrowed money, or a combination of both. Borrowed money is called debt, while money belonging to shareholders is called equity.
Leverage ratios help you see how much a company depends on debt and how that debt compares with its financial position or earnings.
There is no single formula called the “leverage ratio”. The formula depends on the type of leverage ratio you are using.
For example:
- Debt-to-equity compares debt with equity.
- Debt-to-assets compares debt with total assets.
- Debt-to-capital compares debt with total capital.
Debt-to-EBITDA compares debt with EBITDA.
The Securities and Exchange Board of India (SEBI) also uses the debt-to-equity ratio as a measure of a company’s financial leverage. The ratio is calculated as total debt divided by shareholders’ equity.
Source:
The Securities and Exchange Board of India (SEBI).
Why are leverage ratios important?
Leverage ratios help you understand how a company funds its operations and how much it relies on borrowed money.
Debt can help a company fund new projects, purchase assets, or expand its operations. However, debt also creates financial obligations. The company may need to pay interest and repay the borrowed amount.
A company with a higher level of debt may face greater pressure if its earnings or cash flows fall. This is why investors, lenders, and analysts often study leverage ratios alongside other financial measures.
You should not use a leverage ratio on its own. It is more useful when you compare it with:
- The company’s past ratios
- Similar companies in the same industry
- The company’s earnings and cash flows
Its interest costs and repayment obligations
You can also read about financial risk to understand how financial decisions can affect a company’s risk level.
How to calculate a leverage ratio
The calculation depends on the type of leverage ratio you are using. Most leverage ratios compare two financial figures.
For example, the debt-to-equity ratio uses this formula:
Debt-to-equity ratio = Total debt ÷ Total equity
The information required for these calculations generally comes from a company’s financial statements. Under the Companies Act, 2013, financial statements include the balance sheet, profit and loss account, cash flow statement, statement of changes in equity where applicable, and related notes.
What do debt, equity, and assets mean?
Before calculating a leverage ratio, it helps to understand three basic terms.
Debt: Money that a company has borrowed and needs to repay. It can include loans, borrowings, bonds, or other forms of debt.
Equity: The value belonging to the company’s shareholders after accounting for its liabilities.
Assets: Resources owned or controlled by a company. These can include cash, property, equipment, inventory, and other items that have economic value.
A simple leverage ratio example
Suppose a company has:
- Total assets: Rs. 70 crore
- Total debt: Rs. 30 crore
- Total equity: Rs. 40 crore
The debt-to-equity ratio would be:
Debt-to-equity ratio = Rs. 30 crore ÷ Rs. 40 crore = 0.75x
This means the company has Rs. 0.75 of debt for every Rs. 1 of equity.
The debt-to-assets ratio would be:
Debt-to-assets ratio = Rs. 30 crore ÷ Rs. 70 crore = 0.43x
This means debt is equal to 43% of the company’s total assets.
The debt-to-capital ratio would be:
Debt-to-capital ratio = Rs. 30 crore ÷ (Rs. 30 crore + Rs. 40 crore) = 0.43x
This means debt makes up 43% of the company’s debt and equity capital in this example.
These figures are illustrative. They do not represent the financial position of a particular company.
What are the types of leverage ratios
Different leverage ratios compare debt with different financial measures. Each one gives you a different view of the company’s financial position.
Debt-to-equity ratio
The debt-to-equity ratio compares a company’s total debt with its shareholders’ equity.
Formula:
Debt-to-equity ratio = Total debt ÷ Total equity
For example, a debt-to-equity ratio of 1.5x means the company has Rs. 1.50 of debt for every Rs. 1 of equity.
A higher ratio generally indicates greater use of debt relative to equity. However, you should consider the industry and the company’s financial position before interpreting the figure.
Debt-to-assets ratio
The debt-to-assets ratio compares a company’s total debt with its total assets.
Formula:
Debt-to-assets ratio = Total debt ÷ Total assets
For example, a ratio of 0.50 means debt is equal to 50% of the company’s total assets.
This ratio helps you understand how much of the company’s asset base is financed through debt.
Debt-to-capital ratio
The debt-to-capital ratio compares total debt with the company’s total capital, which consists of debt and equity.
Formula:
Debt-to-capital ratio = Total debt ÷ (Total debt + Total equity)
For example, if a company has Rs. 30 crore of debt and Rs. 40 crore of equity, its total capital is Rs. 70 crore.
Its debt-to-capital ratio would therefore be:
Rs. 30 crore ÷ Rs. 70 crore = 0.43x
Debt-to-EBITDA ratio
The debt-to-EBITDA ratio compares a company’s debt with its EBITDA.
EBITDA means earnings before interest, taxes, depreciation, and amortisation. It is a measure of earnings before these items are deducted.
Formula:
Debt-to-EBITDA ratio = Total debt ÷ EBITDA
For example, if a company has Rs. 100 crore of debt and EBITDA of Rs. 25 crore:
Debt-to-EBITDA = Rs. 100 crore ÷ Rs. 25 crore = 4x
This means the company’s debt is four times its EBITDA.
EBITDA is useful for comparison, but it is not the same as cash flow. It does not account for all cash expenses, such as capital expenditure.
Asset-to-equity ratio
The asset-to-equity ratio compares a company’s total assets with its shareholders’ equity.
Formula:
Asset-to-equity ratio = Total assets ÷ Total equity
A higher ratio can indicate that a larger asset base is being supported by each unit of equity. It is useful when studied alongside other leverage measures.
How should you interpret a leverage ratio?
A leverage ratio needs context. A high or low figure does not have the same meaning for every company.
Suppose two companies operate in the same industry. Company A has a debt-to-equity ratio of 0.5x, while Company B has a ratio of 1.5x.
You cannot conclude that Company A is automatically financially stronger. Company B may have higher debt because it is funding an expansion project, while Company A may have a different business model.
To interpret the ratios, look at:
- How the ratio has changed over time
- How it compares with similar companies
- Whether the company generates enough cash to meet its obligations
- How much interest it pays on its debt
- Whether its earnings are stable
Whether the company has significant upcoming repayments
You can also read about risk tolerance when considering how financial risk fits into your overall investment analysis.
What is a good leverage ratio?
There is no single leverage ratio that can be considered suitable for every company.
The appropriate level depends on the specific ratio, industry, business model, earnings, cash flows, and borrowing requirements.
For example, a company that needs large amounts of capital to build factories or infrastructure may have a different debt structure from a service company that requires fewer physical assets.
Instead of using a fixed number as a universal benchmark, compare the ratio with companies in the same industry and with the company’s own historical figures.
A low leverage ratio can indicate lower dependence on debt, but it does not automatically mean that the company is financially stronger. Similarly, a higher ratio does not automatically mean that the company is in financial difficulty.
What does a high leverage ratio mean?
A high leverage ratio generally means that a company has a relatively high level of debt compared with the financial measure used in that ratio.
For example, a high debt-to-equity ratio means the company has more debt relative to shareholders’ equity.
This can increase financial pressure because debt may involve interest payments and repayment obligations. If earnings fall, meeting these obligations can become more difficult.
However, the meaning of a high ratio depends on the company and the industry. You should compare the figure with other relevant financial measures before drawing a conclusion.
Advantages and risks of financial leverage
Companies may use debt to fund business activities without raising all the required money through equity.
Some potential advantages include:
- Funding expansion or new projects
- Purchasing assets required for business operations
- Supporting working capital needs
Raising funds without issuing additional shares
However, borrowing also creates obligations. Some key risks include:
- Higher interest expenses
- Regular repayment obligations
- Greater financial pressure when earnings fall
Higher risk of financial distress if the company cannot meet its obligations
Therefore, the effect of debt depends on how the company uses the borrowed money and whether it can generate enough earnings and cash flow to meet its obligations.
What are the limitations of leverage ratios?
Leverage ratios are useful, but they do not provide a complete picture of a company’s financial position.
Keep these limitations in mind:
- They use accounting data: Changes in accounting methods, estimates, or asset values can affect the ratio.
- They provide a point-in-time view: A ratio may not show how the company’s financial position will change in the future.
- Industry differences matter: Debt levels that are common in one industry may be less common in another.
- They do not show everything: A leverage ratio may not fully capture future cash flows, contingent liabilities, or other financial commitments.
One ratio is not enough: You should consider profitability, liquidity, cash flow, and interest obligations as well.
For example, you can study the interest coverage ratios alongside leverage ratios. While leverage ratios show the level of debt compared with another financial measure, interest coverage measures how well a company’s earnings can cover its interest expenses.
Leverage ratio vs coverage ratio: What is the difference?
Leverage ratios and Coverage Ratios both help you assess a company’s debt position, but they answer different questions.
A leverage ratio focuses on the amount of debt compared with measures such as equity or assets.
A coverage ratio focuses on the company’s ability to meet a financial obligation, such as interest payments.
For example:
Debt-to-equity ratio:
Total debt ÷ Total equity
Interest coverage ratio:
Earnings used for the calculation ÷ Interest expense
A leverage ratio therefore tells you more about the company’s debt structure, while a coverage ratio helps you understand its ability to meet specific financial obligations.
A leverage ratio itself does not automatically impose a debt limit. However, a lender may include a maximum leverage ratio in a loan covenant. If the borrower breaches that condition, the loan agreement may specify certain consequences.
What is the difference between financial leverage and operating leverage?
Financial leverage relates to the use of borrowed money. Operating leverage relates to the use of fixed operating costs.
For example, a company that borrows Rs. 50 crore to fund a new factory is using financial leverage.
A company with high fixed costs, such as rent, salaries, or machinery costs, may have high operating leverage. In that case, a change in sales can have a larger effect on operating profit.
The two concepts are different, although both can affect a company’s financial performance.
How can you use leverage ratios when analysing a company?
Suppose you are considering whether to invest in a listed company.
Start by checking its debt-to-equity ratio. Then compare the figure with the company’s previous years and with similar companies.
Next, check whether the company generates enough earnings and cash flow to manage its debt. You can also examine its interest expenses and repayment obligations.
This approach gives you more context than looking at a single leverage ratio.
Remember that leverage ratios are one part of financial analysis. You can combine them with profitability, liquidity, cash flow, and other measures before making an investment decision.
Explore Investment Tools
Articles and Insights

Frequently Asked Questions
Understanding leverage ratios
Interpreting leverage ratios
Leverage in investing and trading
What is the formula for leverage ratio?
There is no single formula for all leverage ratios. The formula depends on the specific measure. For example, debt-to-equity is calculated as total debt divided by total equity, while debt-to-EBITDA is calculated as total debt divided by EBITDA.
What are some examples of leverage ratios?
Common examples include the debt-to-equity ratio, debt-to-assets ratio, debt-to-capital ratio, debt-to-EBITDA ratio, and asset-to-equity ratio. Each ratio compares debt or assets with a different financial measure, so the interpretation also differs.
Can a leverage ratio be zero?
A leverage ratio can be zero for a ratio that uses debt as its numerator if the company has no debt. For example, a debt-to-equity ratio would be zero when total debt is zero, assuming the denominator is positive.
What are the four common leverage ratios?
Four commonly discussed leverage measures are the debt-to-equity ratio, debt-to-assets ratio, debt-to-EBITDA ratio, and debt-to-capital ratio. Interest coverage is also widely used when analysing a company’s ability to meet interest obligations.
The Bajaj Broking website also provides educational resources on financial ratios and investment concepts, which can help you understand these measures in context.
What does a 1.5 leverage ratio mean?
The meaning depends on the type of leverage ratio. If you mean a debt-to-equity ratio of 1.5x, the company has Rs. 1.50 of debt for every Rs. 1 of equity. A number by itself is not enough to interpret a leverage ratio.
What does a leverage ratio of 2.0 mean?
You need to know which leverage ratio is being used. If it refers to a debt-to-equity ratio of 2.0x, the company has Rs. 2 of debt for every Rs. 1 of equity. The figure should then be compared with industry and historical data.
How can a company reduce its leverage ratio?
A company may reduce its leverage by repaying debt, reducing new borrowing, increasing equity, or improving its earnings, depending on the specific ratio being considered. The appropriate approach depends on the company’s financial position and business requirements.
What is 10x leverage?
In trading, 10x leverage generally means that borrowed funds increase the size of a position to 10 times the investor’s own capital or margin. This is different from company leverage ratios such as debt-to-equity and should not be confused with them.
What is 80% leverage?
In an investment context, 80% leverage generally means that 80% of the investment value is funded through borrowing and 20% through the investor’s own capital. This is different from a company’s debt-to-equity or debt-to-assets ratio.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.