








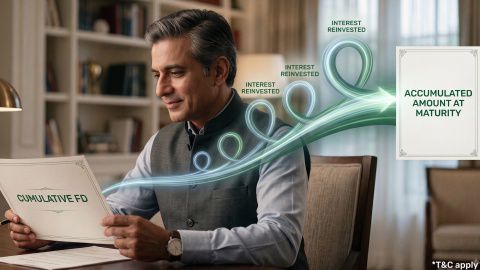
Compounding in Fixed Deposits How its Work
-
In Summary
Compounding can help a fixed deposit grow because accumulated interest contributes to future interest calculations. It is most relevant to cumulative FDs, where interest is retained and paid with the principal at maturity.
- Simple interest: Interest is calculated only on the original principal.
- Compound interest: Interest is calculated on the principal and eligible accumulated interest.
- Maturity amount: Depends on the deposit amount, interest rate, tenure and compounding method.
- Cumulative FD: Interest accumulates under the product’s terms and is paid at maturity.
- Non-cumulative FD: Interest is paid at selected intervals, so it is not retained in the deposit in the same way.
- Actual returns: Depend on the provider’s calculation rules, applicable rate, payout option and any relevant deductions.
Before booking an FD, check whether interest is cumulative or paid periodically. A higher advertised rate does not automatically mean a higher after-tax return, and compounding frequency should be compared only when other assumptions are equivalent.
Most banks and NBFCs calculate FD interest using different compounding frequencies—monthly, quarterly, half-yearly, or annually. The more frequently interest is compounded, the higher the maturity value. This makes compounding an essential concept for anyone planning long-term savings through FDs.
With Bajaj Finance Fixed Deposits, investors benefit from competitive interest rates, flexible tenures, and compounding options that help maximise long-term returns without market risk. Check latest rates.
What is compounding in a fixed deposit?
-
Compounding is the process of calculating interest on the original principal plus interest accumulated in earlier periods, where the scheme’s terms allow that interest to be reinvested.
For example, suppose you deposit Rs.1,00,000 at an illustrative annual rate of 7%, with annual compounding. At the end of the first year, the deposit earns Rs.7,000 in interest, taking the balance to Rs.1,07,000. In the second year, interest is calculated on Rs.1,07,000 rather than only on the original Rs.1,00,000.
This means the amount on which interest is calculated can grow over time. The effect is more noticeable over longer periods, provided the interest remains invested.
A cumulative FD generally follows this principle, subject to the provider’s terms. A non-cumulative FD, by contrast, pays interest periodically instead of accumulating it in the deposit until maturity.
How does compounding work in an FD?
-
The process can be understood in four steps:
- Deposit a lump sum: You invest an amount for a chosen tenure.
- Interest accrues: The deposit earns interest at the rate and according to the method specified in the terms.
- Interest accumulates: In a cumulative FD, eligible interest is retained and contributes to future calculations under the product’s compounding rules.
- Maturity proceeds are paid: At the end of the tenure, you receive the principal and accumulated interest, subject to the applicable terms and deductions.
For a non-cumulative FD, interest is instead paid at the selected intervals, such as monthly, quarterly, half-yearly or annually. Since the interest is paid out rather than retained, the maturity proceeds generally consist of the principal, while the interest has been received separately.
Important: Compounding frequency is product-specific. Bajaj Finance’s published terms state that its cumulative FDs compound annually. Other institutions and products may use different calculation methods, so check the relevant terms rather than assuming that all FDs compound monthly or quarterly.
What is the compound interest formula for an FD?
The standard compound interest formula is:
A = P × (1 + r/n)^(n × t)
Where:
- (A) = maturity amount
- (P) = original principal
- (r) = annual interest rate expressed as a decimal
- (n) = number of compounding periods per year
- (t) = investment tenure in years
The compound interest earned is:
Compound interest = A - P
This is a standard mathematical formula. The calculation used by a financial institution may also account for its specific day-count convention, compounding rules, rounding and payment dates. Use the provider’s maturity calculator for a product-specific estimate.
How do you calculate compound interest on an FD?
Consider an illustrative deposit of Rs.1,00,000 at 7% per annum for five years, compounded annually.
| Particular | Value |
|---|---|
| Principal | Rs.1,00,000 |
| Annual interest rate | 7% |
| Tenure | 5 years |
| Compounding frequency | Annual |
| Maturity amount | Approximately Rs.1,40,255 |
| Total interest earned | Approximately Rs.40,255 |
Using the formula:
A=1,00,000(1+0.07)^5
A\approx Rs.1,40,255
Therefore, the deposit grows to approximately Rs.1.40 lakh, including around Rs.40,255 in interest.
These figures are illustrative, not a quoted FD offer. Actual maturity proceeds depend on the institution’s rate, compounding and day-count rules, selected tenure and other applicable terms.
How does compound interest compare with simple interest?
Using the same principal, annual rate and five-year period:
| Particular | Simple interest | Compound interest |
|---|---|---|
| Principal | Rs.1,00,000 | Rs.1,00,000 |
| Annual rate | 7% | 7% |
| Tenure | 5 years | 5 years |
| Interest earned | Rs.35,000 | Approximately Rs.40,255 |
| Maturity amount | Rs.1,35,000 | Approximately Rs.1,40,255 |
Under these assumptions, compound interest produces approximately Rs.5,255 more than simple interest over five years.
The comparison assumes annual compounding for the compound-interest example and simple interest for the other. It is a mathematical illustration, not a comparison of two specific FD products.
What factors affect compound interest on an FD?
Several factors influence the amount you may receive at maturity.
1. Principal amount
The principal is the amount deposited at the beginning. Other things being equal, a larger principal generates more interest in rupee terms.
For example, at the same rate, tenure and compounding method, a deposit of Rs.2,00,000 earns approximately twice the interest of a deposit of Rs.1,00,000.
2. Interest rate
The applicable annual rate affects how much interest accumulates. A higher rate generally produces a higher maturity amount when the principal, tenure and calculation method are unchanged.
FD rates can vary by institution, tenure, deposit amount, customer category and payout option. Check the current rate table and effective date before booking.
3. Investment tenure
A longer tenure provides more time for interest to accumulate and, where applicable, compound. However, choosing a longer term should also take into account when you may need the money and the product’s premature-closure rules.
4. Compounding method
The frequency and method of compounding influence the mathematical result. When the annual rate and all other assumptions are the same, more frequent compounding generally produces a slightly higher result than less frequent compounding.
However, products may quote different rates for different payout options. The actual maturity value should therefore be compared using each product’s stated rate and calculation method, not frequency alone.
5. Interest payout option
A cumulative FD retains interest under the scheme’s terms and pays the proceeds at maturity. A non-cumulative FD pays interest periodically, which may be more suitable for someone who needs regular income.
If periodic interest payments are spent rather than reinvested elsewhere, they do not benefit from further compounding within that FD.
6. Taxes and other applicable deductions
FD interest is generally taxable under the applicable income-tax rules. Tax deducted at source (TDS), where applicable, affects the amount credited to you, although TDS is not necessarily the same as your final tax liability.
Compare the expected after-tax outcome as well as the gross maturity amount.
What are the benefits of compounding in a fixed deposit?
Compounding may be useful when you want to retain interest within a deposit rather than receive periodic payouts.
- Interest accumulates over time: The deposit can grow as interest is added under the scheme’s terms.
- Supports planned savings: A cumulative FD can help build a lump sum for a future expense.
- Maturity value is easier to estimate: The quoted rate and terms allow you to estimate proceeds, although actual calculations may vary with the provider’s method.
- No need to reinvest each interest payment manually: Under a cumulative structure, interest accumulates automatically as specified by the product.
- Can suit medium-term goals: A cumulative FD may be appropriate where the maturity date aligns with the planned use of the money.
Compounding does not remove the need to assess the institution’s credit risk, taxation, liquidity and early-withdrawal rules. It also does not mean that every FD offers the same return.
What is the difference between cumulative and non-cumulative FDs?
The key difference is how and when interest is received.
| Feature | Cumulative FD | Non-cumulative FD |
|---|---|---|
| Interest handling | Interest accumulates under the scheme’s terms | Interest is paid at selected intervals |
| Typical payout | Principal and accumulated interest at maturity | Interest periodically; principal at maturity |
| Compounding effect within the deposit | Interest may be retained and compounded as specified | Interest paid out is not retained in the deposit |
| Common use | Building a lump sum | Receiving regular interest income |
| Main consideration | Access to interest is generally at maturity | Payout amounts and rates depend on the product’s terms |
Neither option is universally preferable. A cumulative FD may suit someone who does not need regular interest income, while a non-cumulative FD may suit someone who wants periodic payments for expenses.
Check out different FD Rates
How can you estimate the maturity value of an FD?
An FD calculator can help estimate the maturity amount using the deposit amount, tenure, interest rate and payout option.
To estimate your returns:
- Open the provider’s FD calculator.
- Enter the amount you plan to deposit.
- Select the available tenure.
- Choose the relevant interest payout option.
- Review the estimated interest and maturity proceeds.
- Check the applicable rate and terms before confirming the deposit.
You can use the Bajaj Finance FD calculator for an estimate based on its available product options. The calculator’s output is indicative; the final amount depends on the booked FD’s terms and applicable calculations.
How can you make an informed choice when considering FD compounding?
A few practical checks can help you decide whether a cumulative FD fits your needs.
- Match the tenure to your goal: Choose a period that aligns with when you expect to need the money.
- Compare the rate for the same term: Review rates for the same tenure, customer category and payout option.
- Understand the compounding rules: Confirm how and when interest is calculated and accumulated.
- Check early-closure conditions: A premature withdrawal may reduce the interest payable or be restricted.
- Account for tax: Estimate the likely after-tax outcome rather than relying only on the gross return.
- Consider liquidity: Keep funds for emergencies accessible rather than committing all available savings to a deposit with restrictions.
- Verify the provider: Review the institution’s terms, disclosures and applicable deposit-protection arrangements.
For example, if you do not need the interest until a planned expense in three years, a cumulative FD may be worth comparing with a non-cumulative deposit. If you need interest to meet recurring expenses, a periodic payout option may be more suitable.
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
Compounding allows interest retained in an FD to contribute to future interest calculations. Over time, this can increase the maturity amount compared with simple interest under otherwise equivalent assumptions. The benefit depends on the deposit amount, interest rate, tenure and the scheme’s calculation method.
Before choosing an FD, compare cumulative and non-cumulative options, check the applicable interest rate and understand the tax and premature-closure rules. Use a calculator for an estimate, then confirm the actual terms with the financial institution.
Locate to your nearest FD branch

Related Articles

Frequently Asked Questions
Overview
Can I get compound interest on FD?
Yes, select a cumulative Fixed Deposit where interest remains invested until maturity. Future interest is calculated on the principal and accumulated interest.
Why should I choose Bajaj Finance FD for long-term savings?
Bajaj Finance Fixed Deposit offers assured returns, 12-to-60-month tenures, and cumulative options. It carries CRISIL AAA/STABLE and [ICRA]AAA(Stable) ratings.
Does an FD give compounding interest?
A cumulative Fixed Deposit provides compounding because interest remains within the deposit. A non-cumulative deposit pays interest periodically, preventing internal compounding.
Is an FD compounded annually or monthly?
The frequency depends on the issuer’s terms. Bajaj Finance cumulative Fixed Deposits compound annually, while non-cumulative deposits offer different periodic payout options.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.