







Clear your overdue EMI
Clear your overdue EMI today – stop penalties & fix your credit
*Overdue charges include penalty interest and bounce fees as applicable. T&C apply.
In Summary
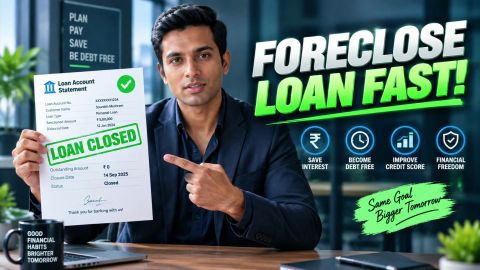
Follow the correct step-by-step process to foreclose or cancel loans
Closing your home loan involves confirming the final amount payable, completing repayment and obtaining written closure confirmation. Check the required documents and property-related formalities to keep your records accurate.
- Review your outstanding balance, unpaid instalments and applicable charges, and request the final repayment amount from your lender.
- Pay the confirmed amount through an authorised method, retain the transaction receipt and complete any required closure formalities.
- Collect the applicable NOC or NDC, loan closure confirmation, final statement and original property documents held by the lender.
- Check whether any property charge-release process or property record update remains necessary after the loan closes.
- If your account still shows as active, contact your lender with the payment reference and supporting records to resolve the discrepancy.
Keep your closure documents securely, verify your loan account status and follow up with your lender on any outstanding formalities or missing records.
How do you close a home loan?
You can begin the home loan closure process through your lender’s official online services, customer care, or designated branch. The available payment options and required formalities depend on your loan account.
Follow these steps to complete the process:
- Review your loan account. Check the outstanding balance and any unpaid instalments through the official customer portal or app, where available.
- Request the final repayment amount. Ask your lender to confirm the total amount payable for your intended closure date.
- Confirm the payment method. Check whether you can make the final payment online or need assistance through customer care or a branch.
- Pay the confirmed amount. Use an authorised payment method and retain the transaction receipt.
- Complete the closure formalities. Submit any required request or documents and follow the lender’s instructions.
- Obtain closure confirmation. Check the loan account status and collect the applicable closure documents.
If you cannot find the relevant option online, contact customer care or visit the designated branch to understand the next steps. Keep your loan account details and payment records available when seeking assistance.
What should you check before paying the final amount?
You should confirm the total amount payable for your intended closure date before making the final home loan payment. The outstanding principal in a regular statement may differ from the amount required to close the account.
Check the following details with your lender:
- The final repayment amount applicable to your payment date.
- Any unpaid instalments or other outstanding dues.
- Any applicable charges included in the final amount.
- The authorised payment methods available for your account.
- Any documents or requests needed to complete closure.
For example, if your statement shows an outstanding principal of Rs. 5,00,000, do not assume that this is the final amount payable. Request the closure amount from your lender and ask for an explanation of any difference before paying.
Keep a copy of the confirmed amount and payment receipt. These records can help you resolve discrepancies if the payment or closure status needs further review.
What happens after you make the final home loan payment?
After you make the final payment, your lender must complete the applicable account closure formalities before you treat the loan as closed. Payment and formal closure are related but separate steps. Retain your transaction receipt and check whether the payment has been credited to your loan account. Follow any instructions from the lender about submitting a closure request, providing documents or collecting the closure records. Ask for written confirmation once the account has been closed. If the lender requires additional steps, clarify what remains outstanding and how you can complete them. Do not rely only on a successful payment message to confirm closure. Check the account status and obtain the applicable documents. If the lender holds original property documents, confirm the process and arrangements for their return.
Which documents should you collect after home loan closure?
You should collect the applicable loan closure records and any original property documents that your lender holds. The documents you receive depend on your loan account and the formalities applicable to the property.
Check whether you need the following records:
- No Objection Certificate (NOC) or No Dues Certificate (NDC): The applicable certificate confirming that the relevant loan dues have been cleared.
- Loan closure confirmation: Written confirmation that the loan account has been closed.
- Final loan statement: A record of the loan account’s final repayment position.
- Original property documents: Documents held by the lender that are due to be returned.
- Document handover acknowledgement: A record of the original documents returned to you.
- Charge-release records: Relevant confirmation or supporting documents for any applicable property charge-release process.
Check the borrower details and loan account information on the documents. Store the records securely so you can refer to them when needed. Ask your lender whether any further property-related formalities remain after the account closes.
What should you check in your property records after closure?
After closing your home loan, check whether any property-related formalities remain. Use the following table to review the records and next steps.
| What to check | Action to take |
| Registered property charge | Ask your lender whether a charge was registered against the property and whether it needs to be released. |
| Property record updates | Confirm whether any updates to property records are required and follow the applicable instructions. |
| Original property documents | Compare the documents returned by the lender with the handover details. |
| Missing documents or discrepancies | Contact your lender if any expected document is missing or the records do not match. |
| Supporting records | Retain charge-release documents, handover acknowledgements and other relevant records. |
Do not assume loan closure automatically completes every property-related formality. Confirm which steps apply to your property and keep the relevant acknowledgements with your closure documents.
What if your home loan still shows as active after repayment?
If your home loan still appears active after the final payment, check whether the payment has been credited and whether the lender has completed the closure formalities. A payment receipt alone does not confirm that the account has been formally closed.
Take these steps to resolve the issue:
- Review your payment receipt and the latest loan statement.
- Contact customer care through an official channel or raise a service request using an available online service.
- Share your transaction reference and supporting records through an authorised channel if requested.
- Ask whether any dues, documents or closure steps remain outstanding.
- Retain the service request number and written responses for follow-up.
If the account status does not match your payment records, ask the lender to investigate the discrepancy. Once the lender confirms closure, check that you have received the applicable closure documents and any property records due to you.
Loan support made easy - Read on
Not your nearest branch?

Frequently Asked Questions
Home Loan Closure Basics
Overdue & Closure Process
What should you do if you discover an outstanding amount after your home loan closure request?
Review your latest loan statement and ask your lender to explain the outstanding amount before making another payment. Check whether it relates to an unpaid instalment, an applicable charge or another account adjustment. Request a breakdown of the amount and retain the response and payment records until the discrepancy has been resolved.
How can you confirm that your final home loan payment has been allocated correctly?
Compare your payment receipt with your loan account statement and verify the amount and transaction date. If the account does not reflect the payment correctly, contact your lender through an authorised service channel and provide the transaction reference. Ask for confirmation once the payment has been reconciled and the remaining closure formalities have been completed.
What should you do if you are closing a joint home loan?
Contact your lender to confirm the closure requirements applicable to all borrowers on the loan account. Check whether any joint borrower verification, signatures or documents are required. Before completing the process, ensure that each borrower understands the outstanding amount, payment arrangements and closure formalities, and retain the written confirmation issued after closure.
What should you do if an original property document is missing when the lender returns your papers?
Compare the documents received with the handover acknowledgement or the list provided by your lender. Record the details of any missing document and raise a request through an authorised service channel. Keep the acknowledgement and written responses, and ask the lender to explain the next steps for tracing or obtaining the missing document.
Why should you keep your home loan closure documents after repayment?
Closure documents provide evidence of the loan's repayment and formal closure, while property-related records may help establish that the applicable documentation has been returned or updated. Keep the closure confirmation, final statement, relevant certificates and document handover records securely. You may need them later to answer queries about the loan or property records.
What should you do if your property records still show a lender-related charge after loan closure?
First, confirm with your lender whether a charge was registered against the property and whether the release process has been completed. Ask which supporting documents or further formalities are required. Property record updates may involve a separate process, so retain the lender's confirmation and follow the applicable instructions for updating the relevant records.
More Articles
Disclaimer
While care is taken to update the information, products, and services included in or available on our website and related platforms/websites, there may be inadvertent inaccuracies or typographical errors or delays in updating the information. The material contained in this site, and on associated web pages, is for reference and general information purpose and the details mentioned in the respective product/service document shall prevail in case of any inconsistency. Subscribers and users should seek professional advice before acting on the basis of the information contained herein. Please take an informed decision with respect to any product or service after going through the relevant product/service document and applicable terms and conditions. In case any inconsistencies observed, please click on reach us.
*Terms and conditions apply.