550 CIBIL Score: Which Overdue Account to Clear First

550 CIBIL Score: Which Overdue Account to Clear First

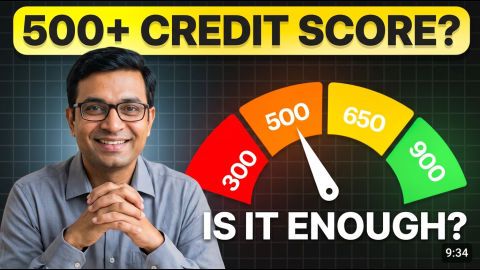
A 550 CIBIL score can reflect overdue balances with more than one lender at once. Clearing them in the right order limits the damage while you work towards the 650 Bajaj Finance lists for its Personal Loan.

Rs. 40,000 - Rs. 75 lakh

You may be eligible for a pre-approved offer

Enter mobile and OTP | Check offer | No branch visit needed


In summary

When 2 or more accounts are overdue, rank them by how late each one is, measured as days past due (DPD). The latest accounts carry the most risk, so they come first, while you keep current accounts clean. A Bajaj Finance Personal Loan needs 650 or higher.


  • Your report shows DPD for every account.
  • Accounts beyond 90 DPD come first.
  • Current accounts must stay current.
  • Bharat moved from 550 to 657 over 16 months.

Clearing the worst account first stops it from turning into a write-off on a 550 CIBIL score record. Work down the list one account at a time.

What does days past due mean?

Days past due (DPD) counts how many days a payment is late, recorded each month for each account. A 550 CIBIL score with DPD on 2 or more accounts shows lenders that the strain is spread across your borrowing.

Show More Show Less

How should you rank overdue accounts?

Rank them by DPD, starting with the account that is furthest behind. Use the table to set the sequence when a 550 CIBIL score spans 2 or more lenders.


Account statusPriorityReason
Days past due (DPD) above 90FirstRisks being written off
DPD of 31 to 90SecondCan still be brought back to current
DPD of 1 to 30Third, but within the monthCheapest to fix now
Current accountsKeep paying on timeProtects what is still clean

Last updated: 21st October, 2026


Call each lender, explain your income, and ask for a written plan. Lenders tend to agree terms sooner when you reach out first, before a 550 CIBIL score slips further.

Show More Show Less

How does reporting affect your progress?

A 15-day reporting cycle replaced the monthly one on 1st January, 2025. Each account you bring to current can show on your report within the same month.


Worked example: Bharat in Solapur

Bharat is 35 and works as a salaried textile mill supervisor in Solapur, earning Rs. 36,000 a month. After a medical emergency, he fell behind on a consumer durable loan, a card and a two-wheeler loan, leaving a 550 CIBIL score. He cleared the card first, at 120 DPD, then the other 2, then kept every account current for 16 months; his score climbed to 657. He then borrowed Rs. 70,000 to replace a work laptop, at an illustrative 20% per annum, and compared the equated monthly instalment (EMI) over 12 and 18 months.


EMI = P × R × (1 + R)^N ÷ [(1 + R)^N − 1]. Here P = Rs. 70,000, R = 20 ÷ 1,200 and N = months.


TenureMonthly EMI (Rs.)Total interest (Rs.)EMI as share of salary (%)
12 months (1 year)6,4847,81318.0
18 months (1.5 years)4,53311,60212.6

Last updated: 21st October, 2026


Adding 6 months drops the EMI by Rs. 1,951 while interest grows by Rs. 3,789. A processing fee of up to Rs. 2,891 would apply. Bharat chose 18 months, as an EMI of 18% of his pay felt risky after his recent strain.

Show More Show Less

What will Bajaj Finance require when you are ready?

A 550 CIBIL score is a long way from the CIBIL condition below. Once each account is current and the score has recovered, a Bajaj Finance Personal Loan needs:


CriterionRequirement
NationalityIndian
Age21 years to 80 years.
Employed withPublic, private, or multinational companies (MNCs).
CIBIL Score650 or higher.
Customer profileSelf-employed or Salaried

*You should be 80 years or younger, at the end of the loan tenure.

Last updated: 21st October, 2026


Meeting these criteria does not guarantee approval, which depends on eligibility, verification and credit assessment. No collateral or guarantor is required.


You may need the following documents, subject to your profile and application:


Document categoryAccepted options
KYC proofAadhaar/ passport/ voter’s ID/ driving license/ Letter of National Population Register/ NREGA job card
Identity proofPAN card, Real-time image / photograph
Employment proofEmployee ID card, Letter of Allotment of Accommodation Issued by Employer
Income proofSalary slips — last 3 months, Bank account statements — last 3 months
OthersPension order, Utility bill, Phone bill, Piped gas bill, Property / Municipal tax receipt

Not every applicant needs every document. Confirm the final list of required personal loan documents during your application.

Show More Show Less

How do you fund repayments without new debt?

Fund repayments from income and assets you already hold, since new credit adds another account to manage. The table lists sources for someone with a 550 CIBIL score.


SourceHow it helpsLimit
Sell an unused assetFrees cash for the oldest arrearsOne-off amount
Trim fixed costs, such as subscriptionsAdds a monthly sum to repaymentsSmall sums each month
Overtime or extra shiftsRaises income for a periodDepends on your employer

Last updated: 21st October, 2026


Put every extra rupee towards the account at the top of your list until it is current, then move to the next one. This is the steadiest way out of a 550 CIBIL score.

Show More

Key offerings: 3 loan types

Personal loan interest rate and applicable charges

Type of fee

Applicable charges

Rate of interest per annum

10% to 30.5% p.a.

Processing fees

Up to 4.13% of the loan amount (inclusive of applicable taxes).

Flexi Facility Charge

Term Loan – Not applicable

Flexi Loans –Up To Rs 1,999 To Up To Rs 18,999/- (Inclusive Of Applicable Taxes)

Will be deducted upfront from loan amount.

Bounce charges

Rs. 700 to Rs. 1,200/- per bounce

“Bounce charges” shall mean charges for (i) dishonor of any payment instrument; or (ii) non-payment of instalment (s) on their respective due dates due to dishonor of payment mandate or non-registration of the payment mandate or any other reason.

Part-prepayment charges

Full Pre-payment:

  • Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount as on the date of full pre-payment

  • Flexi Term (Dropline) Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

  • Flexi Hybrid Term Loan: Up to 4.72% (Inclusive of applicable taxes) on the outstanding loan amount, as on the date of full prepayment.

Part Pre-payment

  • Up to 4.72% (Inclusive of applicable taxes) of the principal amount of Loan prepaid on the date of such part Pre-Payment.

  • Not Applicable for Flexi Term (Dropline) Loan and Flexi Hybrid Term Loan.

Penal charge

Delay in payment of instalment(s) shall attract Penal Charge at the rate of up to 36% per annum per instalment from the respective due date until the date of receipt of the full instalment(s) amount.

Stamp duty (as per respective state)

Payable as per state laws and deducted upfront from loan amount.

Annual maintenance charges

Term Loan: Not applicable

Flexi Term (Dropline) Loan:

Up to 0.295% (Inclusive of applicable taxes) of the Dropline limit (as per the repayment schedule) on the date of levy of such charges.


Flexi Hybrid Term Loan:

Up to 0.472% (Inclusive Of Applicable Taxes) Of The Dropline Limit During Initial Tenure. Up to 0.295% (Inclusive Of Applicable Taxes) Of Dropline Limit During Subsequent Tenure

Credit guarantee scheme feeUp to 1.18% p.a. (pro-rated daily till 31st March) (inclusive of all applicable taxes) of the loan amount
Credit guarantee scheme renewal feeUp to 1.18% p.a. (inclusive of all applicable taxes) on the outstanding loan amount as on April 01 of the subsequent Financial Year.
*Renewal Fee to be collected only for 3 subsequent financial years.
 
**If the Remaining Tenure is less than 12 months, the CG Fee in subsequent years shall be charged prorated.

Frequently asked questions

Overdue accounts

Moving forward

Why clear the account furthest past due first?

An account far past due is closest to being written off, which would stay on your report as a serious mark. Bringing it back to current stops that. Accounts with lower DPD are cheaper to fix and can follow. This order limits the worst damage behind a 550 CIBIL score.

Both count against your payment history, and the DPD matters more than the product type. A card may grow faster due to interest on the unpaid balance, so factor in cost once the DPD order is set. Bharat cleared his card first, as it was the furthest behind of his 3 accounts.

The Bajaj Finance Personal Loan criterion is 650 or more, which puts it out of reach for a 550 CIBIL score. Some lenders offer secured credit, such as a loan against a deposit, on their own terms. Check that any lender is regulated by the Reserve Bank of India (RBI) and never pay an advance fee.

Keep a simple sheet listing each account, its DPD, the agreed plan and each payment date. Check your CIBIL report every month to confirm the DPD falls to zero on each account. Bharat updated his sheet after every payment until all 3 accounts were current and his 550 CIBIL score began to recover.

Show More Show Less

Disclaimer

Bajaj Finance Limited has the sole and absolute discretion, without assigning any reason to accept or reject any application. Terms and conditions apply*.
For customer support, call Personal Loan IVR: 7757 000 000