








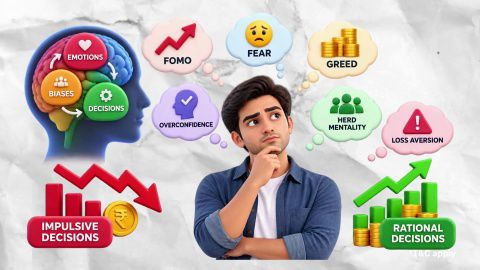
Key Financial Terms Explained Financial Year, Behavioral Finance & More
-
In Summary
Behavioural finance examines how human behaviour affects decisions about saving, spending and investing. It recognises that investors do not always make choices based solely on available information or financial calculations.
- Meaning: It combines psychology and finance to explain how emotions and mental shortcuts influence financial decisions.
- Common biases: Herd mentality, loss aversion, overconfidence, anchoring and confirmation bias can affect investment choices.
- Practical impact: These biases may lead to impulsive trading, excessive risk-taking or reluctance to reconsider an investment.
- Key theories: Prospect theory and behavioural portfolio theory help explain how people perceive risk, gains and losses.
- Managing biases: A written investment plan, clear financial goals, diversification and periodic portfolio reviews can help bring more structure to decisions.
Understanding behavioural finance does not eliminate investment risk or guarantee better returns. However, recognising common biases can help people assess financial decisions more deliberately.
If you prefer stable, bias-free returns, consider investing in a Bajaj Finance Fixed Deposit — a secure way to earn guaranteed returns without market risks. Book FD.
What is Behavioural Finance?
-
Financial decisions are not always based on calculations alone. People may respond differently to the same information depending on their experiences, expectations and emotional state.
Understanding behavioural finance can help individuals recognise these influences before making financial decisions.
Its importance can be understood through the following points:
- Improves self-awareness: It helps people identify patterns such as fear of losses, overconfidence or following the crowd.
- Supports more deliberate decisions: Recognising emotional triggers can create an opportunity to pause and review a choice.
- Explains investment behaviour: It helps explain why investors may buy during periods of excitement or sell during market declines.
- Encourages consistency: A written financial plan can help people assess decisions against their goals instead of reacting to every market movement.
- Provides insight into markets: Behavioural finance can help explain some market patterns that traditional models may not fully account for.
Behavioural finance is useful for first-time investors as well as experienced market participants. Experience and financial knowledge do not make a person completely immune to behavioural biases.
What are the core concepts of behavioural finance?
Behavioural finance covers several concepts that explain how people process information and make financial decisions.
1. Herd mentality
Herd mentality occurs when people follow the actions or opinions of a group instead of evaluating a decision independently.
In investing, this may happen when someone buys a stock because it is widely discussed on social media or because many acquaintances have invested in it. The popularity of an investment may be mistaken for evidence of its quality.
Example: An investor buys shares of a company after hearing repeated recommendations from friends, without reviewing the company's financial position, valuation or risks.
How to manage it: Assess an investment against its fundamentals, suitability and risk before acting on popular opinion.
2. Loss aversion
Loss aversion refers to the tendency to experience the discomfort of a loss more strongly than the satisfaction of an equivalent gain.
This can influence investment decisions in different ways. An investor may hold a declining investment for too long because selling would make the loss feel real. Another may avoid an investment that fits their goals because the possibility of losing money feels especially uncomfortable.
Example: An investor continues holding a share only because they want its price to return to the original purchase price, even though the company's prospects may have changed.
How to manage it: Reassess the investment using current information, its role in the portfolio and the original financial objective rather than the purchase price alone.
3. Overconfidence bias
Overconfidence bias occurs when people overestimate their knowledge, judgement or ability to predict outcomes.
In financial markets, this may lead to excessive trading, concentrated portfolios or insufficient attention to risk.
Example: After correctly predicting a few market movements, an investor assumes they can consistently time the market and begins making larger, less diversified bets.
How to manage it: Recognise the limits of prediction, consider alternative explanations and assess the potential downside as carefully as the expected return.
4. Mental accounting
Mental accounting is the tendency to treat money differently depending on where it came from or what it is intended for, rather than considering the overall financial position.
For instance, someone may carefully save their monthly salary but spend a bonus or gift more freely because it feels like extra money.
Example: A person uses an unexpected cash bonus for discretionary purchases while carrying expensive outstanding debt or lacking an emergency fund.
How to manage it: Consider income, savings, debt and expenses together. Assign money to priorities based on the overall financial plan rather than its source.
5. Confirmation bias
Confirmation bias occurs when people favour information that supports their existing beliefs and give less attention to evidence that challenges them.
Example: An investor who believes a company will perform well reads only positive news about it and dismisses negative earnings information or changes in its business outlook.
How to manage it: Actively look for credible evidence that challenges the original view. Consider both favourable and unfavourable information before making a decision.
What are the common behavioural finance issues?
Behavioural biases can affect not only which investments people choose but also when they buy, sell or change their financial plans.
Common issues include the following.
Emotional investing
Emotional investing occurs when decisions are driven mainly by feelings such as fear, excitement, anxiety or greed rather than a considered assessment.
For example, an investor may sell a diversified portfolio during a market decline because of panic, even though their financial goals and time horizon have not changed.
A structured investment plan and predefined review criteria can help reduce decisions made in the heat of the moment.
Short-term focus
Short-term focus occurs when immediate results receive more attention than longer-term goals.
An investor may repeatedly change their investment choices in response to daily market movements, even when those movements do not materially affect the original investment rationale.
Reviewing investments at planned intervals and relating them to specific goals can help maintain perspective. The appropriate review frequency depends on the investment and the individual's circumstances.
Anchoring bias
Anchoring bias occurs when a person relies too heavily on an initial figure or piece of information when making a decision.
In investing, the anchor may be the original purchase price, a past market high or an analyst's earlier price target.
Example: An investor refuses to sell a share at Rs. 150 because they purchased it for Rs. 200, even though current information suggests that its prospects have weakened.
The original purchase price is relevant for calculating the gain or loss, but it does not by itself establish what the investment is worth today.
Illusion of control
The illusion of control is the belief that a person can influence or predict outcomes that are largely outside their control.
In financial markets, investors may believe that frequent monitoring or repeated trading gives them greater control over market movements.
However, research, analysis and experience cannot remove uncertainty from financial markets. Investors can control aspects such as their allocation, costs and exposure to risk, but they cannot control future market prices.
Regret aversion
Regret aversion refers to the tendency to avoid a decision because of the possibility of regretting it later.
An investor may delay reviewing a poorly performing investment because selling could feel like admitting a mistake. Another may avoid a suitable financial decision because they fear that an alternative might perform better.
Comparing available choices against clear criteria and accepting that no decision can eliminate uncertainty may help reduce the influence of regret aversion.
What are the key theories of behavioural finance?
Behavioural finance theories help explain why people respond differently to gains, losses, information and risk.
1. Prospect theory
Prospect theory, developed by psychologists Daniel Kahneman and Amos Tversky, explains how people evaluate potential gains and losses relative to a reference point.
One important insight is that people may react more strongly to losses than to equivalent gains. Their willingness to take risks can also change depending on whether a choice is framed as a potential gain or a potential loss.
For example, an investor may prefer a relatively certain gain but become willing to take greater risks when trying to recover a loss. This is not universal behaviour, but it is a pattern that prospect theory helps explain.
2. Behavioural portfolio theory
Behavioural portfolio theory examines how psychological preferences and personal goals influence the way people construct portfolios.
Some investors mentally separate money into different categories, such as retirement savings, a child's education fund and money intended for short-term spending. They may assess each category separately rather than considering the combined risks and returns of their entire portfolio.
A goal-based approach can be useful, but the overall portfolio still needs to be assessed for diversification, liquidity, costs and risk.
3. Efficient market hypothesis and behavioural finance
The efficient market hypothesis (EMH) proposes, in broad terms, that market prices reflect available information to varying degrees, depending on the form of market efficiency being considered.
Behavioural finance examines how psychological biases, investor sentiment and limits to arbitrage may contribute to patterns in market prices or trading that are not fully explained by traditional models.
This does not mean that markets are always inefficient or that behavioural finance can reliably predict future price movements. It offers another way to understand how individual and collective behaviour may affect financial markets.
4. Adaptive Markets Hypothesis
The adaptive markets hypothesis proposes that market behaviour can be understood partly through ideas from evolution, learning, competition and adaptation.
In this view, investors and market participants adjust their behaviour as conditions change. A strategy that appears useful in one environment may become less effective in another as competition and market conditions evolve.
The hypothesis brings together elements of traditional finance and behavioural insights. It emphasises that financial behaviour and market outcomes may change over time.
How can behavioural finance improve investment decision-making?
Behavioural finance can help investors recognise when emotions or mental shortcuts may be influencing a decision. The objective is not to eliminate emotions, but to build a process that allows financial choices to be reviewed more consistently.
Practical steps include:
- Set clear financial goals. Identify the purpose of each investment, the time horizon and the level of risk that may be appropriate.
- Write down the reasons for investing. Record the rationale, important assumptions and circumstances that would justify reviewing the decision.
- Diversify where appropriate. Avoid allowing a single investment or asset class to dominate the portfolio without a clear reason.
- Review credible information from different perspectives. Consider evidence that supports and challenges an investment view.
- Avoid impulsive reactions. Before acting on market news or a sharp price movement, check whether the event changes the investment's fundamentals or your financial needs.
- Review the overall portfolio. Consider investments together, including their combined exposure to risk, liquidity needs and costs.
- Learn from past decisions. Review both successful and unsuccessful decisions to understand whether the process was sound, rather than judging it solely by the outcome.
These practices can support more disciplined decisions, but they cannot guarantee profits or prevent losses. Investment choices should reflect an individual's circumstances and tolerance for risk.
What is the difference between traditional finance and behavioural finance?
Traditional finance and behavioural finance offer different but complementary ways of understanding financial decisions.
| Basis | Traditional finance | Behavioural finance |
|---|---|---|
| Main focus | Financial decisions and outcomes, often using rational-choice models | How psychology and human behaviour influence financial decisions |
| View of decision-making | Commonly models decisions as rational responses to information and preferences | Recognises that emotions and cognitive biases can influence decisions |
| Role of emotions | Often simplified or excluded from core models | Considered an important influence on behaviour |
| Investor behaviour | Analysed through expected returns, risk and other financial variables | Also examines biases such as loss aversion, anchoring and herd mentality |
| Market behaviour | Uses models such as the efficient market hypothesis to analyse prices and information | Examines how sentiment, biases and limits to arbitrage may help explain certain market patterns |
Neither approach explains every financial outcome on its own. Traditional financial models remain useful for analysing risk and return, while behavioural finance adds insight into how people actually make decisions.
To conclud...
Behavioural finance explains how emotions, mental shortcuts and psychological biases can influence saving, spending and investment decisions. Concepts such as herd mentality, loss aversion, overconfidence, mental accounting and anchoring help explain why people sometimes make choices that do not align with their long-term objectives.
Recognising these patterns can help individuals pause, examine the available evidence and assess decisions against their financial goals. A structured plan, diversified investments where appropriate and regular reviews can support a more consistent decision-making process. However, behavioural finance is not a method for predicting markets or guaranteeing returns; investment decisions still involve uncertainty and risk.
Check out different FD Rates
Fixed Deposit variants
Get ROI up to
8.15% p.a.
Senior citizen
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Age below 60 years
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Minor
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
HUF
Starting with just Rs. 15,000
Get ROI up to
7.75% p.a.
Sole proprietor
Starting with just Rs. 15,000
Locate to your nearest FD branch

Related Articles


Frequently Asked Questions
Overview
What is the concept of behavioural finance?
Behavioural finance studies how psychology, emotions and cognitive biases influence financial decisions. It helps explain why people may make choices that differ from those predicted by traditional financial models, including decisions affected by fear, overconfidence or social pressure.
What is financial behaviour?
Financial behaviour refers to how individuals manage money through activities such as earning, spending, saving, borrowing and investing. It can be influenced by income, personal experiences, financial knowledge, emotions, social expectations and psychological biases.
How can behavioural finance help with financial planning?
Investors can use behavioural finance by identifying potential biases, checking information from different perspectives, writing down their investment rationale and reviewing decisions against their financial goals. Diversification and planned portfolio reviews may also help reduce the influence of impulsive reactions.
Is behavioural finance the same as behavioural economics?
No. Behavioural economics is the broader field that studies how psychological and social factors influence economic decisions. Behavioural finance applies many of these insights specifically to financial decisions, investing and financial markets.
What is an example of loss aversion in investing?
An investor may continue holding a declining share because selling it would mean accepting a loss. If the decision is based only on avoiding that feeling rather than reviewing the investment's current prospects and risks, loss aversion may be influencing the choice.
Disclaimer
1. Bajaj Finance Limited (“BFL”) is a Non-Banking Finance Company (BAJAJ FINANCE) and Prepaid Payment Instrument Issuer offering financial services viz., loans, deposits, Bajaj Pay Wallet, Bajaj Pay UPI, bill payments and third-party wealth management products. The details mentioned in the respective product/ service document shall prevail in case of any inconsistency with respect to the information referring to BFL products and services on this page.
2. All other information, such as, the images, facts, statistics etc. (“information”) that are in addition to the details mentioned in the BFL’s product/ service document and which are being displayed on this page only depicts the summary of the information sourced from the public domain. The said information is neither owned by BFL nor it is to the exclusive knowledge of BFL. There may be inadvertent inaccuracies or typographical errors or delays in updating the said information. Hence, users are advised to independently exercise diligence by verifying complete information, including by consulting experts, if any. Users shall be the sole owner of the decision taken, if any, about suitability of the same.