








Rs. 100- Rs. 10 crore
Start investing with Rs. 100 | Easy KYC | Expert-managed funds
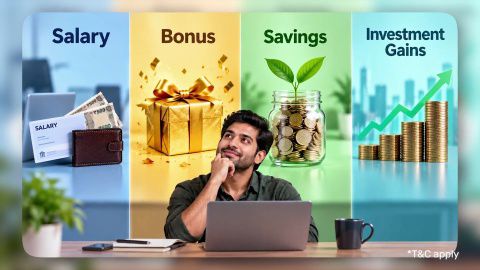
Mental Accounting
In summary
Mental accounting happens when you divide your money into separate mental categories instead of considering your overall financial position.
- Mental accounting can affect how you spend, save, borrow, and invest.
- You may treat a bonus differently from your regular salary.
- Investment gains may feel different from money earned through work.
- Mental accounting can encourage useful goal-based saving when used deliberately.
- It can also lead to inconsistent financial decisions when emotional categories override financial priorities.
- Reviewing your complete financial position can help you identify these biases.
- Mutual fund investments remain subject to market risk regardless of how you mentally categorise them.
Mental accounting does not always lead to poor decisions. The key is to use financial categories as planning tools without allowing them to distort your overall decisions.
What is mental accounting?
Mental accounting is the tendency to divide money into separate mental “buckets” based on where it came from, what you intend to use it for, or how you feel about it.
The concept is associated with economist Richard Thaler and is studied under behavioural finance, which examines how psychological factors can influence financial decisions.
For example, you might carefully budget your monthly salary but spend a tax refund or bonus more freely because you consider it “extra” money. Financially, both amounts belong to you, but you may treat them differently.
Mental accounting can influence everyday spending as well as decisions involving investments, savings, and debt.
What are common examples of mental accounting?
Mental accounting can appear in ordinary financial decisions without you consciously recognising it.
Spending bonus money differently
You may use a festival bonus for discretionary spending while treating your regular salary as money for household expenses, savings, and investments.
This can be useful if the bonus has been deliberately allocated for discretionary spending. It can become unhelpful when the label “extra money” encourages spending that does not fit your overall budget.
Keeping savings while carrying expensive debt
You may keep money in a savings account while carrying high-interest credit card debt because you mentally classify your savings as a protected amount.
The two amounts are financially connected, even though they sit in different accounts. Looking at the interest earned on your savings and the interest paid on your debt can give you a broader picture.
Treating investment profits as free money
After making a profit on an investment, you may become more willing to take risks because the gain feels less valuable than your original money.
This can result in a decision that does not match your overall risk tolerance or financial goals.
Protecting money for a specific goal
You may keep a separate amount for a holiday, emergency, education, or retirement and avoid spending it on unrelated expenses.
This is not necessarily a problem. Goal-based saving can make it easier to maintain financial discipline.
How does mental accounting affect financial decisions?
Mental accounting can make you focus on individual amounts rather than your overall financial position.
| Financial situation | Mental category | Possible effect |
|---|---|---|
| Salary | Regular income | More careful budgeting |
| Bonus or gift | Extra money | Higher discretionary spending |
| Investment gain | Free or house money | Greater willingness to take risk |
| Emergency savings | Untouchable money | Reluctance to use it when genuinely needed |
| Credit card debt | Future problem | Delayed repayment |
Last updated: September 2026
These are examples of possible behavioural patterns, not outcomes that occur in every situation. The same mental category can have a different effect depending on your financial circumstances.
How does mental accounting affect investing?
Mental accounting can affect how you evaluate gains, losses, and individual investments.
Suppose Riya invests Rs. 50,000 in a mutual fund. Its value later falls to Rs. 40,000. She may continue holding it simply because she wants to recover the original Rs. 50,000.
At the same time, another investment may generate a Rs. 10,000 gain, which she considers “extra money” and uses for a high-risk investment.
These decisions may be influenced by how Riya mentally labels the money rather than by her overall financial goals and portfolio.
Mental accounting can contribute to behaviours such as:
- Holding an investment because of its original purchase price.
- Taking additional risk after making short-term gains.
- Focusing on one investment instead of the complete portfolio.
- Treating investments for different goals as completely separate.
- Overlooking concentration or duplication across investments.
The SEBI Riskometer can help you understand the stated risk level of a mutual fund scheme. The six categories are Low, Low to Moderate, Moderate, Moderately High, High, and Very High. It describes scheme risk and does not predict returns or eliminate the possibility of losses.
Is mental accounting always harmful?
No. Mental accounting can sometimes support better financial discipline.
For example, keeping a separate emergency fund can reduce the temptation to spend money meant for unexpected expenses. Similarly, allocating a fixed amount towards retirement or education can help you stay focused on a long-term goal.
The problem arises when the mental category becomes more important than the underlying financial objective.
For example, you might keep low-return savings untouched while carrying expensive debt because you consider the savings “off limits”. Similarly, you might take excessive investment risk because a recent gain feels less important than your original investment.
The aim is not necessarily to eliminate financial categories. It is to recognise when they are helping you and when they may be distorting your decisions.
How can you reduce mental accounting bias?
You can reduce the influence of mental accounting by periodically reviewing your complete financial position.
Review your overall financial position
Consider your savings, investments, debt, income, expenses, and financial goals together rather than reviewing each account separately.
Your net worth can provide a broader view because it considers your assets after deducting your liabilities.
Compare debt costs with savings returns
If you are keeping money in a low-return account while paying a higher interest rate on outstanding debt, compare the two before deciding how to use your money.
The objective is to understand the overall financial effect rather than treating savings and debt as unrelated categories.
Review investment costs
When comparing mutual funds, do not focus only on recent returns. Costs can also affect your investment outcome over time.
The Total Expense Ratio represents the expenses charged by a mutual fund scheme as a percentage of its assets. Understanding this cost can help you assess a scheme more completely.
Review risk objectively
Avoid increasing investment risk simply because a recent investment has generated a profit.
Consider your financial goals, investment horizon, risk tolerance, diversification, and the characteristics of the investment before making changes.
Standard Deviation is one measure used to understand the variability of an investment's returns. It should not be used on its own to determine whether a mutual fund is suitable.
How does mental accounting relate to mutual funds?
Mental accounting can affect how you divide and evaluate mutual fund investments.
You might hold one fund for retirement, another for a child's education, and another for a short-term goal. Assigning investments to specific goals can make your financial plan easier to organise, but you should still review the portfolio as a whole.
For example, holding five funds for five different goals does not automatically mean your portfolio is diversified. Different schemes can hold similar securities or have similar risk exposures.
If you are considering how to invest in equity mutual funds, consider your investment objective, risk tolerance, investment horizon, diversification, and the characteristics of the scheme rather than selecting a fund based only on how a particular amount of money feels.
On the Bajaj Broking website, you can explore 4,000+ mutual fund schemes across equity, debt, hybrid, ELSS, and thematic categories. Eligible schemes may offer SIP or lumpsum investment options, subject to scheme terms.
KYC is mandatory before investing. Where applicable, SIP investments can start from Rs. 100 per month, subject to the terms of the selected scheme.
Can mental accounting affect debt management?
Yes. Mental accounting can make you treat borrowed money and savings as separate issues even though both affect your overall financial position.
For example, you may preserve a savings balance because it feels important to have “money in the bank” while continuing to pay interest on an outstanding credit card balance.
Reviewing your assets, liabilities, interest costs, and cash requirements together can provide a clearer picture.
However, you should also maintain an appropriate cash reserve for essential expenses. Paying down debt should not automatically mean using all your available savings.
How can you use mental accounting positively?
You can use separate financial categories deliberately when they support a clear financial plan.
For example, you might allocate money towards:
- Emergency expenses.
- Short-term financial goals.
- Long-term investments.
- Retirement planning.
- Planned discretionary spending.
The distinction is between deliberate budgeting and emotional labelling.
A deliberate allocation is based on a financial objective. Mental accounting becomes problematic when the label attached to money causes you to ignore costs, risks, debt, or competing financial priorities.
Conclusion
Mental accounting is a behavioural finance bias that can influence how you spend, save, borrow, and invest. Separate financial categories can support discipline when they are based on genuine goals, but emotional labels can also lead to inconsistent decisions.
Reviewing your finances as a whole can help you identify whether your mental categories are supporting your objectives or affecting your decisions. When investing, consider your goals, risk tolerance, diversification, costs, and investment horizon rather than judging each amount in isolation.
Last reviewed: September 2026
Mutual funds are subject to market risk. Please read the scheme-related documents carefully before investing.
Explore Investment Tools
Articles and Insights
Frequently Asked Questions
Understanding mental accounting
Mental accounting and investing
Why do people use mental accounting?
People naturally attach different meanings to money based on its source, purpose, or how they acquired it. Salary, bonuses, gifts, and investment gains can therefore feel different even when they have the same monetary value. Behavioural finance studies these patterns to understand how psychological factors influence financial decisions.
Is mental accounting the same as budgeting?
No. Budgeting is a deliberate process of planning how you will use your income and resources. Mental accounting is a behavioural tendency to categorise money. You can use separate categories in a budget without allowing those categories to distort your broader financial decisions.
Can mental accounting make investors hold losing investments?
It can contribute to this behaviour. An investor may become attached to an investment because of the price originally paid or a desire to recover a particular loss. A more objective review considers the investment's current suitability, risk, financial goals, and alternatives rather than focusing only on the original purchase price.
Can mental accounting affect diversification?
Yes. You may treat investments assigned to different goals as completely separate even when they hold similar securities or asset classes. Reviewing the entire portfolio can help you identify concentration and overlap that may not be obvious when each goal is considered separately.
Disclaimer
Bajaj Finance Limited ("BFL") is registered with the Association of Mutual Funds in India ("AMFI") as a distributor of third party Mutual Funds (shortly referred as 'Mutual Funds) with ARN No. 90319
BFL does NOT:
(i) provide investment advisory services in any manner or form.
(ii) carry customized/personalized suitability assessment.
(iii) carry independent research or analysis, including on any Mutual Fund schemes or other investments; and provide any guarantee of return on investment.
In addition to displaying the Mutual fund products of Asset Management Companies, some general information is sourced from third parties, is also displayed on As-is basis, which should NOT be construed as any solicitation or attempt to effect transactions in securities or the rendering any investment advice. Mutual Funds are subject to market risks, including loss of principal amount and Investor should read all Scheme/Offer related documents carefully. The NAV of units issued under the Schemes of mutual funds can go up or down depending on the factors and forces affecting capital markets and may also be affected by changes in the general level of interest rates. The NAV of the units issued under the scheme may be affected, inter-alia by changes in the interest rates, trading volumes, settlement periods, transfer procedures and performance of individual securities forming part of the Mutual Fund. The NAV will inter-alia be exposed to Price/Interest Rate Risk and Credit Risk. Past performance of any scheme of the Mutual fund do not indicate the future performance of the Schemes of the Mutual Fund. BFL shall not be responsible or liable for any loss or shortfall incurred by the investors. There may be other/better alternatives to the investment avenues displayed by BFL. Hence, the final investment decision shall at all times exclusively remain with the investor alone and BFL shall not be liable or responsible for any consequences thereof.
Investment by a person residing outside the territorial jurisdiction of India is not acceptable nor permitted.
Disclaimer on Risk-O-Meter:
Investors are advised before investing to evaluate a scheme not only on the basis of the Product labeling (including the Riskometer) but also on other quantitative and qualitative factors such as performance, portfolio, fund managers, asset manager, etc, and shall also consult their Professional advisors, if they are unsure about the suitability of the scheme before investing.
Disclosure: Bajaj Finance Limited (BFL) is a distributor of Mutual Funds with ARN - 90319 and distributes mutual funds of Bajaj Finserv Asset Management Limited (BFSAMC). BFL receives commission towards distribution of mutual fund products. BFSAMC is a group company of BFL, carrying business on arm’s length basis without any conflict of interest and in accordance with the prevailing law / regulation.
Disclaimer
Bajaj Finance Limited ("BFL") is an NBFC offering loans, deposits and third-party wealth management products.
The information BFL contained in this article is for general informational purposes only and does not constitute any financial advice. The content herein has been prepared by BFL on the basis of publicly available information, internal sources and other third-party sources believed to be reliable. However, BFL cannot guarantee the accuracy of such information, assure its completeness, or warrant such information will not be changed.
This information should not be relied upon as the sole basis for any investment decisions. Hence, User is advised to independently exercise diligence by verifying complete information, including by consulting independent financial experts, if any, and the investor shall be the sole owner of the decision taken, if any, about suitability of the same.
Disclaimer
Mutual Fund SIP calculator may provide potential investors an approximate estimate on the maturity amount of the monthly SIP, purely based on mathematical calculation of the projected annual return rate selected by investor. However, such calculation does not factor the actual performance by the Asset Management Company (AMC) and should not be treated as any advice or assurance about the actual return of investment. Mutual Funds do not have a fixed rate of return and it is not possible to predict the rate of return. Please note that the SIP calculator are for illustrations only and do not represent actual returns which may vary depending on various factors including but not limited to actual performance, expense ratio, taxation, exit load (if any), etc.